How Much Brand Activation Design Service Owners Make: $150k+ Year 1
Brand Activation Design Service Bundle
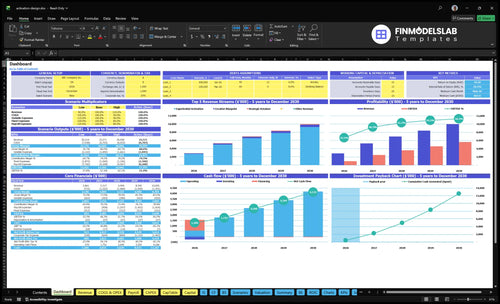
You’re trying to separate agency revenue from the cash an owner can actually take home This model covers Year 1 revenue of $2861M, $953k EBITDA, payroll, overhead, reserves, and the $150k Creative Director role before taxes, financing detail, or personal expenses
Owner income$150kNet margin33% to 56%Revenue for target pay$451kBusiness difficultyHard
Want to test your owner pay?
Owner income calculator
Estimate owner take-home and target-pay gap from revenue, margin, costs, reserves, and target pay.
!
Planning note: This is a researched planning estimate, not guaranteed salary, tax advice, or owner distribution advice.
What drives owner income most?
1
Project Pricing
$175-$300/hr
At $175-$300 per billable hour, even small rate gains lift take-home fast because most work is sold by time.
2
Project Volume
$2.9M-$10.0M
Revenue grows from $2.861M in Year 1 to $10.005M in Year 5, so booked project count is the biggest income lever.
3
Margin Control
25%-17%
Keeping COGS down from 25% to 17% protects gross profit and leaves more cash after fabrication and freelance help.
4
Repeat Work
10%-30%
Retainers rising from 10% to 30% smooth cash flow and cut selling drag, so more revenue sticks.
5
Staffing Model
$535K-$1.48M
Wages climb from $535K to $1.48M, so hiring ahead of demand can quickly eat profit from new sales.
6
Overhead Buffer
$312K/$668K
Fixed overhead runs about $312K a year, and minimum cash hits $668K, so reserves decide how long you can hold growth.
Need the full projection view for Brand Activation Design Service?
Can a brand activation design service owner make six figures?
Yes, a Brand Activation Design Service owner can make six figures if they personally fill the $150k Creative Director role and the agency hits its delivery plan; see What Are Operating Costs For Brand Activation Design Service? for the cost base behind that answer. Year 1 shows $2.861M revenue and $953k EBITDA before taxes and reserves, so the model has room for six-figure owner pay, but it isn’t guaranteed.
Six-Figure Path
Owner fills $150k creative lead role
Year 1 revenue reaches $2.861M
EBITDA lands at $953k
Repeat clients lower sales pressure
Watch The Risk
Keep fabrication and freelance COGS near 25%
COGS means direct delivery costs
EBITDA is before taxes and reserves
No guaranteed salary or tax guidance
How much revenue does a brand activation agency need to pay the owner?
If the Brand Activation Design Service owner wants $150k pay, $26k/month fixed overhead, and $535k Year 1 payroll, the business needs about $1.424M in revenue before reserves. With 70% contribution after COGS and variable costs, the actual model revenue is $2.861M, which gives more room for reserves and owner pay.
Core pay math
$26k monthly overhead
$312k yearly overhead
$535k Year 1 payroll
$150k owner salary
Revenue needed
70% contribution rate
$997k total pay and overhead
$1.424M revenue before reserves
$2.861M model revenue target
How does scaling a brand activation design service change owner income?
Scaling the Brand Activation Design Service can raise owner income, but only if pricing and utilization hold. Here’s the quick math: revenue grows from $2.861M in Year 1 to $10.005M in Year 5, payroll rises from $535k to $1.48M, and EBITDA margin improves from 33.3% to 56.5%. A solo founder keeps overhead low but caps project capacity, and the model needs $668k of minimum cash in Month 5.
Income upside
Solo setup keeps overhead low
Small studio adds delivery capacity
Staffed agency scales best
Margins rise if utilization holds
Cash and payroll
Payroll climbs fast with headcount
Month 5 cash need hits $668k
Reserve cash before owner draws
Protect pricing on every project
Key Takeaways
Higher scopes and cleaner change orders lift owner take-home.
Volume must stay profitable without burning out the team.
Margin leaks from freight, delays, and subcontractor overages.
Cash reserves bridge deposits, vendor pay, and collections.
Compare lean, base, and high owner income scenarios
Owner income scenarios
Owner income shifts with project mix, staffing, and pass-through costs. Revenue scales from Year 1 to Year 5, but reserve needs stay real and distributions are not guaranteed.
Low, base, and high cases show how the operating setup changes owner pay.
Scenario
Low CaseLow Case
Base CaseBase Case
High CaseHigh Case
Launch model
This is the lower-income path built on smaller projects and a lean cost base.
This is the researched Year 1 operating case.
This is the stronger-scale path tied to Year 5 output.
Typical setup
Work centers on fewer activations, a smaller team, and tighter spend, so owner pay stays closer to salary only.
This is the Year 1 model with $2.861M revenue, 25% COGS, 5% variable costs, $535k wages, and $312k fixed overhead.
This is the mature-scale case with $10.005M revenue, 17% COGS, 2% variable costs, and $1.48M wages, but cash reserves still matter.
Cost drivers
Lower project volume
leaner staffing
tighter overhead
salary-only owner pay
Year 1 revenue $2.861M
COGS 25%
variable costs 5%
wages $535k
fixed overhead $312k
Year 5 revenue $10.005M
COGS 17%
variable costs 2%
wages $1.48M
reserve needs stay high
Owner income rangeBefore owner reserves
Salary onlySalary only
$150,000Modeled pay
Upside onlyUpside only
Best fit
Use it if you want to stress-test a slow start or weak sales pipeline.
Use it for planning, lender talks, and investor reviews.
Use it to test upside, but keep a reserve because distributions are not guaranteed.
!
Planning note: Scenario ranges are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distributions.
Brand Activation Design Service Core Six Income Drivers
Project Pricing And Scope
Scope Pricing
Higher-value scopes push more revenue into each project, so the owner keeps more after payroll and overhead. At $250/hour in Year 1, a 120-hour activation bills $30,000; at $300/hour in Year 5, it bills $36,000. Creative blueprints move from $175/hour to $220/hour, and retainers rise from $200/hour to $250/hour.
The risk is scope creep: design revisions, install complexity, travel, and vendor coordination can all add hours without adding price. If those pieces are not priced up front, gross margin drops and owner pay gets squeezed even when sales look strong.
Scope Control
Price the job around hours by phase, revision rounds, travel, and vendor pass-throughs. Use a written change-order trigger when the client adds work, and keep reimbursables outside labor rates. That keeps the realized hourly rate close to the target instead of drifting down during delivery.
Track planned versus actual hours.
Cap revision rounds in writing.
Mark up pass-through costs clearly.
When actual hours climb but price does not, margin falls fast. The clean fix is tighter scope and faster change orders, not more unpaid effort from the owner.
Client Mix And Repeat Work
Repeat Clients And Recurring Mix
Repeat clients help this business smooth cash flow between big installs and keep staffing less chaotic. The mix shifts toward more stable revenue: activation allocation rises from 70% to 90%, strategic retainers from 10% to 30%, and creative blueprints from 20% to 28%. When those recurring hours are priced well, owner draw gets steadier.
The risk is loading the team with low-margin custom work that never repeats. Here’s the quick math: more retainers usually mean better utilization between installation cycles, but only if scope stays tight and revisions stay controlled. If repeat work is mostly ad hoc, it can lift revenue and still drag profit because labor fills up faster than cash does.
Build Recurring Revenue Into Every Account
Track repeat-client share, retainer hours, and margin by project type so you can see which accounts actually support owner pay. A healthy mix pairs large activations with recurring planning work, not endless one-off custom builds. One clean rule: if a retainer does not cover idle time between installs, it is not stabilizing income.
Use a simple client-level forecast: expected activation dates, retainer billing, billable hours, and revision load. Price recurring planning so it protects gross margin, then cap custom changes with clear scope rules. That keeps the team from getting buried in work that looks busy but leaves little profit after labor, vendor costs, and overhead.
Measure repeat revenue by client.
Separate retainer and activation hours.
Cap revisions before work starts.
Forecast cash by install cycle.
Gross Margin Control
Gross Margin Control
Gross margin is revenue left after direct production costs, before payroll and overhead. For this model, Year 1 direct COGS is 25% — 15% fabrication and materials plus 10% freelance specialists — and Year 5 improves to 17%. On $100,000 of project revenue, that means $75,000 gross margin in Year 1 and $83,000 in Year 5, before fixed costs and owner pay.
Variable costs add another 5% in Year 1 and 2% in Year 5. Every unpriced freight run, install delay, or subcontractor overage cuts the cash left for salaries, overhead, and the owner’s draw. The key inputs are billed revenue, fabrication and material spend, freelance labor, and pass-through costs. If any of those slip, owner-pay capacity drops fast.
Protect the margin on every activation
Track direct COGS by job, not just by month. Split each project into fabrication, materials, freelance specialists, freight, and install overruns, then compare plan to actual. The target is simple: move from 25% to 17% direct COGS and from 5% to 2% variable costs as the process gets tighter.
Price change orders for scope creep, extra travel, and rework before the work starts. If a client adds a late install day or a new subcontractor, bill it immediately or your gross margin becomes hidden owner labor. Here’s the rule: if the cost is tied to one project, it should be booked to that project.
Staffing And Subcontractor Strategy
Staffing And Subcontractor Mix
Staffing is the main bridge between booked work and owner pay. The Year 1 core team is one Creative Director, one Senior Producer, two Experiential Designers, and one Account Manager, with $535k payroll. Freelancers add 10% of revenue, so lean hiring protects cash, but it also means the owner can become the backstop for creative, production, and client fire drills.
In Year 5, payroll reaches $148M and freelancer cost drops to 6% of revenue. That can lift capacity and reduce chaos, but only if the project pipeline stays full. If headcount grows faster than billable work, margin shrinks first, then owner draw gets squeezed. One line: underbuilt teams save cash, but they cap delivery.
Track Labor Before It Hits Profit
Track staffing by role, not just headcount. Watch payroll as a share of revenue, freelancer spend as a share of revenue, and utilization, meaning billable time. If the owner keeps stepping into production or account management, the team is too thin and sales time gets lost. That is where owner income starts to stall.
Set utilization targets by role.
Cap freelancer spend at plan.
Review overload before each launch.
Build the staffing plan from booked pipeline, not hope. Add producers and designers before quality slips, then use freelancers first when demand softens so cash stays flexible. The goal is simple: enough bench to deliver, but not so much payroll that profit and owner pay get crowded out.
Annual Project Volume And Capacity
Annual Project Volume and Capacity
Owner income depends on profitable volume the team can deliver without burnout. In Year 1, each active customer averages 140 billable hours/month, rising to 160 by Year 5, while activation hours per project fall from 320 to 280. That means the same team can carry more revenue if delivery stays tight and rework stays low.
Pipeline timing matters because CAC starts at $15k and improves to $12k. Here’s the quick math: a 12.5% drop in activation hours raises capacity, but seasonal gaps can still drain cash between deposits and final collection. Annual profit can look strong while owner pay stays uneven.
Track Capacity Before Chasing More Bookings
Measure active customers, billable hours, and activation hours every month. If hours per project move from 320 to 280, that is about 14.3% more capacity per hour block. If overtime, revision cycles, or install delays rise with volume, the extra revenue won’t reach the owner’s draw.
Build the sales plan around the next 60 to 90 days of work, not just annual targets. Watch deposits, vendor prepayments, and final billing dates by project. A $15k CAC leaves little room for idle pipeline, so smoother booking flow usually matters more than chasing one big quarter.
Fixed Overhead And Cash Reserves
Fixed Overhead And Cash Reserves
Fixed overhead is the monthly cash burn you pay before project profit lands. Here, the stated burn is $26k/month or $312k/year, and the model says minimum cash need reaches $668k in Month 5. That matters because owner pay only works when cash timing stays ahead of overhead.
Track the fixed lines that do not move with each project: rent and utilities, insurance, software, IT, admin and legal, plus marketing and brand development. If any of those costs rise, take-home income drops fast because the business funds the gap before profit can be drawn.
Reserve Enough Cash To Keep Paying Yourself
Use a simple cash forecast: monthly fixed overhead, client deposits, vendor payment dates, and final collection dates. The key test is whether cash stays above $668k in Month 5. If not, delay hiring, cut nonessential spend, or tighten payment terms before owner draws get squeezed.
One clean rule: keep reserves tied to timing risk, not just annual profit. Even strong projects can miss cash timing if a deposit slips or a final invoice lands late, and that is when overhead eats the owner’s income.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.