How Much ADU Construction Owners Can Make: $145k To $23M
Accessory Dwelling Unit Construction Bundle
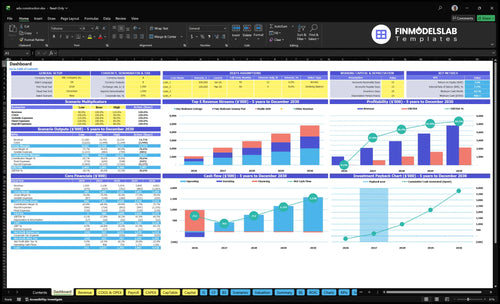
An ADU construction business owner can make about $145k in salary in the first year if they fill the Managing Director role, with little room for distributions because EBITDA is only $1k By the fifth year, the same model shows $4833M in revenue and $2151M in EBITDA, so potential pre-tax owner compensation could reach about $2296M before taxes, debt service, reserves, and reinvestment These are researched planning assumptions, not guaranteed take-home pay The main swing factors are completed projects, average contract value, direct job costs, payroll, overhead, and cash reserves
Owner income$145k–$2.3MNet margin0.1%–44.5%Revenue for target pay$1.06MBusiness difficultyHard
Want the six ADU income drivers?
1
Project Volume
$1.1M-$4.8M
More completed ADUs drive the biggest income lift, with revenue growing from $1.059M in Year 1 to $4.833M in Year 5.
2
Contract Value
$145-$185/hr
Higher hourly pricing and a bigger share of two-bedroom work raise revenue per project without needing the same jump in jobs.
3
Gross Margin
70%-75%
Direct costs fall from about 30% of sales to 25%, so every saved point drops straight into EBITDA.
4
Crew Capacity
120-140h
More billable hours per active customer let the team take on more work, but only if labor stays matched to demand.
5
Sales Pipeline
$4.5K-$3.5K
Lower CAC makes each lead cheaper to win, and cleaner permit flow keeps projects moving into production.
6
Overhead Discipline
$129K/$607K
Fixed overhead and reserve control protect the 7-month breakeven and keep owner cash from getting squeezed.
Want to test your ADU owner pay?
Owner income calculator
Estimate owner take-home and the target-pay gap from revenue, margin, costs, reserves, and target pay.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
What gross margin should an ADU construction business target?
Target model gross margin as the planning anchor, not a national rule. In Accessory Dwelling Unit Construction, direct cost load is 300% in Year 1 and 252% in Year 5, so gross margin moves from 700% to 748%; for a deeper dive, see How Increase Accessory Dwelling Unit Construction Profitability? A 2-point margin miss on $2.919M of revenue cuts about $58k from gross profit.
Margin drivers
Materials set the base cost.
Subcontractors move the margin fast.
Sitework and permits add load.
Change orders and contingency matter.
Watch the math
Use gross margin as the anchor.
Gross margin is not net profit.
It is not owner take-home.
Scheduling affects cost control.
Is an ADU construction business profitable to scale?
Accessory Dwelling Unit Construction can scale, but profit only follows if throughput, job costing, and cash stay tight. A managed-crew setup can lift revenue from $10.59M to $48.33M, but it also needs $607k of minimum cash and about 21 months to pay back. A lean owner-operator model protects overhead but caps completed projects, and scaling does not automatically raise owner distributions.
What helps scale
Keep crews busy every week
Track job costs tightly
Use senior PMs at $95k
Protect cash for 21 months
Main profit risks
Owner-operator limits output
Subcontractors can squeeze margin
Trade pricing can move fast
Schedule slips hit cash
How many ADU projects do I need to make money?
You make money on completed, collected ADU projects, not on leads or signed contracts. On the model math, marketing budget divided by CAC points to about 10 acquired customers in Year 1, 19 in Year 3, and 29 in Year 5, with revenue per acquired customer rising from about $106k to $169k. Break-even lands in Month 7, and target pay has to cover a $145k owner salary, $129k annual fixed overhead, payroll, job costs, and reserves.
Cash math
Count only finished, paid jobs
Ignore leads and signed deals
Year 1: about 10 customers
Revenue per customer: $106k to $169k
Break-even
Break-even in Month 7
Year 3: about 19 customers
Year 5: about 29 customers
Cover $145k pay and $129k overhead
Key Takeaways
Completed projects drive revenue, not inquiries.
Bigger ADUs raise revenue but strain cash.
Gross margin must cover payroll, overhead, reserves.
Minimum cash need peaks at $607k in Month 7.
Compare low, base, and high ADU owner-income outcomes
Owner income scenarios
Owner income shifts with ramp, scale, and reserve needs because payroll and office costs stay fixed while project margin improves over time.
Low, base, and high cases show how owner pay changes from launch year to mature scale.
Scenario
Low CaseRamp
Base CaseScaled
High CaseMature
Launch model
This is the lower owner-income path during the first-year ramp.
This is the modeled middle path once Year 3 scale is in place.
This is the stronger owner-income path at mature Year 5 scale.
Typical setup
Year 1 brings $1.059M revenue, about 70.0% gross margin, and $1k EBITDA, so the owner mostly takes salary and keeps cash tight.
Year 3 reaches $2.919M revenue, about 72.4% gross margin, and $1.058M EBITDA, which can support salary plus some distributions after reserves.
Year 5 reaches $4.833M revenue, about 74.8% gross margin, and $2.151M EBITDA, so owner income can stack salary and EBITDA-level upside before taxes, debt, and reinvestment.
Owners planning from Year 3 scale with reserve checks.
Owners modeling mature-year upside and reinvestment needs.
!
Planning note: These ranges are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distributions.
Accessory Dwelling Unit Construction Core Six Income Drivers
Project Volume And Completion Rate
Project Volume And Completion Rate
This driver is the number of accessory dwelling unit (ADU) projects that move from signed job to completed and collected cash. The model’s marketing budget and CAC imply about 10 acquired customers in Year 1 and 29 in Year 5, with revenue rising from $1.059M to $4.833M as more jobs finish. Completed work, not inquiries, is what pays gross profit and owner draws.
Here’s the hard part: delays in permits, inspections, subcontractors, or homeowner funding push revenue and owner distributions out. No completion, no cash. If quality slips or collections slow down, booked work can still leave the business short on payroll, overhead, and profit available to pay the owner.
Measure Completion, Not Leads
Track the full path from inquiry to signed scope, permit, start, completion, and collection. The key test is completed and collected projects ÷ acquired customers. A strong inquiry count with weak completion burns CAC and traps cash in preconstruction.
Track permit turnaround by job.
Track starts, completions, collections.
Flag funding gaps before mobilization.
Forecast monthly completion capacity.
Use those dates to spot where revenue gets stuck. If permits or inspections slip, finished revenue moves right, and owner pay moves with it.
Overhead, Reserves, And Working Capital
Overhead, reserves, and cash gap
Owner take-home starts after fixed overhead, payroll, capex funding, and reserve build. Here’s the quick math: fixed overhead is $10,750 per month, or $129,000 per year; payroll runs $490,000 to $950,000; and capex totals $218,000. The model’s minimum cash need reaches $607,000 in Month 7, so paper profit can’t be paid out until cash is there.
This driver matters because reserves are separate from taxes and distributions. If milestone billing slows or permits delay starts, cash gets tied up in payroll and overhead first. The main inputs are payroll timing, overhead, capex timing, and how much cash each job collects at each milestone.
Track cash before owner draws
Track a rolling 13-week cash forecast, not just P&L profit. Watch cash on hand against the $607,000 reserve floor, plus payroll dates and capex timing. If the reserve is below target, hold owner draws and protect liquidity first.
Cash balance versus $607,000
Payroll due dates
Capex payment timing
Milestone collections
Owner draws and reserves
If collections slip, the business can look profitable and still run short on cash. That is why the reserve target should sit ahead of owner pay, not after it.
Sales Pipeline, Design, And Permitting Conversion
Inquiry to Permit Conversion
Income here depends on how fast inquiries turn into signed scope, design, permit, start, completion, and collection. If conversion slips at any step, revenue gets pushed out and owner pay follows. In Year 1, project-specific permits run about 30% of revenue, then ease to 22% by Year 5, so preconstruction cost is a real cash drag until jobs clear permit.
Here’s the quick math: marketing rises from $45k to $100k, while CAC improves from $4,500 to $3,500. That only helps if more leads become signed, permitted starts. If too many projects stall before approval, the team can burn cash on design and permit work without getting to collection, which squeezes profit and delays distributions.
Cut Stalls Before Permit
Track the funnel by stage, not just lead count: inquiry, signed scope, design complete, permit filed, permit approved, start, completion, and cash collected. One clean metric is the permit conversion rate from signed scope to approved permit, because that is where preconstruction cash gets trapped.
Set a cap on work-in-process before permit approval, then forecast preconstruction spend per active job. If that queue grows faster than starts, cash tightens even when sales look strong. The fix is simple: tighten scope documents, submit complete permit sets, and stop selling more preconstruction than the team can clear.
Track stage-by-stage conversion rates.
Monitor preconstruction cash per job.
Compare CAC to collected revenue.
Limit stalled jobs before permit.
Gross Margin And Job Cost Control
Job Cost Control
Owner income rises when each ADU estimate covers materials, trades, permits, commissions, contingency, and change orders. In this model, direct cost load falls from 300% to 252%, so more contract cash stays in gross profit. That gross margin then has to fund payroll, overhead, reserves, and owner distributions.
The biggest leak is underbilled scope. Materials run 180% in Year 1 and 160% in Year 5, while subcontractors move from 80% to 60%. If those lines slip, the job may still finish, but the owner’s draw gets pushed out because the margin never arrives. One missed line item can wipe out several clean jobs.
Measure Every Cost Bucket
Build each estimate from the same buckets: materials, subcontractors, permits, commissions, contingency, and change orders. Then compare estimated vs. actual job cost on every completed ADU. If one line runs hot twice, raise price before you add more volume. That protects margin and keeps cash available for owner pay.
Track estimate vs. actual by job line.
Price change orders before work starts.
Review cost overruns after each closeout.
Forecast cash after permit and sub bills.
Keep margin high enough to cover payroll, overhead, and reserves. If a job looks profitable only before permits, subs, or change orders hit, the owner ends up funding the gap instead of taking home profit. Clean job costing turns revenue into real distributions.
Labor, Subcontractor, And Scheduling Capacity
Labor and Scheduling Capacity
Capacity is what turns signed ADU work into finished, billable jobs. Payroll rises from $490k in Year 1 to $950k in Year 5, while senior project managers grow from 1 FTE to 4 FTE at $95k each and architectural designers from 1 to 2 FTE. If that staff sits idle, EBITDA drops and owner draws shrink.
The driver depends on active projects, staffing, subcontractor lead times, permit timing, inspections, and completion rate. More completions mean more revenue and cash collected. Delays do the opposite: they push milestone billing out, trap labor costs in work not yet finished, and can turn booked revenue into working-capital strain.
Track Utilization Weekly
Measure projects per PM, designer queue, and subcontractor start dates every week. If headcount grows before completions do, you are buying idle payroll. Keep each FTE tied to a billed milestone, not bench time.
Active jobs per project manager
Design queue days
Permit age and inspection dates
Subcontractor commitment dates
Forecast cash by milestone, not just signed contract value. One late trade can block the next start, delay collection, and hit owner income twice: lower throughput and higher payroll drag.
Average Contract Value And Project Mix
Contract Value Follows Scope Mix
Average contract value in ADU work comes from project scope, not a single national price. With billable assumptions of 85, 120, and 160 hours by project type, and hourly pricing rising from $145 to $185, contract value can swing a lot. A studio at 85 hours and $145/hour is $12,325; a two-bedroom at 160 hours and $185/hour is $29,600.
That mix matters for owner pay. The project mix shifts from 40% studio, 40% one-bedroom, 20% two-bedroom in Year 1 to 20%, 45%, 35% in Year 5, so revenue per job can rise even if job count stays flat. Bigger ADUs can lift revenue, but they also raise permitting, sitework, labor, and working-capital needs, so cash gets tied up longer before milestone billing clears.
Price The Mix, Not The Average
Track contract value by unit type, not by total pipeline. Build every estimate from hours × rate, then add scope items that change with size, like permits and sitework. If your two-bedroom share rises, forecast higher revenue and higher cash use together, or owner draws can get squeezed even when topline looks strong.
Track studio, one-bedroom, two-bedroom mix.
Reprice when hours or scope change.
Watch permit and sitework cash timing.
Separate quoted value from collected cash.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.