Does Owner Income in an After-School Program Depend More on Volume or Margin?
After-School Program Bundle
A U.S. after-school program owner can plan for roughly $15,700 to $109,200 a year in owner income after modeled tax and reinvestment reserves, with a base case of $66,360 on $336,000 of annual revenue. This article models an owner-directed, licensed 60-slot school-age center in a mid-cost market with a 1:15 staffing benchmark. The largest constraints are occupied seats, weekly tuition, payroll, facility overhead, debt, and reserves. Owner income is not revenue, EBITDA, or guaranteed salary; the owner works as director and no separate director is in payroll.
Owner income$66KNet margin20%Revenue for target pay$335KBusiness difficultyModerate
How much can an After-School Program owner make?
For this 60-slot owner-directed model, the base answer is $66,360 a year after the calculator’s tax and reinvestment reserves. The planning range is wide because school-age prices vary sharply by state and local market. Child Care Aware of America explicitly says school-age prices are too variable to include in its national average calculation, so a founder should resist using one national tuition number; its 2026 methodology instead supports state-level pricing work. For a transparent mid-cost benchmark, Delaware’s 2024 market-rate survey reported 75th-percentile center prices of roughly $30 to $33.95 per day for school-age care under four hours, which is why this model uses a more conservative $150 weekly base tuition rather than a premium metropolitan rate.
The base model averages $28,000 monthly revenue, or $336,000 a year: about 54 enrolled children across 39 school weeks at $150 per week, plus roughly $20,000 of registration, school-closure, and limited enrichment revenue. Non-labor direct costs are assumed at 10% of sales, leaving a 90% gross margin before payroll; that is a planning assumption, not an industry statistic.
After $6,500 of monthly non-owner payroll, $8,000 of fixed overhead, $800 of marketing, and $2,000 of debt service, profit before reserves is $7,900. A 22% tax reserve plus 8% reinvestment reserve leaves $5,530 a month, or $66,360 annually. The owner is excluded from payroll to avoid double counting.
Owner income calculator
Test how enrollment-driven revenue, margin, staffing, overhead, debt, and reserves change owner take-home.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
1
Occupied seats
54 of 60 base
Every consistently filled seat spreads fixed facility and director costs over more tuition dollars; empty seats are the fastest way to compress owner cash.
2
Weekly tuition
$150 base
A $5 weekly change across 54 children and 39 school weeks moves annual revenue by about $10,530 before direct cost and reserve effects.
3
Staffing coverage
1:15 benchmark
Ratio-driven hiring creates cost steps. Crossing a child-count threshold can require another staff member even before the extra tuition fully covers that wage.
4
Direct program cost
10% of sales
Snacks, supplies, activities, merchant fees, and other non-labor delivery costs are modeled at 10% in the base case, leaving a 90% gross margin before payroll.
5
Facility overhead
$8K monthly
Rent, utilities, insurance, software, licensing, cleaning, and administration continue even when a school holiday or enrollment dip reduces tuition collections.
6
Retention and cash timing
39-week core season
Keeping families through the school year protects tuition already won and reduces the marketing spend and vacancy weeks needed to replace churned seats.
Want to test enrollment, staffing, and owner pay in a full forecast?
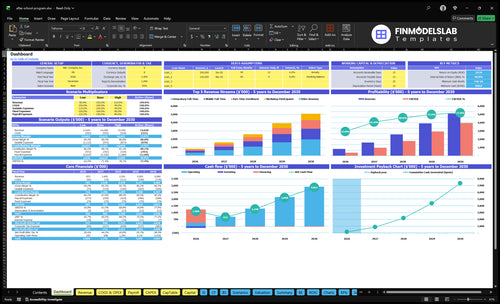
The After School Program Five-Year Financial Model Template includes a dashboard and scenario views that can help pressure-test enrollment, pricing, payroll, cash runway, and break-even assumptions. The screenshot is useful for checking whether a stronger enrollment case also brings the staff, working-capital, and reserve burden needed to support it.
What enrollment and tuition level supports a $66K owner income?
The base case needs about $336,000 of annual revenue, nearly the calculator’s $335,424 requirement for a $5,500 monthly owner-pay target. The 2025 America After 3PM findings report that parents of 29.6 million children want afterschool programs while only 7 million are enrolled. That shows unmet need, not proof that one neighborhood can fill 60 paid seats.
The 2024 Delaware market-rate survey found 75th-percentile center prices of $30 to $33.95 per day for school-age care under four hours. The model’s $150 weekly tuition is near the low end of that five-day equivalent. Lower-cost markets should lower both price and costs; expensive metros should not pair premium tuition with cheap-market wages or rent.
Revenue math that can support the base case
About 54 average enrolled children in a 60-slot program.
$150 per child per school week for 39 core weeks.
Core tuition of about $315,900 for the year.
About $20,100 from registration, school-closure care, or limited enrichment.
Annual revenue rounds to $336,000, or $28,000 as a 12-month average.
What this estimate hides
Billing can be concentrated in school months even though rent and debt are year-round.
A waitlist does not guarantee families will accept your schedule, location, transport, or tuition.
Discounts for siblings or prepaid terms reduce realized revenue per occupied seat.
Two weeks of vacancy on ten seats at $150 per week removes $3,000 before any staffing savings.
How much staff can the program afford before owner pay gets squeezed?
In the base case, average non-owner payroll is capped near $6,500 per month on a 12-month equivalent basis. The latest national BLS wage table for May 2025 lists childcare workers at a median $16.82 per hour, so the model uses roughly $18 per hour for frontline school-age staff before payroll burden and backup coverage. That is a planning rate, not a local wage quote; high-cost metros can be materially higher.
Ratios create cost steps. Licensing and staffing rules are local, so the model uses Delaware only as a transparent benchmark. Delaware’s 2024 child care cost model lists a 1:15 school-age ratio and a 30-child group size. This model uses 1:15 for planning, not as a nationwide rule.
Why 54 children can still need four staff
At a 1:15 benchmark, 46 to 60 children require four staff in ratio.
Four staff at 25 hours per week and $18 per hour is about $70,200 of school-year wages.
Payroll burden, substitutes, training, and schedule overlap can lift that toward the modeled $78,000 annual payroll.
The owner-director is not included in that payroll line.
When a hired director changes the answer
The base case assumes the owner performs director and administrative duties.
Hiring a full-time director without raising enrollment or price can absorb most of the $66,360 owner-income pool.
Director pay should be treated as real labor, not hidden in owner distributions.
A manager-run location therefore needs more seats, higher tuition, or a lower owner-income target.
Key Takeaways
The base model produces $66,360 of annual owner income after modeled reserves on $336,000 of revenue.
Operating break-even is about $230,700 of annual revenue before owner pay and reserves; supporting the $66,000 target needs about $335,400.
Owner-directed economics are materially better than manager-run economics because the director role is not duplicated in payroll.
Safe distributions come only after direct costs, staff, fixed overhead, marketing, debt service, taxes, and a reinvestment buffer are funded.
What do low, base, and high owner-income scenarios look like?
The modeled range is $15,720 to $109,212 a year after tax and reinvestment reserves. These are reconciled planning cases, not salary benchmarks. Enrollment, price, payroll, overhead, marketing, debt, and reserves all change together, so the low and high cases are stress tests rather than promises.
Owner income scenarios
Compare how occupied seats, tuition, staffing, overhead, debt, and reserve policy change owner cash.
Low, base, and high cases for an owner-directed after-school program.
Scenario
Low CaseLean enrollment
Base Case60-slot owner-directed
High CaseAdded capacity
Launch modelOperating posture
Slower enrollment path with a leaner three-staff schedule and tight owner cash.
Owner-directed 60-slot program at about 90% average occupancy.
Expanded capacity with stronger pricing, five-staff coverage, and higher overhead.
Owner income rangeAfter modeled tax and reinvestment reserves
$15,720
Annual owner income
$66,360
Annual owner income
$109,212
Annual owner income
Best fitHow to use the case
Use to test survival when seats fill slowly and fixed costs cannot shrink much.
Use for budgeting a stable owner-directed center before adding management payroll.
Use to test whether added licensed capacity still produces owner cash after the extra team and room cost.
!
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
How should owner salary, distributions, debt, and reserves be handled?
Do not call the whole $66,360 base output a distribution. It is the owner-income pool after operating costs, debt service, and modeled reserves. Because the owner does the director’s job, part pays for labor and part may be return on ownership. BLS reports a May 2024 median wage of $56,270 for preschool and childcare center directors, a useful labor-value reference for this owner-directed model.
Entity structure changes how that pool is paid. The IRS says an S corporation must pay shareholder-employees reasonable compensation for services rendered before additional cash is treated as distributions. Other entities work differently, so the calculator’s 22% tax reserve is only a planning holdback, not a personal tax calculation.
Debt is cash, not an accounting footnote. The base case deducts $2,000 a month before owner income. SBA says 7(a) rates are negotiated but capped relative to a base rate; its current 7(a) terms show the range by loan size. No debt frees part of that $24,000 annual burden; heavier financing reduces owner cash.
Separate four different numbers
Revenue: what families and other payers are billed or collected.
Operating profit: gross profit minus labor, overhead, marketing, and debt cash service in this planning model.
Owner salary or labor compensation: pay for the director and operating work the owner actually performs.
Owner distribution: residual cash paid because of ownership, only after liquidity and tax rules allow it.
What must be funded before cash is safe
Next payroll and payroll taxes.
Rent, insurance, software, utilities, licensing, and near-term vendor bills.
Debt principal and interest due under the financing agreement.
Tax set-asides based on the actual entity and owner situation.
Replacement, compliance, and enrollment-volatility reserves.
What are the six biggest After-School Program income drivers?
These are the same six levers as the compact cards, expanded into decisions. After-school economics are capacity-and-labor driven: revenue arrives one occupied seat at a time while staffing and facility costs move in steps. Compliance is also a real cost driver: Delaware’s 2024 child care cost model explicitly includes health, safety, licensing, staffing, ratios, and group size in the cost of care. Cutting supervision or compliance is therefore not a valid margin strategy.
1. Occupied seats and utilization
Fill the room before you add the room
The base case averages 54 enrolled children against 60 slots, or about 90% utilization. At $150 per week for 39 school weeks, one retained seat produces $5,850 of core tuition; ten empty seats mean about $58,500 of missed revenue before add-ons.
At a 90% gross margin, one seat creates about $5,265 of gross profit before payroll and overhead. If a lower child count does not eliminate a staffing step, most of that loss reaches owner cash. Track utilization by staffing band, not only as one percentage.
The 2025 America After 3PM survey shows very large unmet national demand, but the founder still needs a school-by-school catchment plan. Transportation boundaries, pickup time, school calendars, and parent commute patterns can make a seemingly strong ZIP code unusable.
Track seats by staffing threshold
Watch paid enrollment and near-term starts against the next staff requirement. The useful question is not only “How full are we?” but “How many more paid seats can this existing team serve legally and safely?”
Paid seats versus licensed seats.
Seats by pickup school and grade band.
Vacancy weeks per seat.
Waitlist-to-enrollment conversion.
Revenue per staffed group.
2. Weekly tuition and realized revenue per child
Price the schedule families actually buy
The model uses $150 per week. Delaware’s 2024 market-rate survey found 75th-percentile center pricing of $30 to $33.95 per day for under four hours of school-age care; five days at $30 equals $150. Treat that as benchmark geography, not a national rate.
Raising realized price by $5 per week across 54 children and 39 weeks adds about $10,530 of annual revenue. At 90% gross margin, that is roughly $9,477 more gross profit and about $6,634 of theoretical owner-income lift after the base 30% reserve, if enrollment and costs hold.
Realized price is more useful than the posted rate. Sibling discounts, staff discounts, partial weeks, late starts, scholarships, and unpaid balances can reduce what is collected per occupied seat. Track the actual dollars collected per child-week and compare them with the posted price.
Watch realized tuition, not the brochure price
A higher posted rate does not help the owner if it increases vacancy or gets discounted away. Measure the amount that reaches the bank for each paid child-week.
Collected revenue per child-week.
Discount rate by reason.
Late-payment and bad-debt rate.
Price increase retention.
Registration and add-on revenue per child.
3. Staffing ratio and shift design
Build schedules around ratio steps, not averages
BLS May 2025 wage data puts the childcare-worker median at $16.82 per hour; the base plan uses about $18 before burden. Four staff at roughly 25 school-week hours each cost about $70,200 over 39 weeks, rising toward the $78,000 annual payroll assumption after burden, substitutes, training, and overlap.
At the 1:15 benchmark, 45 children can fit within three staffing units, while the 46th may trigger a fourth. An extra person at $18 for 20 hours a week across 39 weeks costs about $14,040 before burden, so one new enrollment cannot fund the staffing step.
The owner-director assumption is central. If the owner stops covering administration, parent communication, staffing gaps, and site leadership, the model must add a director or manager wage to labor before calling the remaining cash a distribution.
Track paid labor per child-hour
Measure labor against the hours children are actually in care. A ratio-compliant program can still overstaff through early clock-ins, late close coverage, fragmented school pickups, or too many small groups.
Paid staff hours per child-hour.
Overtime and substitute hours.
Children per staff by time block.
Owner coverage hours.
Cost of the next staffing step.
4. Direct program cost and gross margin
Keep service quality high without hiding COGS
A 90% base gross margin means non-labor direct costs consume 10% of revenue, or $33,600 on $336,000 of sales. That covers snacks, materials, merchant fees, consumables, and activity costs. Delaware’s 2024 cost model likewise treats materials and program inputs as real cost drivers; payroll stays separate in this calculator.
If direct cost rises from 10% to 13%, gross profit falls $10,080 annually. With the base 30% combined reserve, roughly $7,056 of owner cash disappears if other costs are unchanged.
The goal is not to cut program quality. Decide which costs belong in tuition, which should be charged separately, and which vendors can be standardized. Premium enrichment can add revenue while also adding instructor, admission, or transport expense.
Reconcile gross margin every month
Keep a direct-cost schedule separate from payroll and fixed overhead. Otherwise a rising snack, payment, or activity bill can disappear inside “miscellaneous” until the owner draw is already under pressure.
Direct cost per child-week.
Merchant fees as a percent of collections.
Snack and supply cost per enrolled child.
Enrichment revenue versus enrichment cost.
Gross margin before labor.
5. Facility, transport, and fixed overhead
Match the lease and transport footprint to paid seats
The base model carries $8,000 a month of fixed overhead, or $96,000 annually, for rent, utilities, insurance, software, licensing, cleaning, and administration. It is a mid-cost planning assumption and should be replaced with local quotes.
Before owner pay or reserves, base operating break-even is about $19,222 of monthly revenue: $17,300 of operating costs divided by a 90% gross margin. Supporting the $5,500 monthly owner target after reserves lifts required revenue to $27,952. If those fixed costs are financed, SBA 7(a) terms show why the debt payment must be modeled explicitly rather than buried in overhead.
Transportation can move costs between direct and fixed categories. A dedicated van adds insurance, maintenance, fuel, and financing even when route density is weak. A school-site program without transport can support a lower revenue hurdle.
Track overhead per occupied seat
Rent and vehicle commitments should be evaluated against paid capacity, not maximum theoretical capacity. Expansion is attractive only when the added seats cover the new room, staffing step, and any financing burden.
Fixed overhead per occupied seat.
Rent as a percent of collected revenue.
Transport cost per routed child.
Debt service per month.
Break-even revenue before owner pay.
6. Retention, marketing, and cash timing
Protect the 39-week revenue stream you already sold
After-school cash follows the school calendar while rent, insurance, debt, and administration continue year-round. The model therefore uses a 12-month revenue equivalent rather than pretending every month collects exactly $28,000.
If one $150 weekly seat is empty for four weeks, revenue falls $600. Ten such vacancies cost $6,000 before replacement marketing. The 2025 America After 3PM survey also identifies cost, transportation, and location as major barriers, which is why retention and route fit matter alongside marketing. With an $800 monthly marketing budget, a sudden enrollment hole can require more spend or a temporary owner-income cut.
Reserve policy is the final buffer. The base model holds 22% of positive profit for taxes and 8% for reinvestment. Those percentages are planning tools, not tax advice. They exist because accounting profit is not automatically safe cash: payroll, refunds, annual insurance, repairs, deposits, school-calendar gaps, and debt all have timing that can differ from the income statement.
Track cash by school-calendar month
Build a rolling cash view that separates earned revenue from collected cash and shows the weeks when fixed expenses continue but tuition pauses or families leave.
Monthly retention and withdrawal reasons.
Vacancy weeks before replacement.
Marketing cost per enrolled family.
Cash collected versus billed.
Weeks of payroll and fixed overhead held in reserve.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.