What Is a Realistic Pay Range for Amusement Park Owners?
For a U.S. regional, single-site amusement park rather than a destination resort, a controlling owner can reasonably model about $1.75M a year of owner income in a stabilized base case, with a stress-tested range from about $279K to $3.13M. The base case uses $15.48M of annual revenue, about 250,000 visits at roughly $62 of revenue per visit, an 88% gross margin before payroll, $5.4M of hired labor, $3.0M of fixed overhead, $540K of marketing, and $1.5M of annual debt service. The $1.75M figure is cash-style owner income after a 25% tax reserve and 20% reinvestment reserve; it is not GAAP net income, EBITDA, a guaranteed salary, or a guaranteed distribution. It also excludes any owner-level tax true-up, partner or investor splits, and major one-time ride replacements beyond the modeled reserve. This article models the same fixed-site park scope used by the U.S. Census amusement and theme park definition, which includes parks operating a mix of rides, games, shows, refreshment stands, and related attractions.
Owner income$1.75MNet margin11%Revenue for target pay$13.7MBusiness difficultyHard
What does a realistic amusement park owner-income model look like?
The base case is built around a regional park with roughly 250,000 annual visits, not a Disney- or Universal-scale resort. A useful outside anchor is Six Flags' 2025 reporting: the company disclosed $61.90 of in-park revenue per visit, split between admissions and in-park products, while its cost bridge separately identified cost of goods, revenue-driven fees, labor, and other operating expenses in its 2025 Form 10-K. Because that operator has scale, brand power, and a portfolio of parks, this article uses those figures as an adjacent proxy rather than treating them as a small-park guarantee. The calculator's 88% base gross margin is also reconstructed to exclude payroll: direct goods and revenue-driven costs are modeled before labor, while every hired wage remains in the labor field.
The model is owner-operated at the executive level. The owner is assumed to work on strategy, finance, vendor decisions, and management oversight, but the calculator does not bury an owner salary inside payroll. Hired ride operators, maintenance staff, guest services, food teams, supervisors, security, and other employees sit in labor cost. The residual output is the owner's economic compensation pool. Depending on entity type and tax advice, the real-world owner may later divide that pool between salary and distributions; this calculator deliberately does not prescribe that split or count the same owner compensation twice.
Owner income calculator
Estimate owner take-home and target-pay revenue from park sales, margin, payroll, overhead, financing, and reserves.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
1
Attendance and sellable days
250K visits
Every additional guest can produce admission and in-park sales while much of the park's fixed cost base is already committed.
2
Revenue per guest
About $62
Ticket yield, passes, food, merchandise, parking, games, and premium access determine how much revenue each visit carries.
3
Labor efficiency
35% of sales
The base case spends about $5.4M a year on hired labor, so schedule quality and throughput have a direct effect on distributions.
4
Ride uptime and safety
20% reserve
Routine maintenance sits in overhead, while a separate share of positive profit stays in the business for larger repairs and liquidity.
5
Marketing and pass mix
3.5% of sales
Paid demand generation must create profitable visits, not just discounted attendance that lowers admission yield.
6
Debt and reinvestment
$1.5M a year
Base debt service absorbs cash before owner distributions, and major attraction spending can require even more cash than this model retains.
Want to test these assumptions in a full amusement park forecast?
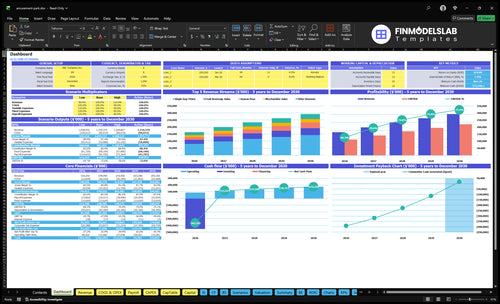
The Amusement Park Excel Financial Model for Startups includes a dashboard for revenue, costs, cash flow, and operating KPIs. The preview is useful for stress-testing the same owner-income inputs used here: visitor count, ticket and ancillary revenue, payroll, operating costs, capex, financing, and cash reserves. Treat the screenshot as a planning interface, not evidence for the benchmarks in this article.
How many visitors does a regional amusement park need to support owner pay?
In the base case, about 250,000 visits at roughly $62 of revenue per visit produce $15.48M of annual sales and about $1.75M of owner income after modeled reserves. The $62 anchor is intentionally close to Six Flags' reported 2025 per-capita spending of $61.90 in its full-year 2025 results. A smaller regional park will not have the same product mix, pass behavior, or pricing power, so the real planning job is to prove both attendance and per-guest yield in the local market.
At the base cost structure, cash break-even after the modeled $1.5M annual debt service but before owner pay and reserves is about $11.86M of annual revenue: $870K of monthly labor, overhead, marketing, and debt divided by the 88% gross margin, then annualized. Excluding debt service, the operating break-even before financing is closer to $10.16M. To support the calculator's $900K annual target owner pay after the 25% tax reserve and 20% reinvestment reserve, required revenue rises to about $13.72M. That gap is why "profitable park" and "park that safely funds the owner's target draw" are different tests.
Volume math to watch
Low: $9.24M annual revenue with little room above fixed cash costs.
Base: $15.48M from about 250K visits at roughly $62 each.
High: $23.76M from about 360K visits at roughly $66 each.
Track visits per open day because weather and calendar mix can hide weak economics.
What this estimate hides
Pass holders and single-day guests produce different admission yield.
Peak-day rain hurts more because fixed costs still run.
Queues, food throughput, parking, and safety staffing cap profitable volume.
Pass prepayments improve cash timing but are not immediate earned revenue.
How do ticket yield and in-park spending change amusement park income?
Per-guest spending is the fastest way to improve owner income when the park can raise yield without damaging attendance. United Parks & Resorts reported $78.54 of total revenue per capita in 2025, including $41.73 of admission revenue and $36.81 of in-park spend, in its 2025 results. That is a larger, premium operator, so this article keeps the base case near $62 per visit instead of adopting the higher figure. The point is the mix: food, merchandise, games, parking, premium access, group business, and pass economics can add as much financial leverage as the posted gate price.
The gross-margin assumption also matters. Six Flags' 2025 cost bridge reported about $268.0M of food, merchandise, and games cost plus about $93.0M of other revenue-driven costs against $3.10B of revenue. That is roughly 11.6% of revenue in direct non-labor costs, leaving an 88.4% contribution before labor and the broader fixed operating base. The calculator rounds that adjacent public-company proxy to an 88% base gross margin. A local park with weaker purchasing, heavy food mix, third-party commissions, or high card fees should use a lower percentage.
Revenue levers
$3 more per guest on 250K visits adds $750K of annual revenue.
Food, parking, games, and premium-access attach rates can lift yield.
Passes trade lower yield per visit for repeat visits and add-on sales.
Groups can fill otherwise weak weekdays.
Margin guardrails
Ticket price is not the same as realized revenue per visit.
Keep non-labor COGS separate from payroll.
Judge promotions on contribution dollars, not attendance alone.
Track processing, concession, refund, and transaction costs.
Can an amusement park run without the owner working every day?
It can, but absentee ownership is more expensive and operationally riskier than the same revenue model with an engaged executive owner. The 2025 national mean wage was $15.69 an hour for amusement and recreation attendants and $25.75 an hour for first-line entertainment and recreation supervisors, according to BLS wage data. A park also needs maintenance, food, security, finance, human resources, and senior management coverage. If the owner steps away from the executive role, a market-rate general manager and stronger management bench must be added to payroll before owner distributions are calculated.
The base labor input is $450K a month, or $5.4M a year, which is about 35% of base revenue. That ratio is close to Six Flags' 2025 labor cost of roughly 33.6% of revenue, but the smaller park has less scale and therefore uses a slightly higher share. U.S. Census business-pattern data also shows how wide the sector is: the industry had 742 employer establishments in 2023, with many small establishments and a much smaller group employing hundreds or thousands of people in the 2023 County Business Patterns data. There is no single staffing template that fits every park.
Working-owner model
Owner leads finance, vendors, KPIs, and senior management.
Owner pay is excluded from the $5.4M hired-labor line.
Ride, maintenance, food, security, and safety specialists remain paid staff.
Daily attendance, labor, uptime, and cash are the owner's core dashboard.
Absentee-owner adjustment
Add a qualified general manager and added administrative coverage to labor.
Reduce distributions unless higher revenue funds that payroll.
Separate return on capital from pay for management work.
Require daily reports on safety, downtime, service, and cash.
What has to be paid before amusement park cash is safe to distribute?
Owner distributions come last. The park first pays direct goods and processing costs, hired labor, maintenance, utilities, insurance, property costs, inspections, marketing, administration, and debt service. Then it needs tax and reinvestment reserves. The IRS notes that owners with income not covered by withholding may need estimated tax payments, so the model's 25% holdback is a cash-planning buffer rather than a tax-rate claim; actual obligations should be set from the owner's facts using IRS estimated-tax guidance. The 20% reinvestment reserve is likewise a planning rule, not a promise that it will fully fund a new coaster.
Safety and compliance also put a floor under cash needs. IAAPA's U.S. ride-safety overview says 44 of 50 states regulate amusement parks, while its regulatory guidance emphasizes recognized amusement-ride standards and periodic inspection by qualified inspectors; see IAAPA ride-safety regulation guidance. Those obligations are not optional margin levers. Cutting maintenance, inspection, training, or insurance to manufacture a larger owner draw may create downtime, claims, regulatory trouble, and lost attendance that cost far more than the short-term saving.
The base model helps separate financial labels. Annual revenue is $15.48M. Gross profit after modeled non-labor direct costs is $13.62M. A cash operating-profit proxy before financing is about $4.68M after hired labor, fixed overhead, and marketing. After $1.5M of debt service, profit before modeled reserves is about $3.18M. The tax and reinvestment reserves retain about $1.43M, leaving about $1.75M as owner income. Accounting profit can be lower because depreciation on rides and buildings is an expense even though it is not a current cash payment; conversely, principal repayment uses cash but is not an accounting expense. EBITDA, accounting profit, owner salary, distributions, and bank cash are therefore not interchangeable.
Key Takeaways
The base owner-income estimate is about $1.75M after modeled tax and reinvestment reserves on $15.48M of annual revenue.
Cash break-even after modeled debt is about $11.86M of annual revenue; supporting a $900K annual owner-pay target after reserves requires about $13.72M.
Attendance and per-guest spending create the revenue ceiling, but payroll, fixed overhead, safety, and debt determine how much of that revenue reaches the owner.
Large attraction capex, equity-partner splits, and owner-level tax true-ups can reduce actual distributions below the calculator output even when the park is profitable.
How do low, base, and high amusement park owner-income cases compare?
The three scenarios move revenue and costs together. The low case does not pretend fixed overhead disappears when demand softens, and the high case adds payroll, marketing, overhead, debt, and a larger reinvestment reserve as the park serves more guests. Exact owner-income values below match the calculator formula after the modeled tax and reinvestment reserves. They are cash-planning outputs, not salary promises or accounting net income.
Owner income scenarios
Low, base, and high cases tie attendance, per-guest revenue, staffing, overhead, debt, and reserves to owner cash.
Low, base, and high owner income cases for a regional U.S. amusement park.
Scenario
Low CaseConservative
Base CaseModeled
High CaseUpside
Launch modelDemand and cash posture
Soft demand and limited pricing power keep owner cash close to the fixed-cost floor.
Stabilized regional demand supports a normal operating year with room for reserves and owner pay.
Stronger attendance and spend support more staffing and reinvestment while still widening owner cash.
Typical setupRevenue and operating scale
$9.24M annual revenue; about 160K visits at roughly $58 per visit; 86% gross margin.
$15.48M annual revenue; about 250K visits at roughly $62 per visit; 88% gross margin.
$23.76M annual revenue; about 360K visits at roughly $66 per visit; 89% gross margin.
Cost driversWhat absorbs the revenue
$3.36M labor
$2.52M fixed overhead
$360K marketing
$1.20M debt service
$5.40M labor
$3.00M fixed overhead
$540K marketing
$1.50M debt service
$8.40M labor
$3.96M fixed overhead
$960K marketing
$1.92M debt service
Owner income rangeAfter modeled tax + reinvestment reserves
$278,520
$1,750,320
$3,130,392
Best fitWhen to use the case
Stress-test a weak season, slower ramp, or local demand shortfall.
Primary planning case for a stabilized owner-operated regional park.
Upside case for proven demand, stronger guest yield, and enough staffing and capital to protect service and uptime.
!
Planning note: Scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
What are the six amusement park income drivers that matter most?
The owner-income range is wide because an amusement park has a high fixed-cost base and several revenue levers that compound each other. The six drivers below use the same assumptions as the calculator and scenarios, so the quick math connects directly to the $279K, $1.75M, and $3.13M owner-income cases rather than introducing a second model.
1. Attendance volume and sellable operating days
Build the forecast from visits, not wishful annual sales
Attendance is the first driver because admission, food, merchandise, games, parking, and premium products all depend on a guest showing up. Six Flags says attendance responds to rides, guest satisfaction, weather, pricing, advertising, perceived safety, and the economy, while many costs stay relatively fixed during a season in its 2025 filing.
Base math is 250K visits at about $62 each. A 10% attendance drop cuts roughly $1.55M of revenue, but insurance, utilities, inspections, core maintenance, property costs, and debt do not fall 10%. Owner income therefore moves faster than attendance when demand weakens.
Track profitable visits by day type
Annual attendance is too coarse; separate peak demand from discount-driven traffic.
Visits per open day
Weather-adjusted attendance
Contribution per operating day
Queue and ride throughput
When peak capacity is full, improve yield before chasing more volume.
2. Revenue per guest and ancillary mix
Raise realized yield without breaking attendance
The base model uses about $62 per guest, combining realized admission yield with food, merchandise, games, parking, and premium products. Six Flags' 2025 cost bridge supports the article's 88% base gross-margin proxy before labor because direct goods and revenue-driven fees were much smaller than payroll and broader operating costs.
A $3 gain in spend across 250K visits adds $750K of sales and about $660K of gross profit at an 88% margin before added labor or overhead. The gain only helps if higher prices or promotions do not materially reduce attendance.
Measure yield by guest and product
One blended average can hide heavy discounting.
Admission revenue per visit
Food and beverage spend
Games, parking, and premium add-ons
Pass visit frequency and renewal
Favor attach-rate gains that preserve repeat demand.
3. Labor efficiency and management depth
Schedule labor to throughput, not only headcount
Base labor is $5.4M a year, about 35% of revenue. That sits near Six Flags' 2025 labor share, while BLS May 2025 wage data shows mean pay of $15.69 an hour for amusement and recreation attendants and $25.75 for first-line entertainment and recreation supervisors.
A 2% increase in base payroll costs $108K annually. With no revenue change, that reduces owner income by roughly $59K after the base reserves. The goal is not understaffing; it is matching paid hours to ride blocks, meal peaks, crowd flow, and safety coverage.
Track output per paid hour
Labor control should protect capacity and guest service.
Labor as a percent of revenue
Sales per labor hour
Overtime and replacement hours
Ride and food throughput
Add full management payroll before modeling absentee-owner distributions.
4. Ride uptime, maintenance, safety, and insurance
Treat uptime spending as revenue protection
Maintenance and safety are not discretionary. IAAPA says fixed-site facilities use daily, weekly, monthly, and yearly inspections and describes roughly 400 North American fixed-site facilities serving hundreds of millions of guests; see the IAAPA safety overview. Funding trained maintenance, inspection, and insurance comes before distributions.
Routine upkeep is inside the base $3.0M fixed-overhead budget. The 20% reinvestment reserve retains another $636,480 annually, but a major coaster or land project still needs a separate capital plan.
Track uptime and reserve adequacy
Know whether maintenance cash is preventing failures.
Ride availability
Preventive work completion
Downtime by attraction
Claims and insurance renewals
Deferred repairs can turn short-term cash into future downtime and larger bills.
5. Marketing efficiency, pass mix, and repeat demand
Buy contribution, not vanity attendance
Base marketing is $540K a year, about 3.5% of revenue. Six Flags notes that pricing and advertising influence attendance and that lower 2025 revenue was partly offset by lower labor and advertising expense in its operating discussion. Demand spend must therefore be judged on profit, not raw visits.
If a $100K campaign creates 4,000 incremental visits at $62 each, it produces about $248K of revenue and $218K of gross profit at an 88% margin before incremental labor. After the campaign itself, only $118K remains before those extra operating costs.
Track acquisition by contribution
Measure the cash created by each campaign cohort.
Cost per first visit
Gross profit by campaign
Pass renewal and frequency
Group-booking weekday fill
Repeat guests with strong in-park spend usually beat expensive one-time traffic.
6. Debt load, seasonal liquidity, and reinvestment
Calculate owner cash after financing and capital needs
Debt and capex explain why EBITDA can look healthy while distributions stay constrained. Base debt service is a reasoned $1.5M annual assumption. United Parks & Resorts reported $217.5M of 2025 capital expenditures in its 2025 financial results; a regional owner should not copy the dollars, but the capital intensity is relevant.
Seasonality adds pressure. Public operators can borrow before opening season and pay facilities down with peak cash flow. A real regional park therefore needs a weekly cash forecast even if the annual model shows $1.75M of owner income.
Track cash after debt and capex
Distributions should follow liquidity, not a strong weekend bank balance.
Debt-service coverage
Minimum seasonal cash
Committed maintenance capex
Tax and distribution timing
Keep enough cash to fund the next low season without borrowing the distribution back.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Amusement Park Bundle
Choosing a selection results in a full page refresh.