Can the Owner of a Boxing Gym Build a Sustainable Income?
Boxing Gym Bundle
For an owner-operated U.S. boutique boxing fitness gym, a realistic base planning range is about $80,000-$85,000 a year of owner income after modeled tax and reinvestment reserves, with the calculator landing at $82,740 on $540,000 of annual revenue. This model assumes roughly 250 active members at about $135 in realized monthly dues, plus private training, class packs, clinics, and retail; a 93% gross margin before payroll; $15,500 a month of hired labor; $11,500 of fixed overhead; $2,500 of marketing; and $2,500 of debt service. The figure is not a passive-owner return: the owner is working as general manager and sales lead, and it excludes a separate market-rate owner salary, final personal tax liability, and any guaranteed distribution.
Owner income$83KNet margin15%Revenue for target pay$542KBusiness difficultyHard
What could a boxing gym owner take home each month?
In the base case, the gym produces $6,895 a month of owner income after a 20% tax reserve and 10% reinvestment reserve, or $82,740 a year. That starts with $45,000 of monthly revenue and leaves $9,850 before reserves after direct costs, hired payroll, fixed overhead, marketing, and debt service. The broader fitness industry is profitable but not uniformly so: the Health & Fitness Association's 2025 benchmarking report, reporting 2024 operator performance, showed a median EBITDA margin of 23.6% and 66.4% member retention. The calculator is a planning model, not an earnings promise.
Owner income calculator
Test how boxing-gym revenue, margin, staffing, overhead, financing, and reserves change the owner's residual cash.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
What moves boxing gym owner income the most?
The six strongest levers are retained members, revenue per member, class utilization, hired payroll, facility overhead, and debt plus reserves. Pricing matters because boxing is usually sold as a premium guided workout rather than basic gym access: live TITLE Boxing Club location pages show unlimited or limited-class memberships ranging from about $99 to $159 per month in a live example such as Plano pricing. Those are franchise examples, so the model uses a $135 realized monthly dues assumption and keeps local pricing editable.
1
Active members and retention
250 members
The base case needs about 250 active members; retaining more of them reduces the number of paid replacements marketing must buy every month.
2
Revenue per member
$135 dues
A $10 increase in realized monthly dues across 250 members adds $2,500 of revenue before any change in training or retail mix.
3
Class utilization
65%-75%
The base schedule should fill roughly two-thirds to three-quarters of usable bag spots at peak times before adding more coach hours.
4
Coach and desk payroll
$15.5K/mo
Hired labor is the largest modeled cash cost; extra shifts should follow demand, while the owner's GM and sales work is not hidden inside payroll.
5
Facility overhead
$11.5K/mo
Rent, utilities, insurance, software, cleaning, and repairs keep running even when a class has six people instead of twenty-six.
6
Debt and reserves
$5.5K/mo
Base debt service is $2,500 and the base reserve is $2,955, so more than $5,000 of monthly cash is unavailable for owner distribution.
Want to test the assumptions in a full boxing gym forecast?
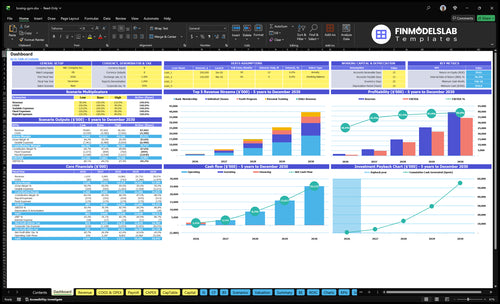
The Boxing Gym Financial Model Template for Excel and Google Sheets includes a dashboard that can help you stress-test membership growth, class and training revenue, payroll, operating expenses, capital spending, and cash runway. Use the screenshot to connect owner-income assumptions with the P&L and cash-flow forecast.
How many members does a boxing gym need to support an $84K target pay?
In this owner-operated model, about 250 active members plus $11,250 a month of private training, class packs, clinics, and retail support $45,000 of monthly revenue. The membership side is plausible for a premium boxing studio because current location pricing can sit well above the whole-industry average: the HFA reported $65 average U.S. monthly dues in 2023, while a live TITLE Boxing Club Boston location lists $109 to $159 monthly plans. The model does not assume every market can charge Boston prices; it assumes a blended $135 collected dues rate and asks the local market to prove it.
Base revenue build
250 active members × $135 realized dues = $33,750 per month.
Private training planning assumption = about $6,000 per month.
Class packs, clinics, retail, and fees = about $5,250 per month.
Total monthly revenue = $45,000, or $540,000 annualized.
What the member count hides
HFA's 66.4% 2024 retention benchmark implies roughly one-third of members may need replacing over a year if a club performs near that median.
At 250 members, 33.6% attrition is about 84 memberships a year, or seven replacements a month just to stay flat.
Peak-time bag capacity matters more than total memberships; a club can sell 250 memberships only if booking patterns fit the schedule.
Track paid joins, cancels, freezes, and reactivations separately instead of relying on a single headline member count.
What margin does a boxing gym need before the owner can draw cash?
The base gym needs a high 93% gross margin before payroll because most membership revenue has little non-labor variable cost, but that is not the same as a 93% profit margin. After $15,500 of hired payroll, $11,500 of fixed overhead, $2,500 of marketing, and $2,500 of debt service, only $9,850 remains before reserves, a 21.9% cash margin on sales. Before debt service, the $12,350 monthly operating surplus is a 27.4% EBITDA-like planning proxy, near the HFA's 23.6% median EBITDA margin for 2024 reporting operators. Revenue is collected sales; gross profit is revenue after direct non-labor costs; EBITDA excludes interest, taxes, depreciation, and amortization; accounting profit follows the P&L; owner salary pays for work; distributions come from residual equity cash after obligations.
Subtract $32,000 of hired labor, overhead, marketing, and debt service.
$9,850 remains before reserves; 20% tax plus 10% reinvestment reserves hold back $2,955.
$6,895 is left as modeled monthly owner income.
Break-even versus target pay
Operating break-even before reserves is about $34,409 monthly revenue: $32,000 of operating costs ÷ 93% gross margin.
Supporting a $7,000 owner target after the 30% combined reserve requires $45,161 a month under the fixed calculator formula.
The $10,752 gap between simple break-even and target-pay revenue is the cash needed to fund owner income and reserves.
Do not call gross margin, EBITDA, accounting profit, and distributable cash the same number.
Can a boxing gym run without the owner?
Yes, but the base $82,740 owner-income figure is not a passive-owner return. The base case assumes the owner manages sales, member retention, scheduling, vendor decisions, and some floor coverage while hired coaches and desk staff are in the $15,500 monthly labor line. The labor assumption is anchored by national pay data: BLS reported a $46,180 median annual wage for fitness trainers and instructors in May 2024, and May 2025 national data put the mean hourly wage for exercise trainers and group fitness instructors at $25.20. A truly absentee owner needs to add a manager cost rather than pretending those duties disappear.
Owner-operated economics
The owner covers GM and sales-lead work and receives the residual $6,895 monthly owner income in the base case.
That residual compensates both labor and ownership risk; it should not be presented as a passive distribution.
If the owner also teaches classes, track those hours so the business can see what replacement payroll would cost.
Use a shadow wage for the owner's role when comparing the gym with another investment.
Manager-run economics
A planning allowance of $6,000 to $9,000 a month for a capable club manager plus burden can consume most or all of the base owner residual.
Local manager pay should be researched rather than assumed; the $6,000 to $9,000 monthly allowance here is a planning range, not a wage benchmark.
To stay profitable with management added, raise member count, realized price, personal-training mix, or schedule efficiency.
Passive ownership becomes credible only after the location can pay market labor for all roles and still retain cash.
How much do debt service, taxes, and reserves reduce the owner's draw?
In the base case, $2,500 of monthly debt service is paid before owner income, then another $2,955 is held back as tax and reinvestment reserves. That means a gym showing a $12,350 operating surplus before debt could still distribute only $6,895 safely under these assumptions. The legal form matters too: the IRS says an S corporation must pay reasonable compensation to a shareholder-employee for services before non-wage distributions. The calculator therefore models owner take-home as a residual planning output, not a tax classification or instruction to replace wages with distributions.
Cash that gets paid first
Card fees, retail cost, and consumables reduce revenue to gross profit.
Coach and desk payroll, rent, utilities, insurance, software, cleaning, and marketing are operating cash needs.
Required loan principal and interest are real cash uses even when principal is not an accounting expense.
Tax and reinvestment reserves protect against treating all remaining profit as spendable cash.
Why the reserve matters
Heavy bags, flooring, HVAC, showers, sound systems, and front-desk systems eventually need repair or replacement.
A $540,000 owner-operated boxing gym can support about $82,740 of modeled annual owner income after the base tax and reinvestment reserves.
Break-even revenue is much lower than revenue needed for target owner pay; surviving is not the same as paying the owner well.
Member retention, realized dues, peak class utilization, and labor scheduling determine whether premium pricing turns into cash.
An absentee owner must add market-rate management payroll before calling the residual a passive distribution.
What do low, base, and high owner-income cases look like?
The low case does not assume fixed costs disappear when sales soften, and the high case adds labor, overhead, marketing, and debt service as volume rises. Across the presets, monthly revenue runs from $34,000 to $65,000, payroll from $12,000 to $21,000, and annual owner income after reserves from $41,400 to $150,444. They assume the owner remains active in management and are not salary promises.
Owner income scenarios
Three coherent presets linking member demand, pricing, staffing, overhead, financing, reserves, and owner cash.
Low, base, and high planning cases for an owner-operated U.S. boutique boxing gym.
Planning factor
Low CaseConservative
Base CasePlanning case
High CaseStretch
Launch modelDemand and revenue posture
$34,000 monthly revenue
Owner-operated schedule
Slower member ramp
$45,000 monthly revenue
About 250 active members
Memberships plus training and retail
$65,000 monthly revenue
Denser class schedule
Stronger training and ancillary mix
Typical setupOperating footprint
Lean 2,500-3,000 sq. ft. planning footprint
Fewer staffed blocks
92% gross margin
Roughly 3,000-3,500 sq. ft.
Owner as GM and sales lead
93% gross margin
Higher-capacity footprint and schedule
More coaches and desk coverage
94% gross margin
Cost driversMonthly cash structure
$12,000 labor
$10,500 fixed overhead
$1,800 marketing
$2,500 debt service
$15,500 labor
$11,500 fixed overhead
$2,500 marketing
$2,500 debt service
$21,000 labor
$13,000 fixed overhead
$4,200 marketing
$3,000 debt service
Owner income rangeAfter modeled tax + reinvestment reserves
$41,400
$82,740
$150,444
Best fitWhen the case is useful
Stress-test a slow ramp where minimum rent, debt, and staffing still have to be paid.
Plan an established owner-operated studio with stable local demand and disciplined scheduling.
Test stronger demand only when added staff, marketing, and overhead are budgeted to support the volume.
!
Planning note: Scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
Which six income drivers should a boxing gym owner track?
The detailed drivers expand the same six levers, ordered by how directly they change the owner-income bridge. Track metrics that reconcile to revenue and cash rather than vanity statistics.
1. Active members and retention
Replace fewer members before buying more leads
At 250 active members, retention is the first owner-income lever because recurring dues fund the class schedule. The HFA's 2025 U.S. consumer headline report shows continued membership growth, while its operator benchmark puts 2024 retention at 66.4%. At that rate, about 84 of 250 memberships turn over in a year, or seven replacement joins a month before any net growth. Improving retention from 66% to 75% means roughly 22 fewer replacements a year.
Owner income benefits twice: dues stay on the books and fewer acquisition dollars refill the same capacity. Diagnose cancellations through onboarding, schedule fit, coach consistency, freezes, and plan changes before simply spending more on ads.
Track the member waterfall weekly
Reconcile beginning members to ending members so retention and acquisition are visible in the same report.
Beginning active members
New paid joins and reactivations
Cancels, freezes, and failed payments
90-day and 12-month retention
If seven or eight joins a month merely replace churn, do not call them growth.
2. Realized revenue per member
Price the membership mix, not just the headline plan
Boxing studios sell limited classes, unlimited access, private training, and retail rather than one flat fee. TITLE's current membership structure includes unlimited, 8x/month, and 4x/month options. The base model therefore tracks realized dues: $135 a month across 250 members, or $33,750 before training and other sales.
A $10 increase in realized dues across 250 members adds $2,500 of monthly revenue. At 93% gross margin and unchanged fixed costs, $2,325 reaches profit before reserves; after the base 30% reserves, about $1,628 a month, or $19,500 a year, can reach owner income. Measure any price test against conversion and retention, not list price alone.
Watch realized price and mix
Use collected cash and active memberships to see whether discounts and plan downgrades are eroding the price book.
Dues revenue per active member
Share on unlimited versus limited plans
Private-training revenue per member
Discount and failed-payment leakage
A premium price only helps if the gym can retain the member at that price.
3. Class capacity and schedule utilization
Fill existing bag spots before adding class blocks
Group boxing has a physical capacity constraint: each participant needs working space and, in many formats, a heavy bag. TITLE lists 45-, 60-, and 75-minute classes on its official workout page. The model therefore treats sellable capacity as bags × class blocks × attendance and targets roughly 65% to 75% peak utilization before adding recurring coach hours.
A 36-bag studio running 28 classes has 1,008 weekly bag spots. At 65% utilization, about 655 are used; at 75%, about 756. Those 101 extra visits can support more memberships without changing rent. Adding a weak midday class does the opposite: coach payroll rises before dues do.
Manage capacity by daypart
Overall utilization can hide packed evenings and empty midday classes, so schedule decisions should be made by block.
Booked spots ÷ usable spots by class
Waitlist count and no-show rate
Revenue per coached class hour
Member complaints about schedule access
Add capacity where waitlists are persistent; trim blocks that stay structurally empty.
4. Coach and front-desk labor
Match paid hours to the revenue schedule
Hired labor is $15,500 a month in the base case, more than rent, marketing, or debt service. BLS's May 2025 national wage table reports a $25.20 mean hourly wage for exercise trainers and group fitness instructors. Boxing-specific pay can be higher or lower based on credentials, local wages, class pay, commissions, and private-training work.
A $2,000 monthly payroll overrun reduces profit before reserves by $2,000. With the base 30% reserve rate, owner income falls about $1,400 a month, or $16,800 a year. If the owner covers shifts, still track the replacement hours so free owner labor does not inflate the apparent margin.
Track labor by productive hour
Separate class delivery, private training, sales coverage, and admin time so scheduling decisions have an economic owner.
Payroll as a percent of revenue
Coach cost per attended class visit
Private-training revenue per paid trainer hour
Owner hours that would require replacement payroll
Do not add permanent coverage for a temporary January demand spike.
5. Facility and fixed overhead
Make the lease work at ordinary attendance, not peak optimism
Every extra $1,000 of monthly fixed overhead raises operating break-even by about $1,075 at a 93% gross margin. If fixed overhead rises from $11,500 to $14,500 with no added capacity, break-even revenue rises about $3,226 a month. The best site is the one ordinary demand can carry through slow months.
Underwrite the address before signing
Use the lease economics and local approvals as part of the owner-income model, not as a separate real-estate decision.
Base rent, CAM, taxes, and escalators
Usable training space and peak capacity
HVAC, showers, sound, and maintenance exposure
Zoning, signage, occupancy, and insurance requirements
Stress-test the site at low-case revenue before relying on the high case.
6. Debt service and cash reserves
Separate accounting profit from cash safe to distribute
The base model pays $2,500 a month of debt service, then reserves 20% of positive profit for taxes and 10% for reinvestment. From $9,850 before reserves, $2,955 is held back and $6,895 remains. Loan principal reduces cash without reducing EBITDA, while equipment and working-capital needs arrive irregularly.
Owner salary and distributions depend on entity structure. The IRS's guidance on paying yourself notes that compensation rules differ by structure and corporate officers are generally employees. First calculate cash after operations, debt, and reserves; then determine wage, draw, or distribution treatment with a tax adviser. The high case reaches $150,444 after reserves, not a guarantee that all accounting profit can leave the bank.
Use a distribution gate
Before taking cash out, confirm the gym can cover near-term obligations and preserve an agreed operating buffer.
Required debt payment and covenant headroom
Tax reserve balance versus estimated liability
Equipment and facility replacement reserve
Minimum cash balance after the proposed owner draw
Owner distributions should be the last step in the cash waterfall, not the first line in the budget.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.