How Much Does a Coding Bootcamp Owner Make? $150K Pay Plus EBITDA
Coding Bootcamp Bundle
A coding bootcamp owner can make $150,000 in planned CEO Program Director pay if they work in that defined role On these researched assumptions, the business also shows EBITDA of $2010M in Year 1 rising to $10282M in Year 5, before taxes, debt service, capex, and owner distribution policy The model assumes 60 to 90 seats, 90% to 94% occupancy, tuition from $2,000 to $6,200, and $13,300 in monthly fixed overhead Treat this as a planning range, not a salary promise
Owner income$150K baseNet margin57% to 79%Revenue for target pay$3.6MBusiness difficultyMedium
Want to test your owner pay?
Owner income calculator
Estimate owner take-home and the target-pay gap from revenue, margin, costs, reserves, and target pay.
!
Planning note: This is a researched planning estimate, not guaranteed salary, tax advice, or owner distribution advice. Actual owner income depends on enrollment, pricing, payroll, taxes, reserves, and capital spending.
Want the six drivers of owner income?
1
Cohort Fill
60-90 seats
Filling more of the 60-90 seats at 90%-94% occupancy pushes tuition revenue up without much extra fixed cost.
2
Net Tuition
$2K-$6.2K
Higher tuition in the $2K-$6.2K range lifts take-home fast because core costs do not rise one for one.
3
Billing Cadence
20-22 d/mo
More billable days per month spread one cohort over more paid time and smooth cash.
4
Teaching Cost
$340K-$760K
Instructor and mentor payroll can run from about $340K to $760K, so staffing discipline protects margin.
5
Acquisition Cost
4%-8%
Marketing spend at 4%-8% of revenue decides how much tuition is left after each enrollment is won.
6
Cash Floor
$893K
A $133K monthly overhead and a $893K cash floor set the burn ceiling, so reserves matter on the way to payback.
Want to see the full Coding Bootcamp model?
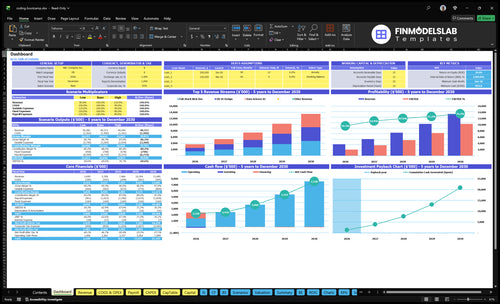
This Coding Bootcamp Financial Model Template shows the dashboard, assumptions, tuition revenue, capacity, staffing, marketing, COGS, opex, capex, cash flow, and owner income. It also includes scenario planning for seats, occupancy, CEO pay, minimum cash, and launch capex.
Owner-income model highlights
Owner take-home is scenario-based
Revenue ties to enrollment
Cash stays above minimum
Can a coding bootcamp owner pay themselves?
Yes, a Coding Bootcamp owner can pay themselves if they hold a real operating role, not as a passive draw; this model budgets a CEO/Program Director salary of $150,000 per year. Track it against cash and enrollment using What Is The Most Critical Metric To Measure The Success Of Your Coding Bootcamp?, because distributions should start only after payroll, career services, acquisition spend, fixed overhead, capex, and the $893,000 minimum cash requirement are covered.
Pay Yourself When
Fill a real CEO role
Budget $150,000 annually
Keep cash above $893,000
Fund core costs first
Tighten Draws If
Enrollment drops below 90%
Instructor payroll is strained
Acquisition spend rises
Capex needs cash
What coding bootcamp profit margin matters most?
For a Coding Bootcamp, delivery margin matters most because software and cloud COGS run 50% of revenue in Year 1 and only ease to 30% by Year 5; see What Is The Estimated Cost To Open, Start, And Launch Your Coding Bootcamp Business? for the launch-cost side of the model. After that, watch acquisition efficiency, since marketing and student acquisition fall from 80% to 40% and career services drop from 40% to 20%. Payroll rises from $780K to $1,408M, so instructor utilization has to improve as cohorts scale.
Delivery margin
Year 1 COGS: 50% of revenue
Year 5 COGS: 30% of revenue
Improve instructor utilization as cohorts grow
Keep cloud costs tied to seats sold
Scaling pressure
Marketing and acquisition: 80% to 40%
Career services: 40% to 20%
Payroll rises from $780K to $1,408M
Spread fixed pay across more students
How many students does a coding bootcamp need to be profitable?
On this model, a Coding Bootcamp needs about 54 occupied seats out of 60 total seats to match the base capacity assumption. Here’s the quick math: monthly fixed overhead is $133K, Year 1 payroll is $780K, and weighted Year 1 tuition capacity is about $3,708 per seat before discounts. So profitability depends more on paid enrolled students than on lead volume.
Capacity math
60 total seats
90% occupancy target
About 54 occupied seats
$133K monthly fixed overhead
Revenue driver
Year 1 payroll: $780K
Tuition capacity: $3,708 per seat
Discounts cut that fast
Paid enrollments beat lead volume
Key Takeaways
Enrollment fills seats and drives tuition revenue first.
Net tuition matters more than headline price.
Acquisition spend must drop as cohorts fill.
Keep $893K reserves separate from profit.
Compare lean, base, and high owner-income scenarios
Owner income scenarios
Owner income moves with seat fill, tuition mix, and staffing depth. The low case keeps the first-year build modest, while base and high cases assume more seats, fuller classes, and thinner cost rates.
Three operating paths for owner pay and profit.
Scenario
Low CaseDownside
Base CaseBase
High CaseUpside
Launch model
This is the lower-earnings path, anchored to the Year 1 launch model.
This is the modeled middle path, using Year 3 scale.
This is the stronger-earnings path, using Year 5 scale.
Typical setup
It assumes 60 seats, 90% occupancy, $780K payroll, and 17% combined COGS and variable costs, with the CEO Program Director still on a $150K role.
It assumes 75 seats, 92% occupancy, $1.053M payroll, and 13% combined COGS and variable costs, with staffing lifted across instruction, admissions, and operations.
It assumes 90 seats, 94% occupancy, $1.408M payroll, and 9% combined COGS and variable costs, with a larger instructor and support team.
Cost drivers
60 seats
90% occupancy
$780K payroll
17% combined cost load
$2.01M EBITDA
75 seats
92% occupancy
$1.053M payroll
13% combined cost load
$5.05M EBITDA
90 seats
94% occupancy
$1.408M payroll
9% combined cost load
$10.28M EBITDA
Owner income rangeBefore owner reserves
$150KLower pay
$150K + $5.05M EBITDAModeled base
$150K + $10.28M EBITDAProfit upside
Best fit
Use this if you want a conservative view of the first operating year and want to stress-test cash and staffing.
Use this for the most likely operating path if enrollment grows as planned and the class mix stays balanced.
Use this to test upside if demand stays strong, classes fill fast, and added headcount still holds margins.
!
Planning note: These scenario figures are researched planning assumptions only, not guaranteed earnings, salary promises, tax advice, or distributions.
Coding Bootcamp Core Six Income Drivers
Enrollment Volume
Enrollment Volume
Enrollment volume is the number of paid students in each cohort. Here, the jump from 60 seats in Year 1 to 90 seats in Year 5 matters a lot: at 90% occupancy, that is 54 students; at 94%, it is 84.6 students, or about 85. More filled seats raise tuition revenue and spread fixed costs across more students, so owner take-home income improves faster than traffic alone would suggest.
What this hides is demand quality. If placement credibility slips, qualified applicants can fall even when ad clicks rise, and empty seats are expensive because most fixed costs do not drop with lower enrollment. One clean rule: traffic only matters if it turns into paid seats.
Track Filled Seats, Not Just Leads
Measure applicants, qualified applicants, enrolled students, and occupancy rate by cohort. Also track the conversion path from inquiry to paid seat, because weak placement results can lower qualified demand even when lead volume grows.
Use a simple test: if capacity is 60 seats, you need 54 paid students at 90% occupancy; at 90 seats, you need about 85 paid students at 94%. Build forecasts from paid enrollments, then check whether each added student still covers variable teaching, admissions, and support load before owner pay rises.
Net Tuition Collected
Net Tuition Collected
Net tuition collected is the cash left after discounts, scholarships, refunds, payment timing, and financing fees. With tuition from $2,000 to $6,200, the owner’s pay depends on cash received, not the sticker price. The effect is high because a small discount across full cohorts compounds quickly.
Here’s the quick math: every dollar lost to refunds or fee offsets cuts cash for payroll, marketing, and owner draw. If payment plans slow receipts, reported revenue can look fine while bank cash stays tight. That gap matters most when cohorts are full and monthly payroll is due before student payments clear.
Track cash, not just enrollments
Measure gross tuition, net collected tuition, refund rate, discount rate, and financing fee rate by cohort. Separate billed amounts from cash received so you can see what actually funds payroll. If cash per student drops, owner pay should drop in the forecast too.
Track net cash per enrolled student.
Split by program and payment plan.
Log refunds within 30 days.
Review discounts before each cohort.
Protect margin by limiting ad hoc discounts and tightening refund rules. If financing fees rise or payment timing slips, update the cash forecast right away so fixed costs and owner draws stay covered. The key test is simple: collected tuition must still cover payroll and overhead on time.
Student Acquisition Cost
Student Acquisition Cost
Student acquisition includes ads, webinars, admissions staff, partnerships, and referrals, but the real metric is cost per enrolled, paid student. In Year 1, marketing and acquisition can run at 80% of revenue, then fall to 40% by Year 5. Weak conversion pushes cost per enrollment up, delays cash coming in, and cuts owner distributions even if lead volume looks strong.
Track Cost Per Paid Enrollment
Measure spend against paid enrollments, not leads. Here’s the quick test: channel spend ÷ deposits collected. Break it out by webinar, admissions, partnerships, and referrals, then compare it to collected tuition and cohort fill rate. A channel that brings traffic but few deposits hurts cash flow. Focus budget on the sources that convert, since this driver is high at launch and only moderate once referrals build.
Overhead And Reserves
Overhead And Reserves
Fixed overhead is $133K per month, and it includes $8K rent, $12K utilities and internet, $800 subscriptions, $500 insurance, $15K accounting and legal, $1K curriculum platform, and $300 hosting. For a coding bootcamp, this cost base hits cash flow before owner pay, so gross profit must cover it first or distributions get overstated.
Minimum cash is $893K, and reserves must stay separate from profit. That means the owner should not count reserve cash as take-home. With $161K launch capex plus operating reserve needs, the real test is cash left after payroll, rent, and program costs, not just monthly profit on paper.
Keep Reserves Off the Payout Sheet
Track monthly overhead coverage and reserve balance separately from profit. A simple rule helps: owner pay only comes from cash left after fixed overhead, and reserves stay untouched until the $893K floor is met. If overhead rises faster than enrollment or tuition collection, pause draws fast.
Build a monthly cash forecast with tuition collected, fixed overhead, and reserve minimum as separate lines. The key check is whether program cash covers $133K before any owner distribution. If not, the business may look profitable while still being one weak cohort away from a cash squeeze.
Instructional Delivery Cost
Instructor Payroll
Instructor payroll is the main gross-margin pressure point. As lead instructor FTEs rise from 10 to 20 and instructor mentor FTEs rise from 30 to 70, labor can grow faster than tuition if cohorts are not full. That trims cash left for owner pay, even when demand looks fine on paper.
Owner-teaching can protect early margin, but it also caps scale. Hired instructors only work well when cohort occupancy is high enough to absorb salaries, so the real metric is tuition per teaching FTE, not headcount alone. If staffing outruns enrollment, gross margin drops first and owner draws feel it next.
Fill Seats Before Adding Teachers
Track students per instructor FTE, cohort fill rate, and monthly payroll together. If you add a lead instructor or mentor before the next cohort is close to full, you raise fixed cost without lifting revenue at the same pace. That is the fastest way to compress margin and slow owner take-home income.
Use a simple test: compare tuition collected from each cohort against the full instructional payroll needed to deliver it. If payroll is rising from 10 to 20 lead FTEs and 30 to 70 mentor FTEs, the business needs denser cohorts, tighter scheduling, or more owner-led teaching until utilization improves.
Track payroll per enrolled student.
Delay hires until cohorts fill.
Watch owner-teaching hours and burnout.
Price for margin, not just seats.
Cohort Frequency
Cohort Frequency
Cohort frequency is how often new classes start. In this model, revenue rises only when demand, staffing, and outcomes can support more starts. The key inputs are seats filled, instructor and mentor capacity, admissions throughput, and placement results. The model uses 20 to 22 billable days per month as utilization improves, so extra cohorts help only if each start stays full and high quality.
Too much cadence can backfire. If cohorts are rushed or underfilled, refunds can rise and future enrollment can slip, which cuts owner take-home even if top-line tuition looks stronger. One clean rule: more starts are not more income unless each cohort protects margin and outcomes.
Manage Start Rate and Quality
Track fill rate, refunds, placement outcomes, and staff load before adding a cohort. If admissions cannot fill seats on time or career services cannot support graduates, the extra start can lower cash and profit instead of lifting them. Build the schedule from staff capacity first, then open the next cohort only when demand is proven.
Use a simple gate: start the next cohort only if current classes are near full, instructors are not stretched, and outcomes stay stable. Watch for overtime, slower feedback, and weaker placement signals, because those are early signs that cadence is too high. Empty seats and weak outcomes cost more than they earn.
Track seats filled per start
Watch refund and placement rates
Limit starts to staff capacity
Protect billable days at 20 to 22
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.