How Much Profit Can the Owner Keep from a Laundromat?
Laundromat Bundle
For a single attended U.S. neighborhood laundromat, a realistic stabilized owner-income planning range is roughly $55,000-$70,000 a year. The base model produces $62,148 of annual owner income after a 25% tax reserve and 12% reinvestment reserve on $504,000 of annual revenue. It assumes about 32 washers, $7,500 of monthly non-owner payroll, $11,000 of fixed overhead, and $4,000 of monthly debt service. Low and high cases produce $19,488 and $123,120. These are planning estimates of owner cash capacity after operating costs, debt, and reserves, not revenue, EBITDA, a guaranteed distribution, or a substitute for the owner's actual tax and capital needs.
Owner income$62KNet margin12%Revenue for target pay$550KBusiness difficultyHard
How much can a laundromat owner make from one store?
A single store can produce little owner cash during a weak ramp and more than $100,000 in a strong year; the useful measure is what remains after machines, lease, payroll, debt, and reserves. The Laundry Association industry overview says performance depends on demographics, vend prices, equipment condition, competition, and turns per day. Its broad historical cash-flow range is a warning against treating one national earnings figure as a forecast.
This article models an owner-operated, attended laundromat: the owner handles management, collections oversight, vendor coordination, and maintenance supervision, while attendants and wash-dry-fold labor sit in payroll. The 2026 American Coin-Op survey reported 5.1 average daily turns for front loaders among respondents; the base case uses a more cautious 4.5 turns per washer per day.
Revenue is customer spending. Gross profit here is revenue after utilities, payment fees, consumables, and other non-labor direct costs. Operating profit is after non-owner payroll, overhead, and marketing; EBITDA is different and does not automatically equal cash. Owner income is the residual after operating costs, debt service, and modeled reserves. Any salary paid to a working owner must come from that capacity rather than being added on top.
Owner income calculator
Adjust laundromat sales, direct margin, payroll, overhead, debt, and reserves to estimate cash available to the owner.
i
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
1
Turns per day
4.5 base TPD
Every extra washer turn uses capacity already paid for, so utilization is the strongest operating lever before peak labor or maintenance has to rise.
2
Vend price and dryer capture
$5.50 blended wash
Price by machine size and protect dryer revenue; a few cents of underpricing on every cycle compounds across thousands of monthly turns.
3
Utility efficiency
24% direct-cost allowance
The base gross-margin assumption leaves 24% of sales for utilities, card fees, consumables, and other non-labor direct costs.
4
Labor and owner coverage
$7.5K monthly payroll
Attendant and wash-dry-fold staffing must match service hours; replacing owner management with paid coverage reduces the residual available to the owner.
5
Rent and lease terms
$5K base rent assumption
Rent is embedded inside $11,000 of fixed overhead; a lease that only works at upside utilization creates fragile owner income.
6
Equipment uptime and capital
$4K debt + 12% reserve
Debt service is fixed in the model while a separate reinvestment reserve protects future machine, water-heater, and payment-system replacement.
Want to test laundromat owner income in a full forecast?
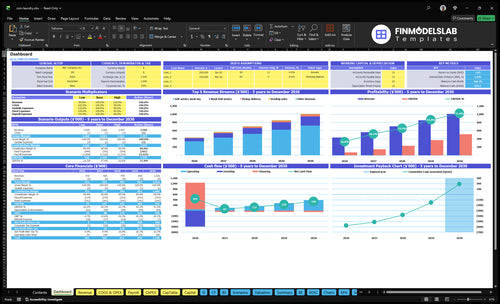
The dashboard preview connects the owner-income question to a full forecast. It can pressure-test washer turns, service mix, seasonality, direct costs, payroll, financing, and replacement capital together instead of assuming one margin every year.
What revenue level supports a $7,000 monthly owner target?
In the base case, the store needs $45,804 of monthly revenue, or $549,648 annualized, to support a $7,000 monthly owner target under the fixed calculator formula. At $42,000 of revenue, modeled owner income is $5,179 a month after reserves, leaving a $1,821 gap. The 2024 Laundry Association industry survey reported medians of 31 washers, 28 dryers, $335,000 of 2023 gross revenue, and 2,740 square feet among responding stores. Those medians are context, not a sales promise.
Base self-service math is 32 washers × 4.5 turns a day × 30.4 days × a $5.50 blended washer vend price, or about $24,100 monthly washer revenue. Dryer revenue at 50% adds about $12,000; roughly $5,900 more comes from wash-dry-fold, vending, and related sales. The 2026 American Coin-Op survey found drop-off wash-dry-fold prices from $1.00 to $3.50 per pound, with $2.00 most common, so service revenue should not be assumed to rescue weak self-service demand.
Build sales from physical capacity
Track turns per washer size, not only total store revenue.
Measure the effective vend price after discounts and loyalty credits.
Keep dryer revenue as a percentage of washer revenue and investigate leakage.
Separate wash-dry-fold pounds and price per pound from self-service machine sales.
Know two revenue floors
Base cash break-even including $4,000 monthly debt service and before owner pay or reserves is about $31,184 per month: $23,700 divided by a 76% gross margin.
The $7,000 owner-pay target raises required revenue to $45,804 per month because target pay must also survive the 25% tax and 12% reinvestment reserves.
Marketing is a $1,200 monthly planning assumption, not a sourced industry average; location quality and repeat use usually matter more than broad advertising.
If the target requires more turns than the local machine mix can physically earn, the answer is a lease, price, service-mix, or capital decision, not a prettier forecast.
How do utilities, rent, and payroll squeeze laundromat margin?
Utilities, rent, and payroll can consume owner income even when the store looks busy. The base case leaves 24% of revenue for utilities and other non-labor direct costs, then deducts $7,500 monthly payroll and $11,000 fixed overhead. The 2026 American Coin-Op survey reported utilities averaging 19.5% of gross among respondents. Because local water, sewer, gas, and electric rates vary, underwrite the site from actual bills or local tariffs.
The 2024 Laundry Association survey reported median monthly rent of $4,000 and median rent-to-gross of 18% among rented stores; median payroll was 20% of gross among stores with payroll, excluding owner compensation. National BLS May 2025 wage data puts laundry and dry-cleaning workers at a $16.78 median hourly wage. The model's $7,500 payroll therefore assumes active owner management, not a fully manager-run store.
What belongs in gross margin
Water, sewer, gas, electricity, payment processing, detergent or bags used for service work, and other non-labor direct costs.
No attendant payroll: all employee labor sits in the labor-cost field.
No rent or routine repair overhead: those sit in fixed overhead.
No major machine replacement: that is funded from the reinvestment reserve rather than hidden in routine direct cost.
Small cost misses are annual-income misses
A three-point direct-cost increase on $42,000 monthly revenue is $1,260 a month, or $15,120 a year before reserves.
A $2,000 monthly rent miss reduces cash before reserves by $24,000 a year.
One additional full-time-equivalent role can consume tens of thousands of annual owner capacity before payroll taxes or benefits.
Compare commercial washers by water and energy characteristics; ENERGY STAR commercial washer specifications show meaningful differences in water and energy performance across certified models.
Key Takeaways
The base model produces $62,148 of annual owner income on $504,000 of revenue after debt service and modeled tax and reinvestment reserves.
Machine utilization and effective vend pricing create revenue; utility efficiency, payroll, rent, and equipment financing decide how much of that revenue reaches the owner.
A laundromat can show accounting profit and still have little safe distribution cash if debt payments, replacement capital, or tax reserves are underfunded.
An owner salary is payment for work, while a distribution is residual ownership return; this model treats both as coming from the same owner-income capacity so they are not double counted.
Can a laundromat run without the owner working full time?
Yes, but absentee operation is a different cost structure, not free passive income. The base assumes the owner handles management while $7,500 monthly payroll covers attendants and service labor. Replacing the owner with paid management must increase labor unless higher sales offset it. The 2024 Laundry Association survey found 49% of responding stores attended for all business hours and 42% for some hours, showing that staffing design is a financial decision.
Tax form matters too. If an owner uses an S corporation and performs services, the IRS says shareholder-employees must receive reasonable compensation before non-wage distributions. The $62,148 base output is therefore total modeled owner cash capacity after reserves, not $62,148 of guaranteed distributions; part may need to be W-2 wages depending on entity structure and professional tax advice.
$7,500 monthly labor covers non-owner attendants and wash-dry-fold work.
Owner pay is the residual output after business costs and reserves; no owner wage is buried in labor.
If the owner performs more attendant work personally, the economics may improve, but that is compensation for labor rather than passive return.
Manager-run adjustment
Add manager and replacement attendant coverage to payroll before judging distributions.
Set a lower owner draw during equipment-heavy months even if the income statement remains profitable.
Keep debt service separate from payroll and overhead so financing never disappears inside an operating-cost percentage.
Do not call a store passive unless the model pays market-rate management and still leaves an adequate return after reserves.
What do low, base, and high owner-income cases look like?
The three cases use the same formulas while changing revenue, direct margin, payroll, overhead, marketing, and reserves together. The high case adds labor and overhead with higher sales; the low case retains minimum fixed costs. They are planning assumptions informed by 2026 operator evidence on turns, pricing, and utilities plus 2024 Laundry Association data on rent, payroll, and revenue, not earnings forecasts.
Owner income scenarios
Compare one-store low, base, and high operating presets that reconcile to the calculator above.
Low, base, and high laundromat owner-income planning cases
Scenario dimension
Low CaseConservative
Base CasePlanning base
High CaseStrong utilization
Launch modelAnnual sales basis
$32,000 monthly revenue
Slower machine use and service ramp
$42,000 monthly revenue
32-washer attended neighborhood store
$60,000 monthly revenue
Higher turns and stronger ancillary mix
Typical setupUtilization and mix
About 3.4 washer turns per day
73% gross margin
Modest wash-dry-fold volume
About 4.5 washer turns per day
76% gross margin
Dryer revenue near 50% of washer revenue
About 5.5 washer turns per day
78% gross margin
More large-machine and service revenue
Cost driversMonthly cash structure
$6,000 labor
$10,000 fixed overhead
$900 marketing + $4,000 debt
$7,500 labor
$11,000 fixed overhead
$1,200 marketing + $4,000 debt
$10,500 labor
$12,500 fixed overhead
$1,800 marketing + $4,000 debt
Owner income rangeAfter modeled tax + reinvestment reserves
$19,488
$62,148
$123,120
Best fitOperating interpretation
Ramp year or soft location
Owner draw stays restrained
Stabilized owner-operated store
Balanced self-service and modest WDF
Strong utilization and pricing
Added staffing supports added volume
i
Planning note: Scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
What are the six biggest drivers of laundromat owner income?
The six drivers are turns per day, vend price and dryer capture, utility efficiency, labor and owner coverage, rent and lease terms, and equipment uptime with capital discipline. The Laundry Association uses turns per day as a core performance measure and notes dryer income often runs around 40%-60% of washer income. Track these unit economics before relying on one profit percentage.
1. Turns per day and machine mix
Use cycle count as the first revenue reality check
The base assumes 4.5 turns per washer per day, below the 5.1 front-loader average in the 2026 American Coin-Op survey. Quick math: 32 washers × 4.5 turns × 30.4 days × $5.50 blended vend equals about $24,077 monthly washer sales. Dryer revenue at 50% brings self-service machine sales to about $36,100 before WDF or vending.
An extra 0.5 turn per washer per day adds about $2,675 monthly washer sales and roughly $4,000 total machine sales if dryer revenue rises proportionally. That is why utilization should improve before more machines are added: capital must produce productive turns.
Track capacity by washer size
Average store TPD can hide an overloaded 60-pound bank and idle small machines.
Weekly turns per day by washer size.
Revenue per washer and per available machine hour.
Peak-period wait time and abandoned loads.
Downtime by machine, not only total repair spend.
2. Vend price and dryer capture
Price the machine mix, not a generic wash
Pricing varies by machine size. The 2026 American Coin-Op survey reported common prices around $5 for 30-pound, $6 for 40-pound, and $8 for 60-pound washes. The base uses a $5.50 weighted washer price and a 50% dryer-to-washer revenue ratio.
On roughly $36,100 monthly machine revenue, a 5% effective price lift at unchanged turns adds about $1,805 of sales. Price can have strong flow-through because utility use per cycle does not rise 5% with price, but lost turns can erase the gain. Track utilization before and after price changes.
Audit realized price, not the menu board
Discounts, loyalty credits, free dry, and promotion codes can make posted prices misleading.
Effective washer revenue per paid turn.
Dryer revenue as a percentage of washer revenue.
Turns before and after each price change.
Revenue mix by 20-, 30-, 40-, 60-, and 80-pound machines.
3. Utility efficiency and direct costs
Protect gross margin from the meter outward
The base 76% gross margin leaves 24% of revenue for utilities, payment fees, consumables, and other non-labor direct costs before payroll. The 2026 operator poll reported utilities alone averaging 19.5% of gross. On $42,000 monthly sales, a three-point utility deterioration removes another $1,260 before payroll, rent, debt, or owner reserves.
Water and energy are purchased every cycle. The ENERGY STAR commercial washer directory shows certified models with different water and energy characteristics. Pair those specifications with local water, sewer, gas, and electric rates and expected turns to estimate dollars per cycle.
Manage utilities as dollars per turn
Utility percentage can look better merely because prices rose, so use both percentage and per-cycle measures.
Water and sewer cost per washer turn.
Gas cost per dryer revenue dollar.
Utility cost as a percentage of total revenue.
Hot-water system efficiency and leak exceptions.
4. Labor and owner coverage
Decide which hours require paid coverage
The base carries $7,500 monthly non-owner payroll, about 17.9% of revenue, close to the 20% payroll-share median reported in the 2024 Laundry Association survey for stores with payroll, excluding owner compensation. May 2025 BLS wage data puts the national median laundry-worker wage at $16.78 an hour, so 40 hours a week is roughly $2,900 monthly base wages before employer taxes, overtime, benefits, or local premiums.
Replacing the owner with another full-time role can consume a large share of the base $62,148 owner-income output. Wash-dry-fold may justify more staff when pounds and price support the contribution margin, but its labor should be measured against service revenue rather than hidden in general payroll.
Separate owner work from employee labor
This keeps operating profit and distributions from looking artificially high.
Paid labor hours per $1,000 of revenue.
WDF pounds processed per labor hour.
Owner hours spent on management and maintenance.
Coverage cost required to make the store truly manager-run.
5. Rent and lease terms
Underwrite rent at base sales, not best-case sales
The base assumes about $5,000 rent and CAM inside $11,000 fixed overhead, or 11.9% of $42,000 monthly revenue. The 2024 Laundry Association survey reported $4,000 median monthly rent among rented respondents and 18% median rent-to-gross. A higher-rent site must compensate through turns, price, machine mix, or ancillary revenue.
If rent is $7,000 instead of $5,000, base cash before reserves falls $2,000 monthly. After the model's 25% tax and 12% reinvestment reserves, owner cash falls roughly $1,260 monthly, or $15,120 annually, assuming other inputs do not change.
Track occupancy before renewal pressure arrives
Long equipment lives can tempt owners into leases that become expensive before the machines are replaced.
Rent and CAM as a percentage of trailing-12-month revenue.
Revenue per square foot and per washer.
Remaining lease term versus equipment financing term.
Scheduled rent escalations in the next 36 months.
6. Equipment uptime, debt, and reinvestment
Treat replacement capital as a real owner-income claim
Commercial laundry equipment ages. The Laundry Association lists typical useful lives of 10-15 years for many front-load washers and dryers. The base case carries $4,000 monthly debt service and a 12% reinvestment reserve, equal to $986 in the static base month.
A $20,000 unplanned replacement equals nearly one-third of the model's $62,148 annual owner income without a reserve. Financing can smooth the hit but does not erase it; any principal-and-interest payment still has to fit ordinary store cash flow rather than peak-month sales.
Measure uptime and funded replacement together
A machine can be "profitable" on paper while deferred maintenance is silently borrowing from the future owner.
Machine downtime hours and lost turns by asset.
Routine repair expense separate from replacement capex.
Debt-service coverage using ordinary monthly cash flow.
Reinvestment reserve balance versus the next likely machine or water-heater replacement.
Safe distribution cash comes after operating bills, debt service, tax reserve, replacement capital, and a working-cash buffer are funded. Earlier draws may simply borrow from the next equipment replacement.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.