How Much Can a Configuration Management Services Owner Make? $175K+
Configuration Management Services Bundle
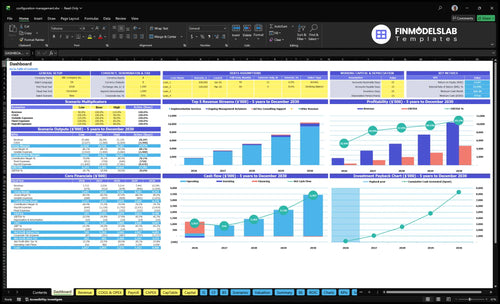
A configuration management services owner can model $175,000 of annual operator pay in this plan, before any optional distributions The business generates $1715M of Year 1 revenue and $377k of EBITDA, then reaches $7441M of revenue and $3012M of EBITDA by Year 4 That moves EBITDA margin from 220% to 405%, based on the researched assumptions Owner income depends on client count, retainers, billable utilization, delivery payroll, overhead, and cash reserves
Owner income$175kNet margin22%–45%Revenue for target pay$1.715MBusiness difficultyHard
Want to test your owner take-home?
Owner income calculator
Estimate owner take-home and the target-pay gap from revenue, margin, costs, reserves, and target pay.
!
Planning note: This is a researched planning estimate, not guaranteed salary, tax advice, or owner distribution advice.
Want the six income drivers?
1
Recurring Retainers
40%-85%
Moving more work onto retainers steadies cash and lifts repeat revenue as recurring mix rises to 85% by Year 5.
2
Project Pricing
$225-$265/hr
Higher implementation rates push the biggest service line and raise revenue without adding the same headcount.
3
Utilization
22.5-28.5h
More billable hours per active customer spread fixed cost across more revenue and improve EBITDA.
4
Delivery Mix
$558K-$2.63M
Payroll rises from about $558K in Year 1 to $2.63M in Year 5, so staffing mix is the biggest margin lever.
5
Client Concentration
High
A few large accounts can swing billings and cash timing, so a broader client base protects owner income.
6
Overhead Reserve
$12.65K/mo
Fixed overhead sets the cash floor, and the model's minimum cash drops to $773K in Month 6.
Want the full Configuration Management Services income model?
What profit margin can a configuration management consulting business earn?
Configuration Management Services can model very high EBITDA margin, or operating profit before interest, taxes, depreciation, and amortization: 220% in Year 1, then 349%, 379%, and 405% by Year 4. The cost base is driven by delivery payroll, technology licensing, cloud demo infrastructure, sales commissions, travel, fixed overhead, and marketing, and you can read more in How Increase Profitability Of Configuration Management Services?
Margin drivers
$12,650 fixed overhead per month.
Non-payroll variable costs drop from 29% of revenue.
They reach 19% by Year 5.
Cost control matters most in delivery payroll.
Key watchouts
Lower contractor cost helps only if quality holds.
Renewal rates must stay strong.
Delivery speed has to stay fast.
Sales commissions and travel still hit margin.
Solo vs team configuration management services income: which model works?
The solo model keeps Configuration Management Services lean, but it caps billable capacity and makes sales time expensive. A team model adds payroll of $5,575k in Year 1, $950k in Year 2, $1,430M in Year 3, and $2,005M in Year 4, but it can support larger revenue. The managed retainer model gets more predictable as retainer adoption rises from 40% to 85%; the real tradeoff is utilization, quality control, documentation, client concentration, owner freedom, and cash risk.
Solo model
Keeps payroll and overhead lean
Caps billable hours hard
Makes founder sales time expensive
Raises client concentration risk
Team model
Adds payroll cost in every year
Supports larger revenue capacity
Improves retainer predictability
Needs tighter quality control
How much can a configuration management services owner take home?
A Configuration Management Services owner can model $175,000 in annual salary, or about $14,583/month, before any profit distributions. See What Are The 5 KPI Metrics For Configuration Management Services? because take-home depends on billable capacity, cash reserves, and reinvestment, not just EBITDA.
Owner Pay
$175,000 modeled annual owner salary
$14,583/month before distributions
Separate CEO pay from profit
Distribute only after cash reserves
Profit Upside
Year 1 EBITDA: $377k
Year 2 EBITDA: $1.233M
Year 3 EBITDA: $1.974M
Year 4 EBITDA: $3.012M
Key Takeaways
Retainer adoption rises from 40% to 85%, smoothing income.
Projects create upfront cash and set support pricing.
Utilization grows revenue, but handoffs need enough slack.
Cash reserves matter because profit is not free cash.
Compare lean, base, and scaled owner-income scenarios
Owner income scenario table
Owner income moves with revenue, retainer adoption, billable hours, and payroll. These scenarios show how the same service business can look cash-heavy in Year 1 and scale-ready by Year 4.
Low, base, and high owner income cases for configuration management services.
Scenario
Low CaseCash-heavy
Base CaseBalanced
High CaseScale-ready
Launch model
Year 1 is the lean case, with $1.715M revenue and $377k EBITDA on a 22.0% margin.
Year 3 is the modeled middle case, with $5.214M revenue and $1.974M EBITDA on a 37.9% margin.
Year 4 is the stronger case, with $7.441M revenue and $3.012M EBITDA on a 40.5% margin.
Typical setup
The business stays lean with 40% retainer adoption, 22.5 billable hours per active customer, a $175k CEO salary, and a $45k marketing budget.
The business is broader at 70% retainer adoption, 25.5 billable hours per active customer, and about $1.43M payroll.
The model assumes 80% retainer adoption, 27.0 billable hours per active customer, and about $2.005M payroll.
Cost drivers
40% retainer adoption
$45k marketing
22.5 billable hours
$175k CEO salary
70% retainer adoption
$1.43M payroll
$85k marketing
25.5 billable hours
80% retainer adoption
$2.005M payroll
$110k marketing
27.0 billable hours
Owner income rangeBefore owner reserves
$377k EBITDACash-heavy
$1.97M EBITDABalanced
$3.01M EBITDAScale-ready
Best fit
Use this to stress-test the plan if sales stay early and the owner keeps the team small.
Use this as the core plan for budgeting, hiring, and cash control.
Use this to test hiring pace, delivery load, and cash needs at scale.
!
Planning note: Scenario ranges are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distributions.
Configuration Management Services Core Six Income Drivers
Recurring retainer revenue
Recurring Retainer Revenue
When implementation clients roll into monthly retainers, owner pay gets steadier. At 40% retainer adoption in Year 1, each retainer customer pays $2,925/month for 15 hours at $195/hour; by Year 5, adoption rises to 85% and the fee is $4,700/month for 20 hours at $235/hour. That shifts revenue from one-off work to predictable cash flow.
Here’s the quick math: monthly retainer revenue equals retainer customers × monthly fee. The catch is scope control. If documentation is thin or response promises are open-ended, unpaid time creeps in and the retainer stops protecting margin. One extra hour on every account can quietly erase the gain from higher pricing.
Measure Retainer Hours, Not Just Retainer Count
Track retainer adoption rate, hours used per client, and unbilled overage each month. If a client is sold 15 hours or 20 hours, the team should document what fits inside that block and what triggers change orders. That keeps recurring work from turning into free support and helps forecast owner draw with less noise.
Watch hours versus plan
Define response times in writing
Log scope changes fast
Price added work separately
Also, use retainer renewals to smooth staffing. A higher mix of recurring work lowers the swing in monthly cash, but only if service levels stay tight and the team does not promise unlimited cleanup. The real win is stable revenue with clean margins, not just a bigger monthly invoice.
Client retention and concentration
Client Retention and Concentration
Retention is the share of implementation clients that stay on ongoing management retainers. That matters more each year because retainer adoption rises from 40% in Year 1 to 85% in Year 5, so renewals protect a bigger slice of monthly income. If one large client leaves, revenue drops, utilization falls, and the owner may still carry the same staff and fixed overhead.
Track renewal rate, top-client share, and monthly retained hours. Here’s the quick math: a Year 1 retainer is 15 hours at $195, or $2,925 per month; by Year 5 it is 20 hours at $235, or $4,700 per month. Every lost renewal removes recurring cash that often funds the owner’s draw.
Protect Renewal Revenue
Build a renewal file for each account with configuration history, compliance evidence, open risks, and the last fixes. That makes the service less tied to one technical sponsor and lowers churn if staffing changes on the client side. Fast response times matter too, because slow follow-up turns retained hours into unpaid rework.
Review top-client concentration monthly.
Document every system change.
Keep two client contacts active.
Test renewal 60 days early.
If a single account starts to dominate monthly billings, tighten scope and reset expectations before the next term. That protects cash flow, keeps delivery capacity balanced, and makes the owner’s income less exposed to one renewal decision.
Billable utilization and capacity
Billable utilization
Billable utilization is the share of consultant time sold to clients. It turns technical talent into revenue without adding fixed overhead, so higher utilization usually lifts owner profit and pay. Here, average billable hours per active customer rise from 225 per month in Year 1 to 285 in Year 5, a gain of 60 hours or 26.7%.
That only helps if the team still has room for sales, documentation, quality checks, client meetings, and training. Push too hard and you can get short-term revenue, but also more rework, weaker handoffs, and higher churn risk. More billable hours help only when delivery stays stable.
Track usable capacity, not max hours
Use active customers, billable hours per month, hourly rate, and nonbillable time to forecast this driver. Revenue per customer is basically billable hours × hourly rate, so every extra sold hour can raise cash flow and gross profit if it doesn’t crowd out support work.
Track billable versus nonbillable hours.
Set a utilization band, not a max.
Use repeatable implementation playbooks.
Hand off cleanly into retainers.
The best lift comes from standard work and clean handoffs to ongoing management. That keeps capacity productive, protects service quality, and helps owner income by holding margins up while reducing churn risk.
Implementation project pricing
Implementation Project Pricing
Implementation work drives immediate cash and sets the anchor for later retainers. At 120 hours × $225/hour, Year 1 project revenue is $27,000 per customer; by Year 5, 100 hours × $265/hour still produces $26,500. That means the real lever is not just hours saved. It’s whether you price the job for scope, compliance risk, system count, and change-control design.
Underpricing hurts twice: it cuts project profit now and signals a weak rate for ongoing support later. Here’s the quick math: a $25/hour discount on a 120-hour project removes $3,000 of revenue. If the project also feeds the retainer pipeline, weak pricing can lower owner income long after go-live.
Price on Risk Signals
Track three inputs on every quote: estimated hours, hourly rate, and scope complexity. Then add price for regulated work, more systems, and tighter change-control steps. If those inputs are clear, the owner can defend a higher rate instead of guessing and discounting to win the deal.
Use a simple rule: bigger compliance exposure and more system handoffs should raise the price, not just the labor total. The goal is to protect cash up front and keep the project from becoming unpaid pre-sales for future support. A clean scope sheet also helps the retainer start at a stronger anchor.
Overhead and reserve discipline
Overhead and reserves
For this firm, overhead and reserves cut immediate owner pay, but they also keep the business alive. Fixed overhead is $12,650 per month for office, internal systems, insurance, legal, communications, and training, so profit has to cover that before any real draw.
Do not treat profit as distributable cash. Year 1 marketing is $45k, rising to $140k by Year 5, and the minimum cash need hits $773k in Month 6. Cash may also be needed for hiring, hardware, software, sales, and working capital, so owner income depends on what is left after those uses.
Protect cash before pay
Track monthly overhead as a fixed run-rate and keep a separate reserve target. Here’s the quick math: if the firm cannot cover $12,650 plus planned marketing and growth spend, owner draws should wait. The reserve is the buffer that stops one slow month from turning into a payroll or vendor problem.
Use a cash forecast that includes hiring, tools, sales spend, and working capital. The key test is simple: if cash falls below the $773k Month 6 need, cut discretionary spend before cutting service quality. That protects delivery and keeps the owner from pulling out cash too early.
Delivery labor mix
Delivery Labor Mix
If delivery work is mostly owner-led at first, more revenue stays in gross profit because there’s less paid labor between billing and take-home pay. In the plan, payroll rises from $5,575k in Year 1 to $2,630M in Year 5, so the labor mix has to shift carefully as the team grows. Owner hours protect margin early; employees add capacity and continuity.
Subcontractors can flex coverage, but they only help if their cost, quality, and response times stay tight. Lower labor cost is not better if it creates rework, missed client deadlines, or weak trust. For this service business, the key inputs are billable hours, direct labor cost, staffing mix, and rework rate.
Track direct labor spread
Measure delivery labor as a share of revenue and split it by owner, employee, and subcontractor hours. Keep a simple rule: if a cheaper worker causes more rework or slower response, the saved wage can disappear fast. Track billable hours, loaded labor cost (pay plus payroll taxes and benefits), and client response time by project.
Use staff for repeatable work, owner time for high-trust work, and subcontractors only for overflow or niche gaps. The best mix is the one that keeps quality high while protecting gross margin and cash for owner pay. Watch these items each month:
Owner hours on key accounts
Employee utilization on repeat tasks
Subcontractor cost versus margin
Rework and missed response times
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.