How Much Corrugated Box Manufacturing Owners Make On $775M Sales
A corrugated box manufacturing owner’s income cannot be guaranteed from revenue alone Under the supplied assumptions, the plant generates $775M in Year 1 revenue and about $491M before owner pay, debt, taxes, reserves, and any fixed costs not fully provided By Year 5, the model reaches $3345M revenue and about $2380M before those same exclusions Treat these as researched planning outputs, not take-home salary claims
Owner incomeNot determinableNet margin53.2% to 66.1%Revenue for target pay$7.75MBusiness difficultyHard
Want to test your box plant owner pay?
Owner income calculator
Estimate owner take-home and the target-pay gap from revenue, margin, operating costs, reserves, and target pay.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
Want the six income drivers?
1
Volume
540K-1.95M
More run time spreads plant fixed costs across more boxes, and year 5 output is more than triple year 1.
2
Price Mix
$8.50-$32.00
Shifting mix toward custom and heavy-duty boxes lifts average selling price and protects income when standard box volume is flat.
3
Paper Waste
$1.48M-$5.88M
Paper, adhesive, and scrap sit in every box, so small swings in input use hit gross margin fast.
4
Labor Uptime
$210K-$850K
Year 1 direct labor starts near $210K, and better uptime lowers cost per box while lifting EBITDA.
5
Order Mix
6.9%-10.0%
Bigger repeat orders cut freight, commission, and ad drag, while small one-off orders push margin down.
6
Fixed Cost
$85K/mo
The plant starts with about $85.3K a month in known fixed costs, so cash stays tight until volume and collections hold.
Want to check owner income in the full box plant model?
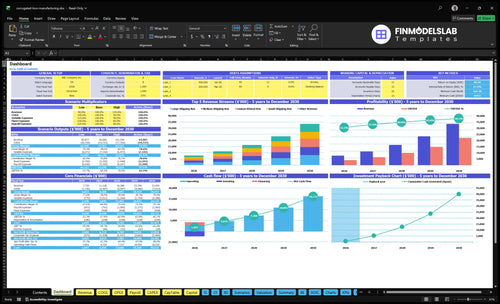
Open the Corrugated Box Manufacturing Financial Model Template to check the dashboard first, then income outputs, sales assumptions, unit pricing, unit COGS, overhead, capex, debt, reserves, and owner pay. Charts compare Year 1 revenue of $775M with Year 5 revenue of $3345M; tables show gross margin from 776% to 790%, and scenario tabs isolate paper, labor, freight, commissions, lease, insurance, equipment payments, and owner distributions.
Owner-income model highlights
Owner pay and reserves
Revenue and margin trends
Cost drivers by scenario
How much revenue does a corrugated box business need to pay the owner?
Corrugated Box Manufacturing doesn’t need one fixed revenue level to pay the owner; it needs revenue equal to (fixed costs + target owner pay + debt + taxes + reserves + reinvestment) ÷ contribution margin, as covered in How To Write A Business Plan For Corrugated Box Manufacturing?. Year 1 contribution is $524M on $775M revenue, so the contribution margin is 67.6%. With known lease and insurance of $330K/year, revenue to cover those costs is about $488K; each $1 of owner pay adds about $1.48 of required sales before debt, taxes, reserves, and missing overhead.
Use The Formula
Add fixed costs
Add target owner pay
Add debt and taxes
Divide by 67.6%
Watch The Gaps
Lease and insurance: $330K/year
Contribution: $524M
Revenue base: $775M
Missing overhead changes pay capacity
Is corrugated box manufacturing profitable?
Yes, Corrugated Box Manufacturing can look profitable on a planning basis, but that is not the same as owner take-home. Under the stated model, $775M in revenue and $601M in gross profit implies about 77.5% gross margin, and pre-owner operating cash is about $491M; that still excludes debt service, taxes, capex reserves, admin payroll, and any other fixed costs not shown.
Planning math
$775M revenue in Year 1
$601M gross profit
About 77.5% gross margin
$330K known fixed costs
What the math hides
$491M pre-owner operating cash
Debt service is not included
Taxes are not included
Capex reserves are not included
What changes small corrugated box plant owner income?
Corrugated Box Manufacturing owner income changes most with role, output, automation, and whether a plant manager is on payroll. If the owner replaces that manager, cash salary can stay in the business, but time risk goes up. Output is projected to rise from 540K units in Year 1 to 195M units in Year 5, and that scale can lift profit, but it usually adds maintenance, equipment financing, inventory, receivables, and reserve needs.
What changes owner income
Owner role changes cash pay.
Plant manager payroll may stay inside.
Time risk rises without a manager.
Capacity data is not provided.
What scale adds
Year 1 volume is 540K units.
Year 5 volume is 195M units.
More volume can raise profit.
More scale needs more working capital.
Key Takeaways
Higher volume helps only if margins stay positive.
Pricing discipline matters more than custom order premium.
Paper costs and waste hit cash fastest.
Overhead and working capital limit distributable cash.
Scenario objective: Compare lean, base, and high owner-income cases using the same box plant economics
Owner income scenarios
Owner income here swings with volume, scrap, freight, and staffing. Year 1 starts at 540,000 units and $7.75M revenue; Year 5 scales to 1.95M units and $33.45M revenue.
Low, base, and high income cases for a corrugated box plant.
Scenario
Low CaseLow Case
Base CaseBase Case
High CaseHigh Case
Launch model
Lower volume and higher waste keep owner pay tight.
Modeled growth supports steady owner income after normal reserves.
Stronger scale lifts pre-owner cash, but pay still depends on debt, taxes, and reserves.
Typical setup
This case assumes weaker mix, more scrap, tighter pricing, and a holdback for reserves after freight and labor costs.
This case uses Year 1 volume of 540,000 units, $7.75M revenue, 77.6% gross margin, and the model's normal fixed cost base.
This case uses Year 5 scale of 1.95M units, $33.45M revenue, and 79.0% gross margin with more sales and production staff.
Cost drivers
Lower unit volume
higher scrap
freight pressure
reserve holdback
tighter owner draw
Planned unit volume
normal scrap
freight and commissions
fixed overhead
steady owner draw
Higher unit scale
better pricing
lower per-unit freight
more sales capacity
larger reserve needs
Owner income rangeBefore owner reserves
Constrained drawDownside case
Steady drawCore case
Upside drawUpside case
Best fit
Use this to test what happens if orders slip and the plant runs below planned capacity.
Use this as the working case for lender talks, hiring, and day-to-day cash planning.
Use this to stress-test upside cash flow if the plant fills capacity and keeps waste in check.
!
Planning note: Scenario ranges are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution guidance.
Corrugated Box Manufacturing Core Six Income Drivers
Production Volume And Capacity Utilization
Production Volume
When output rises, fixed plant costs get spread over more boxes, so gross profit can expand if each order clears material, labor, and setup costs. Here the model uses 540K units in Year 1 and 195M units in Year 5, with revenue rising from $775M to $3,345M. Capacity utilization % is not given, so output is the proxy.
The catch is simple: filling machines with weak orders can lift sales but hurt cash. Owner pay improves only if gross margin stays strong and customers pay on time, because receivables and inventory can trap cash even when volume looks good.
Track Throughput and Margin
Measure monthly units, order count, average run size, gross margin per line, and days to collect. Here’s the quick test: if volume rises but margin per unit falls, you may be buying busy work, not profit. Use output by line to spot low-margin filler orders before they crowd out better work.
Track units by product line.
Watch gross margin per order.
Compare booked volume to cash collected.
Flag long setup or idle time.
Do not price only to keep machines busy. The right volume is the one that covers fixed overhead, keeps collections tight, and leaves enough free cash for owner draws.
Paper Cost And Material Waste
Paper Cost and Waste
Paper cost is the floor under gross margin here. Linerboard, fluting medium, adhesive, inks, and reinforcement materials sit inside Year 1 unit COGS of $148M, with about $113M tied to paper inputs. The owner only earns after these costs, so every supplier change hits cash before any draw.
Here’s the quick math: the model says a 100% paper increase cuts about $1,133K from Year 1 pre-tax cash before pricing actions. Waste rate is not supplied, so trim waste and spoilage should be tracked separately; if waste rises, gross margin falls faster than sales can cover it.
Track yield and spoilage daily
Build the forecast from unit volume, paper mix, supplier price, and yield loss. Add fields for trim waste, spoilage, and rework by line so the model shows true cost per shipped box, not just purchased paper. That is the number that decides owner take-home income.
Track paper cost per shipped box.
Log trim waste by machine.
Separate spoilage from rework.
Reset quotes when paper spikes.
If paper inflation hits, raise quotes fast or cut waste fast. Delayed pricing moves turn into lower gross margin, tighter cash, and smaller owner distributions because material cost sits above owner pay. One clean rule: protect yield first, then reset price.
Customer Mix And Order Size
Order Mix And Cash Speed
This driver is the split between large repeat orders and smaller custom jobs. Big orders can raise output and cut selling time, but they can also push down price and stretch payment terms. Smaller custom boxes can price higher, with custom printed boxes at $2,500 in Year 1 and $2,700 in Year 5, so the owner earns more only if setup time and collections stay tight.
The key inputs are average order size, repeat rate, customer share, and days to collect. One delayed payer can trap cash in receivables, so booked sales do not always turn into spendable profit. Customer concentration means too much revenue tied to one buyer, and that can delay owner distributions even when the plant is busy.
Protect Margin And Collections
Track revenue by customer, quote, and payment term. Here’s the quick math: higher order size helps only if gross margin after material, labor, and print waste still covers overhead and leaves cash to pay the owner. If one account becomes too large, cap exposure, ask for deposits on custom runs, and shorten terms on repeat buyers that stretch payment beyond normal cycle time.
Use a simple rule: more sales is not enough if cash is late. Watch custom order price, repeat volume, and open receivables together, because stronger owner draws come from balanced margin, order size, and collections. If the biggest customer starts paying slower, forecast cash from collected sales, not invoiced sales.
Overhead, Debt, And Cash Reserves
Fixed Overhead and Debt Service
If you’re carrying a $25K/month facility lease and a $25K/month general liability policy, the fixed floor is $50K/month, or $600K/year, before equipment financing, taxes, capex reserves, or admin. That means box margin has to cover a heavy cash load before the owner can safely take money out.
In this business, accounting profit can look healthy while cash is stuck in inventory and receivables. So the real metric is distributable cash after debt service and reserve funding, not just reported profit. If collections slow or stock builds up, owner pay drops even when sales stay strong.
Track Cash Before Owner Draws
Build the monthly cash plan around inventory days, receivables days, debt payments, and a fixed reserve for taxes and capex. The inputs you need are lease, insurance, equipment financing, admin overhead, and expected cash conversion. In a plant, one slow payer can trap cash fast.
Track inventory turns monthly.
Watch receivables aging weekly.
Fund debt before owner draws.
Set a minimum cash buffer.
Use a payout rule: only distribute cash after debt, taxes, and reserve targets are met. That keeps working capital from starving the business and protects the owner from taking profits that only exist on paper.
Labor Productivity And Machine Uptime
Labor Productivity and Machine Uptime
Labor productivity and machine uptime decide how much of each box sale reaches owner pay. Direct machine labor is $210K in Year 1 and $850K in Year 5, or about $17.5K and $70.8K per month. If downtime, setup delays, or overtime rise, the same revenue carries more labor cost, so operating profit drops even when sales look strong.
This driver includes labor hours, changeovers, maintenance inefficiency, and extra cost on product lines with a 10% machine maintenance fund for small boxes plus calibration or testing on other lines. The key inputs are units shipped, labor hours per unit, downtime hours, and overtime rate. More uptime means more gross margin and more cash available for owner draw.
Track Uptime, Not Just Output
Measure output per labor hour, changeover time, downtime, and overtime share every week. Build quotes so setup and testing costs sit in the price, not as surprise margin loss. If actual labor or downtime runs above plan, raise price or cut low-margin runs fast. One clean rule: if uptime slips, owner cash slips too.
Track units per labor hour.
Flag overtime above plan.
Reserve 10% for maintenance.
Price setup and testing separately.
Pricing And Product Mix
Pricing and Product Mix
Box type drives margin here. A corrugated maker can sell small shipping boxes at $850 and heavy-duty boxes at $3,000 in Year 1, so the mix matters as much as unit volume. Higher sticker price only helps if quoted COGS, labor, and waste stay inside the target margin.
Custom printed boxes sell for $2,500 in Year 1, but they also carry $500 unit COGS plus 35% product-level COGS. If that 35% is on sales price, gross profit is about $1,125 before setup time, print waste, and short-run loss. That means custom work can lift revenue and still hurt owner pay if quoting is loose.
Quote by Job, Not by Hope
Track margin by box type, run length, setup minutes, and scrap rate. Here’s the quick math: quote price minus unit COGS, setup labor, and waste tells you if the job actually pays. Use that check before approving custom work, because a busy machine with weak margins still starves cash.
Price each box type separately.
Measure waste on every print run.
Review quoted versus actual COGS.
Set a minimum gross margin floor.
Custom orders should earn their premium, not just look premium. If setup time rises, short runs shrink output, and print waste climbs, the extra revenue can disappear fast. The owner feels that hit as lower gross profit, tighter cash, and less room to take a draw.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Corrugated Box Manufacturing Bundle
Choosing a selection results in a full page refresh.