How Much Can a Custom Jewelry Design Business Make?
A U.S. owner-led custom jewelry design studio can realistically produce anything from about $32,000 to $257,000 a year in owner income after modeled tax and reinvestment reserves, with a defensible base case near $151,200. This article models a direct-to-consumer studio selling made-to-order engagement rings, bands, necklaces, and statement pieces, with the owner leading design and sales, one non-owner bench jeweler plus support in the base case, and no mass-manufacturing or wholesale channel. The base case assumes $75,000 in monthly revenue, roughly 15 custom projects at a $5,000 blended ticket, a 58% gross margin after stones, metal, packaging, shipping, and payment costs, $25,500 of monthly payroll and operating costs, and a 30% combined tax-and-reinvestment reserve on positive pre-reserve profit. The result is owner cash, not a guaranteed salary or GAAP net income. It still has to be classified correctly between wages and distributions for the owner's entity, and actual personal taxes, inventory purchases, unusual repairs, and growth investments can change what is safe to withdraw.
Owner income$151KNet margin17%Revenue for target pay$794KBusiness difficultyHard
How does custom jewelry revenue turn into owner take-home?
The base case starts with $75,000 of monthly sales and ends with $12,600 of owner income after reserves. Stones and metal are absorbed through gross margin, then non-owner payroll, overhead, marketing, and debt service are paid before reserves. The BLS jeweler occupation data reported a $49,140 national median annual wage in May 2024. Here, the owner still works in design, consultations, sourcing, and sales, but owner pay is excluded from labor cost; the output is residual economic take-home before final tax filing and entity-specific classification.
Owner income calculator
Adjust sales, margin, staffing, overhead, reserves, and target pay to estimate monthly owner take-home.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
What moves custom jewelry owner income most?
The strongest levers are booked projects, realized ticket, material yield, bench throughput, consultation conversion, and deposit timing. Skilled labor is also a real constraint: BLS reports that jewelers perform design, CAD, setting, repair, and material-cost work, and that 34% of workers in the occupation were self-employed in 2024. The cards rank the levers by how quickly they change owner cash.
1
Booked projects × ticket
$75K/mo base
Fifteen $5,000 custom projects create the base revenue ceiling; losing three bookings removes $15,000 before any fixed cost changes.
2
Stone and metal margin
58% base
The base keeps 58 cents of each sales dollar after stones, precious metal, packaging, shipping, and payment fees, before payroll.
3
Bench labor productivity
$12K/mo payroll
Production capacity has to rise with orders; the high case adds labor rather than pretending $120,000 of monthly sales can run on base staffing.
4
Consultation conversion
$4.5K/mo marketing
Paid demand only helps when qualified consultations become deposits; track cost per booked project, not clicks or inquiries alone.
5
Deposits and cash cycle
50% deposit plan
A 50% planning deposit on bespoke work can help fund stone and metal purchases; weak deposit discipline turns profitable orders into cash strain.
6
Studio and financing load
$9K/mo base
Base fixed overhead plus debt service totals $9,000 monthly before marketing or payroll, so under-booked months compress owner cash quickly.
Want to test the same owner-income assumptions in a full forecast?
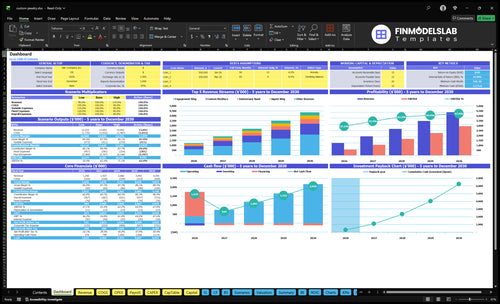
The dashboard preview can help you pressure-test revenue, gross margin, payroll, cash flow, and low/base/high cases together instead of treating owner pay as a single isolated number.
The Custom Jewelry Financial Model and Projections Template shows the business-specific dashboard used for scenario planning. Use it to compare booked-project volume, pricing, material costs, staffing, cash reserves, and financing against your own studio rather than relying on the illustrative assumptions here.
What sales volume supports six-figure owner pay?
The base case needs about $66,133 per month, or $793,596 annualized, to support a $9,000 monthly owner-pay target. At a $5,000 blended ticket, that is roughly 14 completed projects a month. The Knot's 2024 Jewelry & Engagement Study put average U.S. engagement-ring spend at $5,200, while JCK's report on The Knot's 2026 study said the 2025 average fell to $4,600 as lab-grown center stones reached 61% of purchases. A custom studio can price above or below those averages, but ticket pressure must be offset by volume, design fees, or margin.
Base booking math
15 projects × $5,000 = $75,000 monthly revenue.
At 58% gross margin, those sales create $43,500 of gross profit before payroll.
After $25,500 of operating costs, pre-reserve profit is $18,000.
After 30% combined reserves, owner income is $12,600 per month.
What to test before raising the target
Use completed and paid projects, not inquiries, as the volume denominator.
Separate natural-diamond, lab-grown, colored-stone, and metal-heavy pieces because ticket and material percentages differ.
Model rework, rush jobs, resizing, and remake risk in capacity, not as free extra output.
Increase staffing in the high case when production hours or consultation load exceed the owner's practical week.
What margin has to survive stones, metal, and payment fees?
The base planning margin is 58% before payroll, so direct non-labor costs consume 42% of sales. It is a reasoned studio assumption, not a copied chain benchmark. As an adjacent reference, Signet's first-quarter fiscal 2027 filing reported a 35.8% consolidated gross margin and cited higher gold prices as a pressure on merchandise margin. Payment acceptance also matters: Square's U.S. fee calculator lists 2.6% + 15 cents for card-present payments on one plan and 3.3% + 30 cents for online payments. On a $5,000 ticket, those fees belong in direct-cost planning.
Protect project contribution
Quote stones and precious metal with a validity window when input prices are moving.
Track the actual material cost of every completed piece against its quoted allowance.
Keep payment fees, insured shipping, packaging, and certificates in the direct-cost view.
Use design fees or minimum project values when consultation time is high relative to ticket.
One-point margin sensitivity
At $75,000 monthly revenue, one gross-margin point equals $750 of monthly gross profit.
If payroll and overhead do not change, that is $9,000 a year before reserves.
After the base 30% combined reserves, roughly $6,300 of that annual improvement reaches owner income.
That makes material variance and discounting more important than small cuts to software or office supplies.
Key Takeaways
The base case produces $151,200 annual owner income after modeled reserves on $900,000 annual revenue.
About 14 $5,000 projects per month support the modeled $9,000 monthly owner-pay target at base costs and margin.
Margin discipline on stones, metal, and payment fees matters more than revenue growth that is bought with weak pricing.
Owner distributions are safest only after payroll, overhead, debt, tax reserves, and working-capital needs are funded.
Can the studio run without the owner and keep the same distributions?
Usually not at the same revenue and cost base. The owner here is lead designer, sales closer, sourcing decision-maker, and quality-control layer, so replacing that work requires a designer-manager or stronger bench and sales coverage. The base $151,200 is therefore not passive income. BLS describes jewelers as doing design, cost estimation, CAD/CAM, setting, repair, and customer-facing work. If the business is an S corporation, IRS compensation guidance says shareholder-employees must receive reasonable compensation for services before non-wage distributions.
Owner-operated base case
Owner leads consultations, design approvals, vendor selection, pricing, and final quality control.
Non-owner payroll is $12,000 per month and excludes owner pay.
Owner take-home is the residual $12,600 per month after operating costs and modeled reserves.
Bookkeeping may split that economic take-home between payroll wages and distributions depending on entity structure.
Manager-run stress test
Add the market cost of a competent designer-manager before calling the income passive.
If another $7,000 per month of loaded management cost is added with no revenue increase, base pre-reserve profit falls from $18,000 to $11,000.
After the same 30% reserves, monthly owner cash would fall to roughly $7,700.
The better path is to raise revenue capacity and documented processes before removing the owner from production and sales.
How much cash should stay in the business before owner draws?
A profitable custom order can still create a cash squeeze because stones, metal, and findings may be paid before final customer cash arrives. IRS Publication 334 explains that businesses making or selling goods generally account for merchandise, raw materials, work in process, finished goods, and cost of goods sold, subject to small-business exceptions. That is an accounting rule, not a reserve rule, but it shows why inventory timing matters. This model keeps an 8% reinvestment reserve and assumes roughly 50% deposits before large material purchases.
Pay these before distributing cash
Open vendor invoices for stones, precious metal, findings, and insured shipping.
Upcoming payroll, employer taxes, studio rent, insurance, security, and debt service.
Sales-tax remittances and customer refunds, remakes, or warranty work that can hit cash unexpectedly.
A tax reserve: IRS small-business guidance notes that self-employed owners and pass-through owners may need estimated tax payments during the year.
Do not treat compliance as optional overhead
The FTC's jewelry guidance covers truthful descriptions and disclosures for diamonds, gemstones, pearls, and precious metals.
Mislabeling material, treatment, origin, or quality can become a refund, legal, or reputation cost, not just a marketing issue.
Keep vendor documentation and product descriptions tied to each custom project.
Separate cash that is merely passing through for tax or customer materials from cash truly available to the owner.
What do low, base, and high owner-income cases look like?
The low case is owner-heavy and still proving demand; the base case has stable bookings and one core bench employee plus support; the high case adds ticket and volume together with higher payroll, marketing, overhead, and debt service. The owner-income row is not EBITDA or salary. It is annual residual cash after the modeled tax and reinvestment reserves, reconciled to the calculator presets.
Owner income scenarios
Low, base, and high cases show how booked projects, ticket, margin, staffing, overhead, marketing, debt, and reserves change owner cash.
Custom Jewelry Design owner-income scenarios after modeled reserves.
Scenario factor
Low CaseLow
Base CaseBase
High CaseHigh
Launch modelDemand and role assumption
Owner-heavy studio proving demand; about 8 projects per month at a $5,000 blended ticket.
Stable owner-led studio; about 15 projects per month at a $5,000 blended ticket.
Scaled studio; about 20 projects per month at a $6,000 blended ticket with additional staff.
Typical setupRevenue and margin
$40,000 monthly revenue
52% gross margin
$6,500 labor
Owner covers most selling and design
$75,000 monthly revenue
58% gross margin
$12,000 labor
One core bench role plus support
$120,000 monthly revenue
62% gross margin
$22,000 labor
Broader bench and service coverage
Cost driversMonthly cash load
$17,000 operating costs
20% tax reserve
10% reinvestment reserve
$6,000 target owner pay
$25,500 operating costs
22% tax reserve
8% reinvestment reserve
$9,000 target owner pay
$41,500 operating costs
25% tax reserve
10% reinvestment reserve
$14,000 target owner pay
Owner income rangeAfter tax + reinvestment reserves
$31,920
Annual owner income after modeled reserves.
$151,200
Annual owner income after modeled reserves.
$256,620
Annual owner income after modeled reserves.
Best fitUse case
Stress-test a young studio with uneven bookings and heavy owner labor.
Plan a stable appointment-led custom studio with disciplined pricing and one core bench employee.
Test a recognized studio with stronger ticket, more orders, and enough added staff to protect turnaround time.
!
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
Which six income drivers should a custom jewelry owner track every month?
The six drivers below are the same levers ranked earlier, expanded into operating decisions. The point is not to maximize every metric simultaneously. A studio can raise ticket and still damage cash if its stone allowance is loose; it can add bookings and still reduce owner income if bench labor, rework, and marketing rise faster than contribution. Track each lever in dollars per completed project and in monthly cash, then decide whether the next sale genuinely adds distributable income.
1. Booked projects and realized average ticket
Set the sales ceiling with paid projects, not leads
The base case uses 15 completed projects at a $5,000 blended ticket, or $75,000 monthly. If bookings fall to 12, revenue drops $15,000 and, at a 58% gross margin, gross profit falls $8,700 before fixed costs move. The market is moving: The Knot reported $5,200 for 2024 couples, while JCK reported $4,600 for 2025 couples. A custom studio therefore needs to prove any premium through product mix, craftsmanship, service, or design value. Track deposits that convert into completed, fully paid projects at the quoted price, not raw inquiries.
Track a booking waterfall
Measure volume in the same sequence every month so marketing and production decisions use the same denominator.
Qualified consultations booked.
Deposits collected.
Projects completed and paid.
Realized average ticket after discounts and credits.
A two-project shortfall at the base $5,000 ticket is a $10,000 sales miss; do not try to “solve” that with owner draws.
2. Stone and metal margin
Quote material risk before it becomes your problem
The 58% base gross margin is a planning assumption: it is what remains after gemstones, precious metal, packaging, insured shipping, and payment fees, with payroll modeled separately. Signet's fiscal 2027 first-quarter filing said higher gold prices pressured merchandise margin, showing why material exposure matters even for much larger operators. On a $5,000 project, 58% margin leaves $2,900 before payroll; 52% leaves $2,600. Across 15 projects, that $300 gap becomes $4,500 a month, or $54,000 a year before reserves. FTC jewelry guidance also requires accurate product descriptions, so margin protection cannot come from vague material or gemstone disclosure.
Close every job with a material variance
Compare quoted allowance with actual stone, metal, and payment cost before calculating salesperson or owner performance.
Stone cost as a percentage of ticket.
Metal weight and scrap recovery.
Card and financing fee per project.
Gross margin after credits, remakes, and discounts.
One margin point at base sales is $750 per month of pre-reserve profit, enough to matter to owner income.
3. Bench labor productivity
Hire capacity only when throughput justifies it
The base case budgets $12,000 per month for non-owner labor; the high case rises to $22,000 as revenue scales. BLS March 2026 employer-cost data showed retail-trade wages and salaries of $20.41 per hour plus $6.23 in benefits across the broad sector. Actual small-studio pay will vary, but loaded labor cannot be ignored. A new role costing $6,000 per month needs $72,000 of annual gross profit just to cover itself. At a 58% gross margin, that requires about $124,000 of incremental annual revenue before added marketing or overhead.
Measure finished value per paid labor hour
Bench utilization is useful only if quality and turnaround remain acceptable.
Completed project revenue per bench hour.
Rework and remake hours as a percentage of total hours.
Average days from deposit to final delivery.
Payroll as a percentage of gross profit, not just revenue.
Do not treat the owner's extra evenings as free capacity; that only converts business profit into unpaid labor.
4. Consultation conversion and acquisition cost
Buy qualified appointments, not vanity traffic
The base model spends $4,500 per month on marketing, or 6% of revenue, as a planning assumption. If that spend creates 30 qualified consultations and 15 paid projects, marketing cost per booked project is $300; if it creates only 8 projects, the cost is $563. At a $5,000 ticket and 58% gross margin, that conversion difference matters more than click volume. Referrals can lower paid acquisition, but they still consume service and follow-up capacity. Forecast cost per collected deposit and gross profit after acquisition, not cost per click.
Score channels by contribution after CAC
Every referral source, ad set, bridal partnership, and event should be judged on the same booked-project economics.
Marketing spend per qualified consultation.
Consultation-to-deposit conversion rate.
Marketing cost per booked project.
Gross profit after acquisition cost by channel.
Pause channels that produce busy calendars but weak deposits, low tickets, or margin-heavy discounting.
5. Deposits, inventory, and cash-cycle discipline
Finance the job with customer cash where appropriate
Cash can be tied up in a center stone, gold, work in process, or supplier balances even when the P&L looks profitable. The base plan assumes a 50% deposit before major material commitments and an 8% reinvestment reserve. On a $5,000 project, a $2,500 deposit can cover much of the modeled $2,100 direct-cost allowance. But that deposit may still be committed to unfinished work or refunds. IRS Publication 334 distinguishes raw materials, work in process, finished goods, and cost of goods sold; owners should similarly track project cash commitments instead of treating the bank balance as distributable profit.
Keep a project-level cash commitment list
Before every owner draw, identify cash already promised to customers, suppliers, tax authorities, and payroll.
Deposits received on unfinished projects.
Stone and metal purchase orders not yet paid.
Work-in-process cost and expected completion date.
Refund, remake, warranty, and tax obligations.
If the bank balance is high only because several deposits arrived before supplier invoices, the owner is looking at timing, not profit.
6. Studio overhead and financing load
Keep the fixed floor low enough for a slow month
The base case carries $7,000 of fixed overhead plus $2,000 of debt service before marketing or payroll; the low case still carries $8,000 combined. At $40,000 of low-case sales and a 52% gross margin, gross profit is $20,800. After $17,000 of operating costs, only $3,800 remains before reserves, leaving $2,660 of monthly owner income. A showroom lease, security, software, equipment note, and administration can therefore look harmless in a peak month but dominate a slow one. Negotiate the fixed floor before committing to it.
Track break-even before adding another fixed bill
Translate every recurring commitment into the extra monthly revenue needed to carry it at current margin.
Fixed overhead as a percentage of trailing-three-month revenue.
Debt service coverage from pre-reserve profit.
Monthly revenue needed for target owner pay.
Cash runway after open purchase orders and tax reserves.
In the base model, $66,133 monthly revenue supports the $9,000 target owner pay. Any new fixed bill pushes that threshold higher unless margin or productivity improves.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Custom Jewelry Design Bundle
Choosing a selection results in a full page refresh.