How Do Revenue and Margin Affect Owner Pay in an Eco-Friendly Hotel?
Eco-Friendly Hotel Bundle
A 40-room owner-operated Eco-Friendly Hotel in a secondary U.S. leisure market can realistically produce about $264,000 a year of modeled owner income in a stabilized base case, with a downside around $55,000 and an upside around $413,000. The base case assumes about $2.10 million of annual revenue, built from 67% room occupancy, a $195 average daily rate, and ancillary sales equal to roughly 10% of room revenue. It then pays non-labor direct booking and guest costs, $47,000 of monthly employee payroll, $37,000 of fixed overhead, $9,000 of marketing, and $18,000 of debt service before setting aside 24% for taxes and 15% for reinvestment. The owner is assumed to work as general manager, so this income includes compensation for that labor plus residual business return; it is not passive income, a guaranteed salary, or a promise of distributions. Actual property taxes, insurance, financing, local lodging taxes, major renovations, and personal tax liability can move the result materially.
Owner income$264KNet margin13%Revenue for target pay$1.94MBusiness difficultyHard
What would a 40-room eco-friendly hotel pay the owner?
The practical answer is about $22,000 per month in the stabilized base case after modeled reserves, or $263,520 per year. That is a planning output, not hotel-sector average pay. The operating assumptions sit above the 2025 U.S. national lodging averages because this is modeled as a small boutique property with a rate premium, while the national market finished 2025 at 62.3% occupancy and $160.54 ADR according to the HVS 2026 U.S. hotel market summary using CoStar data. The same HVS report also shows why the difficulty rating is Hard: 2025 median ground-up development cost was about $200,000 per room for select-service hotels and $467,000 per room for full-service hotels. This article therefore models a stabilized existing or converted property rather than a new ground-up full-service development.
Owner income calculator
Estimate owner take-home from room revenue, margins, payroll, overhead, debt, and reserve policy.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
1
Occupancy
67% base
Each extra occupied room night spreads the same property and overnight-coverage costs over more revenue, but only if rate and channel cost hold.
2
Average daily rate
$195 base
A $5 ADR move across roughly 9,800 base-case sold room nights changes annual room revenue by about $49,000 before direct booking costs.
3
Labor productivity
27% of sales
Base employee payroll is $47,000 a month before owner pay; adding a hired general manager reduces the residual available to the owner.
4
Booking-channel mix
15%-25% OTA fee
Moving suitable repeat guests from high-commission third-party channels to direct booking can lift gross margin without adding rooms.
5
Utility efficiency
3%-4% of sales
Energy and water are persistent hotel costs; efficiency matters most when savings remain real after maintenance and guest-comfort requirements.
6
Debt and reserve policy
$18K + 15%
The base case pays $18,000 of monthly debt service and retains 15% of positive pre-reserve profit for replacements and working capital.
Want to test occupancy, ADR, payroll, and cash reserves in a full forecast?
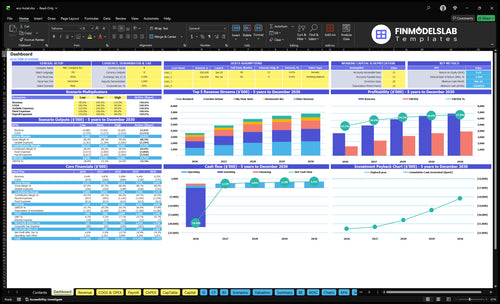
The Eco Hotel Startup Financial Model Template shows a business-specific dashboard for revenue, profitability, cash flow, payback, and scenario analysis. The dashboard is useful for pressure-testing whether occupancy and room rate actually support payroll, debt service, replacement capex, and owner cash rather than looking only at top-line room revenue.
How do room nights turn into about $2.10 million of annual revenue?
The base case starts with 14,600 available room nights a year: 40 rooms multiplied by 365 days. At 67% occupancy, that is about 9,782 sold room nights. Multiplying by a $195 ADR produces about $1.91 million of room revenue, and adding ancillary revenue equal to roughly 10% of rooms gets close to $2.10 million total revenue. The 67% occupancy and $195 ADR are deliberate planning assumptions, not national averages; the 2026 HVS market review reports 2025 national occupancy of 62.3% and ADR of $160.54. A boutique eco-friendly property has to earn its premium through location, product quality, reputation, and demand, not simply by labeling itself sustainable.
Base room-night math
40 rooms × 365 days = 14,600 available room nights.
67% occupancy = about 9,782 sold room nights.
9,782 × $195 ADR = about $1.91 million room revenue.
Ancillary sales lift the rounded total to about $2.10 million.
What revenue does not mean
Revenue is guest spend before hotel expenses.
Gross profit removes non-labor direct booking and guest costs.
Operating profit or EBITDA-style measures still come before debt, taxes, and owner distributions.
Cash safe to distribute comes after debt service, tax reserves, capex reserves, and working-capital needs.
Can the owner step away and keep the same income?
Not in this model. The base labor budget assumes the owner performs the general-manager role, while paid employees cover front desk, housekeeping, maintenance, and guest service. That choice is important because the BLS reported a $68,130 median annual wage for lodging managers in May 2024, before employer payroll taxes and benefits, and CBRE found hotel labor reached 32.4% of revenue in its 2023 U.S. sample. Hiring a manager at roughly the BLS median would lower this calculator's after-reserve owner income by about $42,000 a year before payroll burden, because the manager wage becomes an operating cost and the modeled tax and reinvestment reserves shrink with profit.
$263,520 owner income therefore mixes labor compensation and business return.
Track owner hours so a future manager replacement cost stays visible.
Manager-run case
Add a market-rate GM wage plus payroll burden to labor.
Do not also call that same amount an owner distribution.
Passive owner cash should be judged after replacement management is fully funded.
Owner distributions should remain flexible through weak occupancy periods.
How much revenue supports $180,000 of annual owner take-home?
Using the fixed calculator formula, the base cost structure needs about $161,417 of monthly revenue, or about $1.94 million per year, to support the $15,000 monthly target owner pay after the 24% tax reserve and 15% reinvestment reserve. The current base revenue of $175,000 per month clears that target by about $6,960 a month. For context, CBRE's trailing-twelve-month U.S. hotel sample showed a 34.7% GOP margin at June 2025; GOP is not the same as owner take-home because property-level debt, taxes, insurance, capital needs, and reserves still sit below it.
Target-pay bridge
Base operating costs: $111,000 per month.
Target take-home: $15,000 per month after modeled reserves.
Reserve multiplier: 61% after 24% tax and 15% reinvestment set-asides.
Required revenue: about $161,417 per month at 84% gross margin.
Why the target moves
A weaker direct-booking mix lowers gross margin and raises required revenue.
Higher payroll or insurance raises the fixed cash hurdle.
More debt service can erase distributions even when GOP looks healthy.
A larger capex reserve lowers current take-home but protects future solvency.
Key Takeaways
The modeled base owner income is $263,520 a year after tax and reinvestment reserves, not a guaranteed salary.
Occupancy and ADR set the revenue engine; payroll, distribution cost, fixed overhead, and debt decide how much survives.
The owner-operated case includes the economic value of the general-manager job, so passive ownership would produce less cash unless revenue rises.
Safe distributions come after debt service, taxes, working capital, repairs, and room-refresh reserves, even when accounting profit is positive.
What has to be paid before a hotel distribution is actually safe?
Accounting profit can contain noncash depreciation and may not match bank cash.
GOP or EBITDA-style operating profit comes before some ownership costs and financing.
Owner salary pays for work; owner distribution pays the owner as an equity holder.
This calculator uses one residual owner-income output instead of double counting salary and draw.
Protect distributable cash
Pay vendors, payroll, utilities, insurance, tax obligations, and debt first.
Retain cash for room refreshes, HVAC, laundry, water systems, and unexpected repairs.
EPA WaterSense recommends efficient fixtures, laundry equipment, kitchens, and leak control, but projects still need capital and maintenance.
Distribute only the cash remaining above the working-capital and reinvestment floor.
What do the low, base, and high owner-income cases look like?
The scenarios below keep the same 40-room scope but change occupancy, ADR, direct-cost efficiency, staffing, overhead, marketing, and reserves together. The low case reflects a softer 56% occupancy and $180 ADR environment; base uses 67% and $195; high uses 77% and $215 plus the extra staffing and overhead required to support more occupied rooms. The range is intentionally wider than national averages because market performance varies sharply by location, and the HVS 2026 hotel survey emphasizes that hotel performance and project economics are highly market-specific.
Owner income scenarios
Compare how occupancy, ADR, staffing, gross margin, debt, and reserve policy change owner cash.
Low, base, and high Eco-Friendly Hotel owner-income planning cases.
Scenario factor
Low CaseDownside
Base CasePlanning
High CaseUpside
Launch modelDemand posture
Soft demand with 56% occupancy and a $180 ADR.
Stabilized boutique case with 67% occupancy and a $195 ADR.
Owner income rangeAfter modeled tax and reinvestment reserves
$55,440
Annual owner income after modeled reserves.
$263,520
Annual owner income after modeled reserves.
$413,280
Annual owner income after modeled reserves.
Best fitPlanning use
Stress-test weak shoulder seasons, OTA-heavy mix, and thin distribution cushion.
Use for a stabilized owner-operated boutique hotel with disciplined pricing and staffing.
Use only after adding the labor and overhead needed to service stronger demand.
!
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
Which six drivers move Eco-Friendly Hotel owner income the most?
For this 40-room model, the six strongest levers are occupancy, ADR, labor productivity, booking-channel mix, utility efficiency, and debt plus reinvestment policy. They interact: pushing occupancy through an expensive third-party channel can raise revenue but weaken gross margin; cutting housekeeping too aggressively can protect payroll for a month but damage reviews and rate; and underfunding efficiency or room-refresh capex can make today's owner draw look better while making future cash flow worse.
1. Occupancy and room-night utilization
Fill profitable room nights, not just the calendar
Occupancy is the first lever because the hotel has 14,600 available room nights whether guests show up or not. The base assumption of 67% means about 9,782 sold nights; the low case at 56% is about 8,176, while 77% produces about 11,242. National 2025 occupancy was 62.3% according to the HVS summary of CoStar data, so the base case requires a property that outperforms the national average. Here's the quick math: at the base $195 ADR, moving from 62% to 67% occupancy adds roughly 730 sold room nights, or about $142,000 of room revenue before direct costs. But that upside is worth less if the marginal rooms come through expensive channels or require disproportionate housekeeping overtime.
Owner income improves when occupancy fills fixed-cost capacity without forcing a collapse in rate. Track occupancy by day of week and season because a 75% summer average can hide 40% winter months that still owe the same insurance, property taxes, base staffing, and debt service.
Track occupancy with contribution
Measure whether each additional occupied room leaves enough cash after channel, cleaning, amenity, and labor cost.
Occupancy by day and month
Sold room nights versus available room nights
Contribution per occupied room
Shoulder-season break-even occupancy
2. Average daily rate and revenue quality
Protect rate before chasing volume
The base $195 ADR is about 21% above the 2025 national $160.54 ADR reported in the HVS 2026 market review. That premium has to be supported by the property's location, design, reviews, amenities, and sustainable operating story. At about 9,782 base sold nights, every $5 of ADR is roughly $49,000 of annual room revenue before direct booking costs. A $10 discount used across the property therefore gives up roughly $98,000 a year unless it produces enough incremental room nights or ancillary spend to offset the rate cut.
Revenue quality matters more than a headline ADR. A $210 room sold through a 20% OTA commission can contribute less than a $195 room booked directly after modest acquisition cost. The owner should therefore review net ADR after channel cost, not just the price shown to the guest.
Track net ADR, not rack rate
Compare each channel and room type on the revenue that remains after booking cost and discounts.
ADR by channel and room type
Net ADR after commission
RevPAR and total revenue per available room
Discount depth versus occupancy pickup
3. Labor productivity and the owner's operating role
Price the owner's labor as real work
Hotel labor is structurally heavy because rooms turn every day and the property stays open overnight. CBRE's 2023 hotel sample put total labor at 32.4% of revenue, and its 2025 cost review reported compensation up another 4.8% in 2024. The model sets employee labor at $47,000 a month, or about 27% of base revenue, because the owner fills the general-manager role. Add the BLS $68,130 lodging-manager median wage and the payroll ratio moves closer to the industry benchmark before employer burden.
This distinction separates owner salary economics from owner distributions. The owner can reasonably view part of the $263,520 annual output as pay for running the hotel, but a passive investor cannot. If the owner wants to step away, the replacement manager belongs in laborCost first; only the residual after that expense is a true ownership return.
Track labor per occupied room
Schedule housekeeping, front desk, breakfast, and maintenance against forecast occupancy rather than fixed habit.
Labor dollars as % of revenue
Labor dollars per occupied room
Rooms cleaned per paid housekeeping hour
Owner hours logged separately from staff hours
4. Booking-channel mix and acquisition cost
Shift repeat demand toward lower-cost direct channels
Independent hotels need OTAs for reach, but the commission can be material. SiteMinder says OTA commissions typically run 15% to 25% per booking and reports U.S. direct-booking share around 40% in its 2026 traveler data. The base gross-margin assumption of 84% therefore assumes a blended channel mix rather than all-direct booking. For a simple sensitivity, moving $200,000 of annual room revenue from a 20% OTA commission to a direct channel with a 7% blended acquisition cost improves contribution by about $26,000 before any additional software or loyalty expense.
Do not eliminate OTAs blindly; occupancy can fall when visibility falls. The financial goal is to use third-party demand where it is incremental and turn repeat guests into direct customers when service, consent, and rate strategy support it. Keep OTA commission in direct costs and paid search or local promotion in marketing so the model does not count acquisition twice.
Track cost of sale by channel
Compare gross room revenue with the cash kept after commission, discounts, processing, and direct marketing.
Do not treat a solar array, heat pump, laundry retrofit, or low-flow fixture as free profit. Track installed cost, maintenance, rebates if any, utility savings, and payback. The reinvestment reserve exists partly so the property can fund this work without draining working capital.
Benchmark resource cost per occupied room
Normalize utilities for occupancy and weather so a low bill caused by weak demand is not mistaken for efficiency.
Electricity, gas, water, and sewer per occupied room
Energy use by square foot
Laundry water per occupied room
Verified savings versus project cost
6. Debt service, insurance, and reinvestment discipline
Protect cash after operating profit
A hotel can post healthy GOP and still have thin owner distributions because ownership costs sit below operating profit. The base model pays $18,000 a month, or $216,000 a year, of debt service before owner income. It then retains 15% of positive pre-reserve profit for reinvestment and 24% for taxes. That is especially important when CBRE's 2024 U.S. survey showed insurance premiums rising 17.4% and property taxes 4.3%. A surprise roof, HVAC, hot-water, elevator, or room-refresh project can consume months of distributions if the reserve is too thin.
The low case shows the danger: $1.62 million of annual revenue still produces only $55,440 of after-reserve owner income because fixed costs and debt do not fall in proportion to occupancy. The policy decision is not to maximize this month's draw. It is to distribute only after the next 13 weeks of payroll, debt, taxes, known maintenance, and replacement projects are funded.
Track cash coverage before distributions
Use a rolling cash forecast and an explicit minimum reserve floor before authorizing owner draws.
Debt-service coverage from operating cash
Cash weeks on hand
Annual room-refresh and major-equipment plan
Owner distributions versus retained cash
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.