What Can an Owner Expect to Take Home from an E-Bike Rental?
A U.S. owner-operated E-Bike Rental shop can realistically produce about $137,000 a year of modeled owner income in a solid base case, with a practical low-to-high planning range of roughly $38,000 to $215,000. The base case here assumes about $48,000 of monthly rental revenue, an 88% gross margin after non-labor direct rental costs, $25,500 a month of payroll, overhead, marketing, and debt service, then a 22% tax reserve and 10% reinvestment reserve. The owner works full time as general manager and fleet operator; owner labor is not duplicated in payroll. It is not a guaranteed salary or passive distribution and excludes the owner's final personal tax liability and benefits.
Owner income$137KNet margin24%Revenue for target pay$488KBusiness difficultyHard
How much revenue does an E-Bike Rental shop need to pay its owner?
In this base model, the shop needs about $40,675 a month, or $488,100 annualized, to support a $7,000 monthly owner-income target after the modeled reserves. The base operating month is stronger at $48,000. That is consistent with a roughly 40-bike tourism-oriented fleet producing about 565 paid bike-days per month at an $85 realized rental-day yield. Posted U.S. prices vary materially: San Diego Electric Bike lists $65 for four hours and $90 for 24 hours, while New York Bike Rentals lists $80.99 online for an eight-hour e-bike rental. The $85 yield is therefore a planning average, not a national price benchmark.
At $48,000 of monthly sales and an 88% gross margin, the model produces $42,240 of gross profit. Hired labor, fixed overhead, marketing, and debt service total $25,500, leaving $16,740 before owner reserves. A 22% tax reserve and 10% reinvestment reserve hold back $5,357, leaving $11,383 of modeled monthly owner income. The strict operating break-even point is lower, about $28,977 a month of revenue before any owner take-home, because $25,500 divided by 88% is the sales level that merely covers the modeled operating-cost stack.
Owner income calculator
Test how rental revenue, margin, staffing, overhead, debt, and reserves change owner take-home.
i
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
1
Paid fleet utilization
14.1 days/bike/mo
Filling one more paid day across a 40-bike fleet adds revenue without buying another bike, so utilization is the strongest first lever.
2
Realized rental yield
$85/bike-day
Discounts, half-day mix, add-ons, and channel commissions determine what the shop actually keeps per paid bike-day.
3
Fleet uptime and direct cost
88% gross margin
Brake, tire, battery, cleaning, payment, and damage leakage decide how much revenue survives before payroll and rent.
4
Labor and owner coverage
$12K/mo hired labor
An owner who covers dispatch and management can protect cash, but that savings is compensation for work, not passive profit.
5
Seasonality and acquisition
$2.5K/mo marketing
Tourist demand can bunch into weekends and warm months, so paid acquisition must be judged on contribution, not bookings alone.
6
Financing and fleet reserve
$3K debt + 10% reserve
Debt service is paid before owner reserves, while retained cash funds batteries, replacement bikes, and the next slow period.
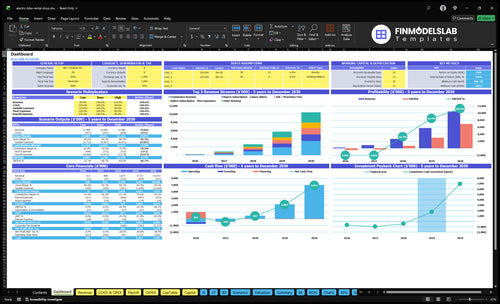
Want to test the rental assumptions in a full forecast?
The Electric Bike Rental Shop Financial Model Template in Excel includes a dashboard view for testing revenue, unit economics, payroll, capex, cash flow, and low/base/high assumptions. For a physical rental shop, use the screenshot as a planning interface: replace platform-style assumptions with your own fleet count, paid rental days, realized rate, staffing, maintenance, financing, and reserve policy.
What sets the revenue ceiling for an E-Bike Rental shop?
Low: 30 bikes × 12.5 paid days × $80 = about $30,000 per month.
Base: 40 bikes × about 14.1 paid days × $85 = about $48,000 per month.
High: 50 bikes × 16 paid days × $90 = $72,000 per month.
Measure paid bike-days, not reservations, because cancellations and weather do not create collected revenue.
What this estimate hides
A $90 list price can become an $85 realized yield after discounts, channel mix, and shorter rentals.
Peak Saturdays can sell out while Tuesday utilization remains weak; monthly averages can hide that imbalance.
Key Takeaways
The base case produces $136,596 of annual owner income only after a $5,357 monthly tax-and-reinvestment reserve.
A 40-bike fleet needs roughly 14 paid bike-days per bike per month at about $85 realized yield to support the modeled $48,000 revenue month.
Owner labor is economically real even when it is not shown in hired payroll; manager-run economics are lower unless revenue rises.
Debt, battery replacement, maintenance, and slow-season cash should be funded before distributions are treated as safe.
Can an E-Bike Rental business run without the owner?
Yes, but the distribution pool usually falls unless the shop has enough volume to fund management coverage. The base case is intentionally owner-operated: the owner handles general management, vendor decisions, scheduling, and some frontline coverage, while $12,000 a month funds hired labor. National May 2025 BLS wage data reports a $19.86 median hourly wage for counter and rental clerks. For technical work, the May 2023 detailed BLS bicycle-repairer data showed a $18.42 national median hourly wage. Actual local wages can be materially higher, and payroll taxes, workers' compensation, overtime, and scheduling inefficiency sit on top of wage rates.
Owner-operated economics
The owner covers management rather than adding a separate manager wage to the $12,000 base payroll.
Owner income is therefore compensation for both capital risk and substantial labor performed in the shop.
If the owner covers another 30 to 40 frontline hours weekly, hired payroll may fall, but the apparent margin is partly purchased with the owner's time.
Manager-run economics
An illustrative extra $5,000 monthly management cost would reduce positive pre-reserve profit by the same $5,000.
With the base 32% combined reserve rate, that $5,000 cost cuts modeled owner cash by about $3,400 a month, or $40,800 a year.
How much cash should stay in the business before the owner distributes profit?
A prudent operator should separate accounting profit from cash that is actually safe to withdraw. In the base month, $16,740 remains after gross profit and operating costs, but the model deliberately keeps $5,357 for tax and reinvestment, leaving $11,383. On top of that formula, the owner should maintain a location-specific operating cash floor. A practical planning rule for this model is roughly 1.5 to 2.5 months of the $25,500 operating-cost stack, or about $38,000 to $64,000, before treating extra cash as freely distributable. That range is a reasoned reserve policy, not an industry standard.
Rent, utilities, insurance, software, licenses, storage, and administration.
Marketing commitments and the full monthly debt payment.
Tax reserve, fleet-replacement reserve, and the minimum operating cash floor.
Do not mix the profit labels
Revenue is rental sales before costs.
Gross profit is revenue after non-labor direct costs in this model.
Operating profit before reserves is gross profit after hired labor, fixed overhead, marketing, and debt cash service here; it is a planning cash metric, not GAAP EBITDA.
Owner income is the residual after modeled reserves. Salary versus distribution depends on entity structure, tax rules, and the owner's actual work.
What do low, base, and high E-Bike Rental owner-income cases look like?
The same rental concept can produce about $38,016, $136,596, or $215,040 a year of modeled owner income after reserves depending on utilization, yield, margin, staffing, overhead, financing, and reserve policy. Payment costs also scale with sales; for context, Stripe's standard U.S. online card pricing is 2.9% plus $0.30 per successful domestic-card transaction, one reason this model keeps payment processing inside direct cost rather than fixed overhead.
Owner income scenarios
Low, base, and high cases tie fleet utilization, realized yield, payroll, overhead, debt, and reserves to owner income.
Low, base, and high E-Bike Rental planning cases.
Scenario
Low CaseDownside
Base CaseOwner-operated
High CaseStrong demand
Launch modelFleet and demand stance
Lean 30-bike fleet with softer weekday demand and owner-heavy coverage.
About 40 bikes with steady tourism demand and the owner acting as general manager.
About 50 bikes, longer staffed hours, stronger partnerships, and higher paid-day utilization.
Typical setupRevenue and margin
$30,000 monthly revenue; 84% gross margin; about 12.5 paid days per bike at $80 yield.
$48,000 monthly revenue; 88% gross margin; about 14.1 paid days per bike at $85 yield.
$72,000 monthly revenue; 90% gross margin; 16 paid days per bike at $90 yield.
Cost driversMonthly operating stack
$9,000 labor
$7,500 overhead
$1,800 marketing
$2,500 debt
20% tax + 8% reinvestment
$12,000 labor
$8,000 overhead
$2,500 marketing
$3,000 debt
22% tax + 10% reinvestment
$18,000 labor
$10,500 overhead
$3,800 marketing
$4,500 debt
24% tax + 12% reinvestment
Owner income rangeAfter modeled tax + reinvestment reserves
$38,016
Annual owner income after modeled reserves.
$136,596
Annual owner income after modeled reserves.
$215,040
Annual owner income after modeled reserves.
Best fitPlanning use
Use to test a slow season, weak launch, or a smaller destination market.
Use as the primary owner-operated plan in a viable tourism or recreation market.
Use as an upside case only if demand, staffing, charging, storage, and maintenance capacity all scale together.
i
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
Which six drivers change E-Bike Rental owner income most?
The six strongest levers are paid fleet utilization, realized rental yield, fleet uptime and direct cost, labor and owner coverage, seasonality and customer acquisition, and financing plus fleet reserves. They interact. Higher utilization can justify more staff; a higher rate can reduce demand; more bikes can expand revenue but also increase debt, storage, charging, maintenance, and replacement cash. The goal is to increase cash left after all six are funded.
1. Paid fleet utilization
Turn idle bike-days into paid bike-days before adding fleet
Utilization is the cleanest revenue lever because a bike already purchased, insured, stored, and charged earns nothing while idle. The base case assumes about 565 paid bike-days per month across 40 bikes, or roughly 14.1 paid days per bike. At the modeled $85 realized yield, one additional paid day per bike adds 40 × $85 = $3,400 of monthly revenue. At an 88% gross margin, that is $2,992 of additional gross profit before incremental staffing or marketing. If no new fixed cost is required, the 32% combined base reserves leave about $2,035 of extra monthly owner income.
Weather, tourism seasonality, and weekday softness mean 47% calendar utilization will not fit every market. Posted coastal pricing such as the $90 24-hour San Diego rate shows revenue potential per occupied day, but local booking data must prove the utilization.
Track utilization by day and bike class
Use paid bike-days divided by available bike-days, then split weekends from weekdays and standard models from premium models.
Paid bike-days per available bike.
Weekend versus weekday utilization.
Lost bookings from sell-outs.
Idle bikes older than 30 days.
Add fleet only when repeated sell-outs are costing more contribution than the next bike's financing, maintenance, and reserve burden.
2. Realized rental yield
Price the mix, not just the headline day rate
Rental yield is the collected rental revenue per paid bike-day after discounts and duration mix, before operating expenses. The base uses $85 because a shop may advertise $90 or more for a full day yet sell half-day rentals, online discounts, group rates, or partner bookings. Current U.S. pricing spans a broad range; New York Bike Rentals shows $24.99 for one hour and $80.99 for an eight-hour online rental. That makes duration mix as important as the posted full-day rate.
Here's the quick math: at 565 paid bike-days, raising realized yield by only $5 adds $2,825 of monthly revenue. At 88% gross margin, that adds about $2,486 before other costs. After the modeled 32% reserves, roughly $1,690 could reach owner income if volume and staffing are unchanged. A $5 increase only works if lost volume does not erase the gain.
Track yield after discounts and channel costs
Use collected rental revenue divided by paid bike-days and reconcile it to your reservation system weekly.
Realized revenue per paid bike-day.
Discount dollars as a percent of list price.
Partner or booking-channel commissions.
Add-on revenue per rental.
Test small price changes on high-demand periods first, when the risk of losing occupancy is lowest.
3. Fleet uptime and direct cost
Protect both availability and the 88% planning margin
The model's 88% gross margin is a constructed planning assumption: roughly 12% of revenue is allowed for payment fees, ordinary repair parts, charging, cleaning consumables, and routine damage leakage, while all payroll remains separate. Card processing alone can absorb about three percentage points; Stripe lists 2.9% plus $0.30 for a successful domestic card transaction. The remaining direct-cost allowance must absorb rental wear, so maintenance discipline matters.
Each one percentage point of gross margin on $48,000 of monthly sales equals $480 of pre-reserve profit. With the base reserves, that is about $326 a month, or $3,917 a year, of owner-income sensitivity. One bike unavailable for seven rentable days at $85 can lose up to $595 of revenue unless another bike absorbs the demand. Safety cannot be traded for uptime; CPSC specifically calls out UL 2849 for e-bike electrical systems.
Track repair cost and downtime per bike
Give every bike an asset record so you can distinguish a profitable workhorse from a bike that consumes labor and parts.
Maintenance parts per paid bike-day.
Downtime days by cause.
Battery health and charge-cycle issues.
Retire or rotate problem bikes before repeated downtime becomes a hidden margin leak.
4. Labor and owner coverage
Separate owner labor from true passive return
The base case includes $12,000 per month of hired labor but no owner wage inside that line. The calculator defines owner take-home as the residual after operating costs and reserves, so an owner wage in payroll would double count compensation. The owner manages schedules, vendors, partnerships, and some frontline work.
Market wages show why this matters. The May 2025 BLS national data puts counter and rental clerks at a $19.86 median hourly wage, before employer payroll burden. If the owner replaces a $5,000 monthly manager role, the business may show about $3,400 more monthly owner cash after the base reserve percentages. But that $40,800 annual difference is payment for real work and responsibility. A passive-owner view should subtract replacement management cost.
Track paid labor hours and owner hours separately
A profitable shop should know whether margin comes from efficient staffing or from the owner silently working unpaid shifts.
Hired labor dollars per rental day.
Owner hours by management and frontline work.
Rentals handled per labor hour.
Overtime and peak-period staffing premiums.
Build a manager-run shadow P&L each quarter even if the owner has no plan to step away yet.
5. Seasonality and customer acquisition
Buy contribution, not vanity bookings
The base spends $2,500 per month on marketing and partnerships, a planning assumption that varies by destination, season, partnerships, and repeat business. The test is whether marketing adds enough gross profit to pay for itself. Suppose a $2,500 campaign creates 40 incremental paid bike-days at $85. Revenue rises by $3,400 and gross profit by about $2,992 at the 88% margin, leaving only $492 before reserves and any added labor. After the base reserve percentages, the owner keeps only about $335. That channel works, but barely.
Seasonality changes channel value: a partnership that fills idle shoulder-season weekdays can beat paid demand for already sold-out Saturdays. Shift spend toward spare fleet and labor capacity.
Track acquisition by contribution and time slot
Attach a source to each booking, then compare revenue, direct cost, and capacity use rather than cost per click.
Acquisition cost per completed rental.
Gross profit per booking source.
Weekday and shoulder-season fill rate.
Repeat and referral share of bookings.
Cut channels that produce low-yield peak bookings while ignoring cheaper demand that could fill idle fleet.
6. Financing and fleet reserve
Fund the bikes twice: purchase first, replacement later
E-bikes are revenue-producing assets, but they wear out and tie up cash. Current consumer-market reference points show the scale of the asset base: Trek lists several Verve+ electric hybrids around $2,000 to $3,500, before commercial-use accessories and spares. Forty bikes at even $2,000 each represent $80,000 of bicycle hardware, so a rental shop that finances fleet and fit-out can easily carry a meaningful monthly payment.
The base uses $3,000 monthly debt service and retains 10% of positive pre-reserve profit for reinvestment, or $1,674 in the base month. Debt comes first: reducing debt service by $1,000 raises pre-reserve profit by $1,000 and, with the 32% combined reserve rate, raises modeled owner income by about $680 a month. Cutting the reinvestment reserve merely shifts battery, replacement-bike, and slow-season risk into the future.
Track debt coverage and replacement funding together
A shop can be profitable on paper and still become cash-starved if owner draws consume money needed for fleet renewal.
Debt service as a percent of monthly gross profit.
Replacement reserve dollars per paid bike-day.
Cash balance after scheduled debt and reserve transfers.
Distribute only cash above taxes, debt, planned fleet renewal, and the minimum operating cash floor.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
E-Bike Rental Bundle
Choosing a selection results in a full page refresh.