What Revenue Supports Owner Pay in an Elevator Maintenance Business?
Elevator Maintenance Bundle
An owner-operated U.S. elevator maintenance company can realistically produce about $162,000 a year in owner income in a solid base case built on roughly $900,000 of annual revenue. This model assumes recurring preventive-maintenance contracts on about 80 units, additional repair and callback work, an 88% gross margin before payroll, and the owner still handling sales, operations, and some technical escalation. It pays hired labor, vehicles and shop overhead, marketing, and $2,500 a month of debt service before reserving 24% of positive operating profit for taxes and 10% for reinvestment. The $162,360 result is residual owner cash after those modeled reserves, not guaranteed salary, EBITDA, or a promise that the full amount is distributable under every entity or tax structure. A slower route base can fall near $57,000 a year, while a stronger regional operation can approach $271,000 if pricing, route density, labor capacity, collections, and repair mix scale together.
Owner income$162KNet margin18%Revenue for target pay$868KBusiness difficultyHard
Owner income calculator
Estimate owner take-home from service revenue, direct-cost margin, payroll, overhead, debt, and reserve policy.
i
Planning note: The model treats owner pay as residual cash after operating costs and modeled reserves. It does not put the owner's own wage inside labor cost, so an S corporation or other structure that requires payroll compensation should reclassify part of owner economics rather than count salary and distribution twice.
1
Contract value and unit count
80 units × $650/mo
The base plan gets about $52,000 monthly recurring revenue before repair work. Pricing and the number of maintained units set the revenue floor.
2
Technician utilization
$109.8K mean wage
High skilled-labor cost makes route density critical. Empty drive time, overtime, and poor dispatch can erase the margin from several contracts.
3
Parts and callback control
12% direct-cost plan
The base case leaves 88% before payroll. Unpriced parts, warranty callbacks, and repeat visits can quickly push that planning margin down.
4
Repair and premium work
$23K/mo add-on revenue
Repairs, testing, and callbacks fill the gap between recurring contract revenue and the $75,000 monthly base sales target.
5
Retention and collections
10-unit loss = $6.5K/mo
A single property-manager loss can remove meaningful recurring revenue, while slow receivables force payroll and parts to be funded from cash.
6
Overhead, debt, and reserves
$16.5K/mo before labor
Base fixed overhead, marketing, and debt service consume $16,500 monthly before payroll, taxes, reinvestment, or any owner draw.
Want to test route, staffing, and reserve assumptions in a full forecast?
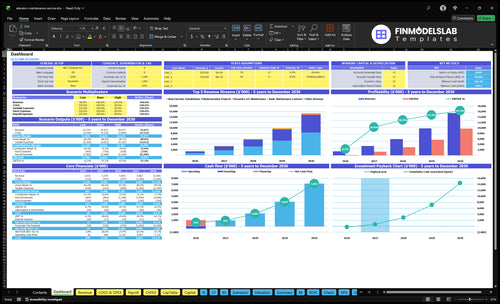
The Elevator Maintenance Service Startup Financial Model Template provides a dashboard for testing service-contract growth, payroll, parts and operating costs, cash flow, financing, and scenario changes. The preview is most useful for checking whether recurring maintenance revenue grows fast enough to support technician hiring without creating a cash shortfall.
How does an elevator maintenance company reach $900K in annual revenue?
The most defensible path is a recurring route base first, then repair, testing, emergency, and excluded-part work on top. A 2022 Miami-Dade County audit reported average maintenance pricing that ranged from $361.03 to $2,563.64 per elevator per month across a large public contract, or $4,332.36 to $30,763.68 annually per unit; that spread shows how strongly equipment type, scope, age, and service level change contract value. See the Miami-Dade contract audit. Because that is an older public-fleet benchmark rather than a current small-contractor price list, this article uses a conservative planning average of $650 per maintained unit per month for the base case.
Base revenue build
80 maintained elevators × $650 per month = about $52,000 recurring monthly revenue.
Repair, testing, callback, and other non-contract work contributes about $23,000 monthly.
Total base revenue is $75,000 monthly, or $900,000 annually.
At 88% gross margin before payroll, that produces $66,000 of monthly gross profit to pay labor and overhead.
Why scope matters more than a headline price
A 2025 Augusta, Georgia elevator-maintenance bid separated certain replacement parts and labor from routine maintenance and allowed parts at documented market cost with markup capped at 15%; review the Augusta bid specification.
Full-maintenance contracts can carry more parts and callback risk than examination-and-lubrication contracts.
Emergency response windows, testing obligations, travel radius, and equipment age can make two $650 contracts economically very different.
Quote the service scope and exclusions before using price per elevator as a profitability metric.
What does it cost to support that revenue?
Skilled labor is the largest controllable expense, and it is unusually expensive in this trade. The BLS May 2025 national wage table reports a mean annual wage of $109,820, or $52.80 per hour, for elevator and escalator installers and repairers. BLS also describes the work as full-time, sometimes on-call, and notes that most states require workers to be licensed; the BLS Occupational Outlook Handbook is a useful check on how labor availability and licensing affect staffing.
Base monthly cost stack
$29,000 hired payroll, excluding the owner's own compensation.
$11,000 fixed overhead for vehicles, insurance, shop or office, software, phones, licensing, and administration.
$3,000 marketing and sales support, kept separate so acquisition cost is visible.
$2,500 debt service for financed vans, tools, acquisition costs, or working capital.
Total operating costs before owner reserves: $45,500 per month.
Costs that are easy to underestimate
A U.S. Department of Labor apprenticeship study reported a 2022 median starting wage of $23.51 per hour for elevator apprentices, showing that even training-pipeline labor is material; see the DOL apprenticeship report.
The IRS 2026 business mileage rate is 72.5 cents per mile, a useful yardstick for checking whether van costs are being understated.
Safety procedures are not optional overhead. OSHA's lockout/tagout guidance explains controls required when servicing equipment that can unexpectedly energize.
Code familiarity and documentation matter because ASME A17.1 covers maintenance, testing, alteration, and repair as well as installation.
How much revenue supports a $144K owner pay target?
In the base model, operating break-even before owner reserves is about $51,705 a month, or roughly $620,000 a year: $45,500 of operating costs divided by an 88% gross margin. To support a $12,000 monthly owner target after reserves, the fixed calculator formula raises required revenue to $72,366 a month, or $868,392 annually. The base plan's $75,000 monthly revenue therefore has only about a $2,634 monthly revenue cushion over the target-pay threshold, even though the displayed owner-income gap is a positive $1,530 after reserves.
What moves the threshold
If gross margin falls from 88% to 84% with the same operating costs and reserve policy, target-pay revenue rises from $72,366 to about $75,812 per month.
An extra $5,000 of monthly payroll raises operating break-even by about $5,682 at an 88% gross margin before considering any growth in owner target pay.
A $6,500 monthly contract loss from ten $650 units can push the base case below its current target-pay revenue requirement.
Target pay should be treated as a planning goal, not another expense line, or the owner will double-count compensation.
Debt can turn accounting profit into weak cash flow
The model includes $2,500 of monthly principal-and-interest cash service before owner reserves.
The SBA 7(a) program states that interest rates are negotiated subject to maximums tied to loan size, so the same van, acquisition, or working-capital balance can produce very different monthly cash burdens.
Principal repayment is cash leaving the business even when accounting treatment differs from an operating expense.
Test owner income after debt service, not just EBITDA, before deciding what is safe to distribute.
Key Takeaways
A $900,000 annual elevator-maintenance business can support about $162,360 of modeled owner income only if payroll, direct costs, overhead, and reserve assumptions hold together.
Recurring unit count is valuable, but route density and technician productivity determine whether added contracts actually improve owner cash.
The base operating break-even is about $620,000 annual revenue, while the modeled $144,000 owner-pay target needs about $868,000.
Owner salary, accounting profit, and distributions are different; the entity structure can change how residual cash should be paid and taxed.
How should the owner separate salary, profit, and distributions?
Use five separate numbers. Revenue is customer billings. Gross profit is revenue after non-labor direct costs in this model. Operating profit before reserves is gross profit after hired payroll, fixed overhead, marketing, and debt service. Owner salary is compensation for work performed when the chosen entity requires or uses payroll. Owner distribution is cash transferred because of ownership after the company has retained enough for taxes, fleet, tools, parts float, and working capital. The calculator's $162,360 annual owner-income output is an economic residual after modeled reserves; it is not automatically a tax-law distribution.
Avoid salary and draw double counting
The calculator excludes the owner's own wage from the $29,000 monthly labor line.
If the owner is an S corporation shareholder-employee, the IRS says reasonable compensation for services must be paid before non-wage distributions; see IRS reasonable-compensation guidance.
That means some of the modeled owner-income pool may be reclassified into W-2 wages rather than added on top of it.
Entity-specific payroll tax, withholding, and personal tax results require professional advice and can change cash actually kept.
What must be paid before cash is safe
Technician payroll and on-call obligations.
Parts purchases and warranty or callback exposure.
Vehicle, insurance, software, licensing, and shop overhead.
Debt principal and interest due in cash.
Tax and reinvestment reserves plus a working-capital buffer; the IRS paying-yourself guidance explains that compensation mechanics depend on business structure.
What do low, base, and high owner-income cases look like?
The modeled range runs from $56,700 to $270,648 of annual owner income after the stated tax and reinvestment reserves. Those outcomes are not produced by changing revenue alone: technician payroll, overhead, marketing, debt service, margin, and reserve rates all move with scale. The low case is owner-field-heavy and fragile; the high case supports more hired capacity but also carries much more payroll and working-capital exposure.
Low, base, and high cases
Compare route scale, staffing, cost pressure, and owner cash using the same presets as the owner-income calculator.
Elevator maintenance planning scenarios and owner income after modeled reserves.
Scenario factor
Low CaseLean
Base CasePlanned
High CaseScale
Launch modelRevenue engine
About 55 recurring units
$45,000 monthly revenue
About 80 recurring units
$75,000 monthly revenue
About 120 recurring units
$120,000 monthly revenue
Typical setupOwner and team
Owner covers service and sales
$18,000 monthly hired payroll
Owner remains operationally active
$29,000 monthly hired payroll
More delegated field capacity
$47,000 monthly hired payroll
Cost driversMonthly presets
85% gross margin
$13,500 overhead, marketing, and debt
88% gross margin
$16,500 overhead, marketing, and debt
89% gross margin
$24,000 overhead, marketing, and debt
Owner income rangeAfter modeled tax + reinvestment reserves
$56,700
$162,360
$270,648
Best fitOperating posture
Dense service radius
Low fixed-cost posture
Balanced recurring and repair revenue
Owner-led sales and control
More management capacity
Higher payroll and cash buffer
i
Planning note: Scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
Which six drivers move elevator maintenance owner income most?
Owner income is most sensitive to the relationship between contract revenue and skilled labor capacity. A route can look profitable by unit count yet produce weak cash if technicians spend too much time driving, callbacks are unpriced, parts are absorbed, or customers pay slowly. The six drivers below use the same assumptions as the calculator so each operating decision can be translated into owner cash.
1. Contract value and maintained-unit count
Build the recurring floor before adding payroll
The base case assumes 80 units averaging $650 per month, or $52,000 of recurring maintenance revenue. That price sits inside the much wider public-contract range reported by the Miami-Dade audit, but it should be treated as a planning assumption because equipment mix and contract scope vary sharply. Here's the quick math: adding ten similar elevators adds $6,500 monthly revenue. At an 88% gross margin, that is $5,720 of gross profit before incremental payroll. If the existing route can absorb the work and the 34% combined reserve rate still applies, the model converts about $3,775 of that amount into monthly owner cash, or roughly $45,300 annually. If those ten units trigger a new hire, the gain can disappear.
Track contract contribution by unit
Do not stop at contract price. Measure what each property consumes.
Monthly contract value per elevator.
Scheduled visits and actual hours per unit.
Callbacks and included-part cost by property.
Travel minutes between stops.
2. Technician utilization and route density
Make each skilled hour cover enough revenue
Labor is expensive enough that dispatch quality becomes a financial metric. The 2025 BLS mean of $109,820 a year equals about $9,152 of wages per month before employer payroll burden, benefits, overtime, van cost, or training. At the base 88% gross margin, the wage alone needs roughly $10,400 of additional monthly revenue just to cover that technician cost before those other expenses. A geographically scattered book can therefore grow revenue while shrinking owner income. The owner should phase hiring behind signed route volume, but not so late that overtime and service delays damage retention.
Track productive hours, not headcount
A good technician schedule minimizes non-billable movement without compromising required service.
Revenue per field technician.
Billable or scheduled service hours divided by paid hours.
Drive hours per route day.
Overtime and after-hours callback hours.
3. Parts, callbacks, and direct-cost discipline
Protect the 88% pre-payroll gross margin
The calculator's gross margin is deliberately defined before payroll. In the base case, 12% of revenue covers parts, consumables, subcontracted specialty items, payment friction, and other non-labor direct costs. Public procurement documents show why exclusions matter: the Augusta maintenance specification allows certain replacement parts outside the maintenance price and caps the permitted parts markup at 15%. On $10,000 of eligible pass-through parts, a 15% markup is only $1,500 of gross profit before ordering, warranty, freight, and handling effort. Absorbing the same parts inside a fixed contract can reverse the economics.
Tag every callback and material issue
The fastest margin leak is work that cannot be invoiced and is not budgeted into the contract.
Parts cost as a percentage of revenue.
Unbilled callback hours by root cause.
Warranty versus customer-billable work.
Quoted markup versus realized markup after freight.
4. Repair, testing, and premium-response mix
Use add-on work to lift revenue without breaking the route
The base model needs about $23,000 monthly beyond the $52,000 recurring-maintenance floor. That additional revenue can come from excluded repairs, testing, after-hours response, modernization support, and billable callbacks. A Wellesley, Massachusetts public solicitation separately budgets standard labor, premium labor, and materials for unscheduled work; see the Wellesley elevator service project manual. If the base company raises its add-on revenue by 10%, or $2,300 per month, while existing staff can absorb the work, the model produces about $1,336 more monthly owner cash after the 34% combined reserves.
Separate recurring and event-driven revenue
That separation shows whether growth is durable or dependent on unusually heavy repair months.
Recurring contract revenue percentage.
Repair revenue per maintained unit.
Premium-response hours and realization rate.
Quoted work won versus quoted work lost.
5. Retention, concentration, and collections
Protect recurring cash, not just annual contract value
Ten base-case units represent $6,500 of monthly recurring revenue. If one property manager controls those ten units and the account is lost, the revenue hit is immediate while technician wages, van payments, and insurance may not fall at all. With fixed costs unchanged, that loss can reduce modeled monthly owner cash by roughly $3,775 after the 88% gross margin and 34% reserves. Collections are equally important: at $75,000 monthly sales, moving average receivables from roughly 30 days to 60 days can tie up about another $75,000 of cash even though the income statement still shows revenue. That is why a profitable company can still struggle to make payroll.
Track renewal risk and days to cash
Owner distributions should shrink before payroll or suppliers are financed with credit cards or emergency borrowing.
Revenue concentration by property manager.
Unit retention and contract renewal rate.
Accounts receivable days and past-due balances.
Cash reserve measured in payroll plus overhead months.
6. Overhead, debt, and reserve discipline
Convert accounting profit into cash that can actually leave the company
Base fixed overhead, marketing, and debt service total $16,500 a month before the $29,000 hired payroll. Within this calculator, every $1,000 of recurring cost removed without harming service adds about $660 to monthly owner income after the 24% tax and 10% reinvestment reserves, or $7,920 a year. Vehicle control matters: at the 2026 IRS business mileage yardstick of 72.5 cents per mile, 2,500 business miles represent $1,812.50 of monthly vehicle-cost equivalent. Debt matters too. Reducing the modeled $2,500 monthly debt payment by $1,000 increases modeled owner cash by about $660, but only after the business still retains enough cash for vans, tools, safety equipment, training, and parts float.
Set a distribution gate
Pay the owner from surplus cash after operating obligations and policy reserves, not from the bank balance on a strong collection day.
Monthly fixed overhead as a percentage of revenue.
Debt-service coverage using actual cash payments.
Reinvestment reserve balance versus planned fleet and tool purchases.
Cash available after target owner pay and upcoming payroll.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.