How Profitable Can a Fabric Store Be for Its Owner?
Fabric Store Bundle
An owner-operated U.S. fabric store can produce about $101,400 a year in modeled owner income in this base case, or $8,450 a month after a 25% tax reserve and 10% reinvestment reserve. The model assumes $100,000 in monthly sales, a 48% gross margin, $19,000 of non-owner payroll, $11,000 of fixed overhead, $3,000 of marketing, and $2,000 of debt service. The low case produces no safe owner distribution; the high case reaches about $207,900 a year with higher staffing and overhead. Scope is an independent specialty retailer selling fabric, sewing supplies, patterns, and notions, consistent with the 2022 U.S. NAICS definition for sewing, needlework, and piece-goods retailers. Manufacturing and upholstery repair are excluded. Owner income is a planning cash output, not guaranteed salary, GAAP net income, or personal after-tax income.
Owner income$101KNet margin8%Revenue for target pay$1.18MBusiness difficultyHard
What does $100,000 a month in fabric-store sales leave for the owner?
In the base case, $100,000 of monthly revenue leaves $48,000 of gross profit after direct merchandise and selling costs. Subtract $35,000 for employee payroll, fixed overhead, marketing, and debt service: profit before reserves is $13,000. Holding back $3,250 for taxes and $1,300 for reinvestment leaves $8,450 a month, or $101,400 a year. As an adjacent benchmark, JOANN reported a 46.9% fiscal 2023 gross margin, with merchandise, freight, shrink, and clearance in cost of sales. Card acceptance fees sat in SG&A, so the 48% base margin here is a reasoned independent-store assumption, not a copied chain figure. See the JOANN fiscal 2023 annual report.
Revenue is the top line; gross profit is revenue after direct product costs. Operating profit or EBITDA-like measures can still exclude debt principal, tax cash, capital spending, and working-capital needs. Accounting profit also differs from cash when inventory is purchased before it sells. Owner salary compensates work; a distribution transfers residual business cash. This calculator excludes owner compensation from employee labor and treats owner take-home as the residual after costs and modeled reserves, preventing double counting.
Owner income calculator
Estimate owner take-home and the target-pay gap from store revenue, margin, staffing, overhead, debt, and reserves.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
1
Transaction volume + ticket
~74/day × $52
The base planning case reaches about $100,000 a month by combining steady daily transactions with a $52 average ticket across yardage and add-ons.
2
Direct-cost margin
48% base
A one-point margin change at $100,000 monthly sales moves pre-reserve profit by about $1,000 before any other cost changes.
3
Inventory turn + shrink
1.6% retail proxy
NRF’s FY2022 retail shrink rate is a broad proxy; slow bolts and markdowns can create an even larger cash drag than physical shrink alone.
4
Labor + owner coverage
$19K/mo payroll
The base store assumes a working owner plus employee coverage; hiring another manager without higher sales directly reduces owner cash.
5
Occupancy + fixed cost
$11K/mo fixed
Rent, utilities, insurance, software, repairs, and administration continue even when traffic softens, raising the break-even sales floor.
6
Repeat + channel mix
17.1% online retail
U.S. e-commerce represented 17.1% of total retail sales in Q2 2026; a practical fabric shop should track whether online demand adds contribution or only fulfillment cost.
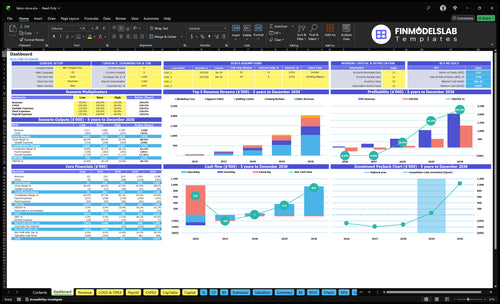
Want to test the fabric-store assumptions in a full forecast?
The Fabric Store Financial Model Template in Excel provides a business-specific dashboard for testing revenue, inventory, costs, cash runway, and profitability assumptions together. The screenshot is most useful for checking whether stronger sales actually improve owner cash after inventory purchases, payroll, fixed expenses, and financing rather than simply making the top line look larger.
How much revenue does a fabric store need to pay an owner $96,000 a year?
The base calculator needs about $98,558 a month, or $1,182,696 a year, to support an $8,000 monthly owner-pay target after reserves. Before owner take-home or reserves, operating break-even is about $72,917 a month: $35,000 of operating costs divided by a 48% margin. These are planning thresholds, not industry averages. Fabric retail is inventory-heavy, so profit can appear while cash is tied in stock. JOANN’s filing notes that assortment complexity, long lead times, seasonal buying, and excess inventory can raise carrying costs, making its public-company inventory discussion a useful adjacent warning despite the scale difference.
Build the sales target from units
Base planning ticket: about $52 per transaction.
At 26 selling days, $100,000 monthly sales imply roughly 74 transactions a day.
A $5 ticket lift at the same 74 transactions adds roughly $9,620 monthly revenue.
Do not assume that extra sales carry the same margin if discounts or shipping rise.
Separate break-even from owner pay
Operating break-even: about $72,917 monthly sales.
Target-pay revenue: about $98,558 monthly under the reserve settings.
The difference funds both the owner target and reserves, not just accounting profit.
Cash safety still depends on inventory buys, timing, and any unmodeled capital spending.
How do inventory and gross margin change owner cash?
At $100,000 monthly revenue, each one-point gross-margin change is worth about $1,000 of pre-reserve profit. After the modeled 25% tax and 10% reinvestment reserves, that is roughly $650 of owner income per month, or $7,800 a year, if other costs stay fixed. The National Retail Federation’s 2023 security survey release reported average FY2022 retail shrink of 1.6%, with rates varying by sector. At $1.2 million annual sales, that proxy equals $19,200. Fabric stores also face markdown risk from slow prints, remnants, and aging collections.
Protect contribution, not sticker price
Track landed merchandise cost by category, including inbound freight.
Measure gross margin after discounts, shrink, markdowns, and payment processing.
Bundle thread, batting, interfacing, tools, or patterns only when they improve contribution.
Review gross margin dollars per transaction, not margin percentage alone.
Make slow stock visible early
Age inventory by receipt date and collection.
Watch sell-through before reordering slow prints.
Use remnants and controlled markdowns to free working capital.
Keep open-to-buy discipline so peak-season buying does not consume owner cash.
Can a fabric store run without the owner behind the counter?
Yes, but a manager-run store needs enough gross profit to cover management payroll before distributions stay intact. The base case assumes the owner works full time as manager, buyer, scheduler, and merchandiser; $19,000 monthly employee payroll excludes owner pay. BLS May 2023 retail salesperson data reported a $16.19 median hourly wage, while BLS first-line retail supervisor data showed a $46,730 median annual wage and $52,030 mean. These are national occupation benchmarks, not fabric-store quotes. Replacing the owner with a $50,000-plus manager plus payroll burden can absorb cash that otherwise looked distributable.
Price the owner’s labor honestly
Keep owner labor separate from employee payroll in this calculator.
Compare owner output with the market cost of replacing management duties.
If the owner stops working, add management payroll before calling income passive.
Do not count one dollar as both salary and distribution.
Salary compensates work; distributions come from residual value and cash.
Coordinate payroll and distributions with a qualified tax professional.
What must be paid before a fabric-store draw is actually safe?
Safe owner cash comes after merchandise replenishment, payroll, occupancy, insurance, software, marketing, debt, tax reserves, and reinvestment—not merely after accounting profit turns positive. The base case leaves $13,000 a month before reserves, retains $4,550, and distributes $8,450. Debt deserves separate treatment because principal reduces cash. The SBA’s 7(a) lending guidance says most 7(a) terms are 10 years or less unless longer-lived real estate or equipment supports more time, and variable rates are negotiated subject to SBA maximums. The modeled $2,000 monthly debt service is an assumption, not a financing quote.
Use a cash waterfall
First: pay vendors and keep essential replenishment funded.
Second: cover payroll, rent, utilities, insurance, systems, and marketing.
Third: make required principal-and-interest payments.
Fourth: fund tax and reinvestment reserves before discretionary draws.
Watch the cash cycle
Inventory can consume cash weeks or months before the customer purchase.
Seasonal orders can make a profitable month look cash-poor.
Online growth adds shipping, packaging, returns, and fulfillment pressure.
Delay distributions when the next inventory buy would otherwise need expensive borrowing.
Key Takeaways
The base case turns $1.20 million of annual revenue into about $101,400 of owner income after modeled reserves, not a guaranteed salary.
At a 48% gross margin, about $72,917 of monthly revenue covers modeled operating costs before owner pay; roughly $98,558 supports the $8,000 monthly owner target after reserves.
Inventory quality matters as much as sales volume: shrink, markdowns, freight, and stale stock reduce both margin and working capital.
A manager-run store is not economically equivalent to an owner-operated store; replacement management payroll must be funded before distributions are called passive income.
What do low, base, and high fabric-store owner incomes look like?
These are coherent planning presets, not a promise that sales scale without cost. The low case uses $55,000 monthly revenue and a 44% margin; operating costs exceed gross profit, so modeled owner income is $0. The base case reaches $101,400 annual owner income after reserves. The high case uses $170,000 monthly sales and a 50% margin while raising labor to $32,000, fixed overhead to $16,000, marketing to $6,000, and debt service to $3,500; owner income becomes $207,900 after reserves. Base and high assume a working owner. For channel context, Census reported e-commerce at 17.1% of total U.S. retail sales in Q2 2026, a broad benchmark rather than a fabric-store target.
Owner income scenarios
Compare the same low, base, and high presets used by the owner-income calculator.
Fabric store operating and owner-income planning scenarios
Scenario
Low CaseLean
Base CaseBase
High CaseScaled
Launch modelOperating shape
Lean owner-operated store with slower demand and limited promotion.
Stabilized owner-operated specialty store with staff coverage and omnichannel sales.
Higher-throughput owner-operated store with more staff, overhead, marketing, and financing.
Typical setupSales and margin
$55,000 monthly revenue; 44% gross margin; about 47 transactions a day at a $45 planning ticket.
$100,000 monthly revenue; 48% gross margin; about 74 transactions a day at a $52 planning ticket.
$170,000 monthly revenue; 50% gross margin; about 109 transactions a day at a $60 planning ticket.
Cost driversMonthly cash load
$12,500 labor
$9,500 fixed overhead
$1,500 marketing
$1,500 debt service
20% tax + 8% reinvestment reserve
$19,000 labor
$11,000 fixed overhead
$3,000 marketing
$2,000 debt service
25% tax + 10% reinvestment reserve
$32,000 labor
$16,000 fixed overhead
$6,000 marketing
$3,500 debt service
25% tax + 12% reinvestment reserve
Owner income rangeAfter modeled tax + reinvestment reserves
$0
Annual owner income after modeled reserves.
$101,400
Annual owner income after modeled reserves.
$207,900
Annual owner income after modeled reserves.
Best fitPlanning use
Stress-test a slow ramp or undersized trade area.
Plan a stabilized independent specialty fabric retailer with a working owner.
Test a larger trade area, stronger repeat demand, and a viable online channel with added cost capacity.
!
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
What are the six biggest fabric store income drivers?
The strongest owner-income levers are transaction volume and ticket, direct-cost margin, inventory quality, labor and owner coverage, fixed overhead, and repeat/channel economics. Traffic is not valuable if discounts destroy contribution, and margin is not enough if cash is trapped in slow stock. Track each lever weekly or monthly.
1. Transaction volume and average ticket
Build revenue from purchases, not optimism
The base case uses a reasoned $52 average ticket and about 74 transactions per selling day across 26 days, which produces roughly $100,000 a month. The low case is closer to 47 daily transactions at $45; the high case is about 109 at $60. The mechanism is simple: traffic × conversion × ticket creates revenue. A store can lift ticket through coordinated notions, batting, thread, patterns, tools, or project bundles, but the attachment item must add gross profit rather than merely shift the sale into a discount.
Here’s the quick math: keeping 74 daily transactions but lifting ticket from $52 to $57 adds about $9,620 of monthly sales. At a 48% gross margin that adds roughly $4,618 of gross profit before incremental labor, fulfillment, marketing, and reserves. If the demand requires another employee shift or paid acquisition, subtract those costs before calling the lift owner income.
Track the demand equation weekly
Separate traffic, conversion, transaction count, and ticket so one strong metric does not hide weakness elsewhere.
Transactions per open day
Average ticket and units per transaction
Attachment rate for notions and project supplies
Gross profit dollars per transaction
2. Merchandise and direct-cost margin
Manage the 48% margin as a mix, not a single markup
The base 48% gross margin is a planning assumption built to be compatible with this calculator: it is what remains after merchandise, inbound freight, shrink, markdowns, payment processing, and other non-labor direct costs. That is deliberately stricter than copying a public-chain gross margin because JOANN’s FY2023 46.9% figure included merchandise, freight, shrink, and clearance in cost of sales but put card acceptance fees in SG&A. The SEC filing’s gross-profit definition is the adjacent evidence; the independent-store percentages are modeled assumptions.
At $100,000 monthly revenue, 47% margin produces $47,000 of gross profit and 49% produces $49,000. With the base operating costs and 35% combined reserves, that two-point spread changes modeled owner income by about $1,300 per month, or $15,600 a year. That makes category mix, vendor terms, freight, and discount discipline direct owner-pay decisions.
Close the margin loop by category
Review realized margin after discounts and loss, not theoretical markup at receiving.
Fabric gross margin by collection
Notion and tool contribution
Freight and payment processing as a percent of sales
Markdown dollars and coupon dilution
3. Inventory turn, markdowns, and shrink
Protect cash from beautiful inventory that does not move
Fabric retail can carry many colors, prints, substrates, widths, notions, and seasonal collections. The large-chain comparison is instructive: JOANN said it carried tens of thousands of in-store SKUs and that assortment complexity, long lead times, seasonality, and forecasting errors could create excess inventory and higher carrying cost. An independent shop will carry far fewer SKUs, but the cash mechanism is the same. NRF reported 1.6% average retail shrink for FY2022, with material variation by sector.
At $1.2 million of annual sales, a 1.6% sales-value proxy is $19,200. But physical shrink is only part of the exposure: aged bolts may require markdowns, remnants need recovery, and overbuying ties cash that cannot fund payroll or owner draws. An owner should prefer faster cash recycling at a healthy realized margin over a showroom full of slow stock purchased to chase variety.
Run an open-to-buy and aging report
Measure what is selling before the next order is placed, especially ahead of seasonal buying.
Weeks of supply by category
Sell-through at 30, 60, and 90 days
Inventory dollars aged over 120 days
Shrink, remnants, and markdowns as a percent of sales
4. Labor cost and owner coverage
Decide whether owner income includes a job
The base store budgets $19,000 a month for non-owner labor and assumes the owner supplies full-time management. That matters because owner income is partly compensation for real work before it can be thought of as a return on invested capital. BLS May 2023 data puts the national retail salesperson median at $16.19 per hour and the first-line retail supervisor median at $46,730 a year; actual local wages, payroll taxes, benefits, and scheduling needs can be higher. The retail supervisor wage benchmark is especially useful for estimating replacement management cost.
If an owner wants to step out and a replacement manager costs roughly $50,000 to $60,000 before full payroll burden, the business needs roughly $4,200 to $5,000 more monthly payroll before burden. At a 48% margin, covering an extra $5,000 of monthly payroll alone takes about $10,417 of added monthly revenue before reserves. Without that lift, distributions fall.
Measure sales and gross profit per labor hour
Schedule to workload, but keep enough expertise on the floor to convert project questions into complete baskets.
Payroll as a percent of revenue
Gross profit dollars per labor hour
Owner hours by management task
Cost to replace owner duties
5. Occupancy and fixed overhead
Keep the fixed base below what normal months can carry
The base model uses $11,000 a month for rent, utilities, insurance, software, repairs, bookkeeping, and administration. It is a reasoned planning assumption for a mid-cost U.S. specialty store, not a national rent statistic. Because it is fixed, the number becomes more dangerous when sales soften. With $19,000 labor, $3,000 marketing, and $2,000 debt service, the total monthly operating-cost load is $35,000; at 48% gross margin the store needs about $72,917 in monthly revenue just to reach zero profit before reserves and owner pay.
A $2,000 increase in fixed overhead raises operating break-even by about $4,167 of monthly revenue at the same margin. That sensitivity is why a visually perfect but oversized location can reduce owner income for years. Compare rent and common-area charges with realistic normal-month demand, not only peak holiday sales.
Stress-test the lease before signing
Convert every fixed commitment into the sales it requires at the expected gross margin.
Fixed overhead per month
Occupancy cost as a percent of sales
Break-even revenue at current margin
Lease escalators and renewal exposure
6. Repeat demand and channel mix
Make repeat projects and online orders carry contribution
Fabric demand is project-driven, so a customer who returns for another quilt, garment, décor project, class, or replenishment can be cheaper to serve than a cold acquisition. As an adjacent large-chain signal, JOANN reported that returning customers generated 44% of FY2023 net sales. That does not establish a target for an independent shop, but it shows why customer frequency is economically important. At the broader market level, the U.S. Census Q2 2026 e-commerce report put online sales at 17.1% of total retail sales.
Online revenue should be measured after pick-and-pack labor, packaging, shipping subsidies, payment fees, returns, and marketing. A $10,000 online sales increase at a 50% merchandise contribution can look attractive, but if fulfillment, shipping support, ads, and returns consume $2,500, only $2,500 remains before fixed overhead and reserves. Repeat in-store customers may create less top-line excitement while delivering better cash economics.
Track customer and channel contribution
Use repeat rate and channel margin together so growth does not hide fulfillment leakage.
Repeat-customer share of revenue
Purchase frequency by customer cohort
Online contribution after fulfillment and returns
Customer acquisition cost versus first-year gross profit
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.