How Much Online Fax Service Owners Make: $127K To $346M EBITDA
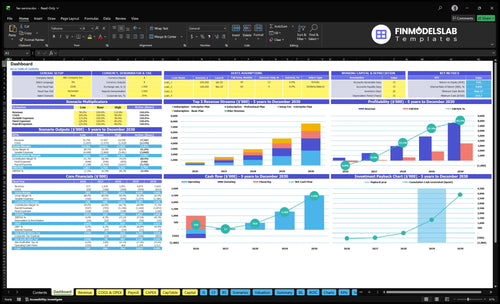
Online Fax Service Bundle
An online fax service owner may have little or no distributable income in the first year because the model shows -$317K EBITDA on $573K revenue The researched assumptions reach break-even around Month 17, with $127K EBITDA in Year 2 By Year 5, the model reaches $7629M revenue and $3459M EBITDA, but owner take-home still depends on reserves, payroll, marketing, and reinvestment Treat these as modeled pre-tax profit ranges, not guaranteed pay
Owner income$3.46MNet margin45%Revenue for target pay$1.53M+Business difficultyHard
Want to test your online fax income?
Owner income calculator
Estimate owner take-home and target-pay gap from revenue, margin, costs, reserves, and target pay.
!
Planning note: This is a researched planning estimate, not guaranteed salary, tax advice, or owner distribution advice. Actual owner income depends on revenue, margins, payroll, taxes, debt, and reserves.
Want the six drivers that move owner income?
1
Paid Volume
15%-22%
More free-trial users turning paid is the main revenue engine, because each added account keeps paying every month.
2
Plan Mix
$15-$99
Shifting the mix toward Professional and Enterprise lifts ARPU, and the $500 setup fee on Enterprise adds extra cash up front.
3
Usage Costs
6%-8%
Carrier transmission fees start at 8% and ease to 6%, so every point saved drops cost of sales and raises margin.
4
Retention
39 mo
Keeping subscribers long enough to clear the 39-month payback window is what turns acquisition spend into owner profit.
5
CAC
$35-$45
Lower customer acquisition cost means more paid accounts for the same marketing budget, which matters as spend scales from $120K to $1.0M.
6
Overhead
$9K/mo
Non-wage fixed overhead is about $9K a month, and that floor helps explain the Month 17 break-even point.
Want to pressure-test owner income in the Online Fax Service model?
How much revenue does an online fax service need to pay the owner?
Online Fax Service owner pay should be tied to EBITDA, not revenue. In Year 1, the model has -$317K EBITDA on $573K revenue, so there’s no room for owner distributions. In Year 2, it reaches $127K EBITDA on $1.529M revenue, but that still comes before reserves and owner taxes, and any paid owner role should be booked as salary, not distributions.
Year 1 cash reality
$573K revenue
-$317K EBITDA
$9K monthly fixed overhead
$120K Year 1 marketing
Year 2 owner pay test
$1.529M revenue
$127K EBITDA
Separate salary from distributions
Hold cash through Month 17
Is an online fax service profitable?
Yes, an Online Fax Service can be profitable, but only under the modeled unit economics, not by default; recurring subscriptions help revenue stability, while carrier, support, uptime, and customer acquisition costs decide the outcome. In this model, break-even occurs in Month 17, variable cost load improves from 200% of revenue in Year 1 to 156% in Year 5, and EBITDA margin moves from -553% in Year 1 to 453% in Year 5; for startup cost context, see How Much To Start Online Fax Service Business?. The quick read: this works if regulated-industry demand is real, churn stays low, and acquisition spend doesn’t outrun subscription revenue.
Profit Signals
Break-even at Month 17
Subscription revenue adds stability
Year 5 EBITDA margin: 453%
Costs improve after early scale
Risk Controls
Keep churn low
Control carrier costs
Maintain strong uptime
Watch acquisition efficiency
How hard is it to scale an online fax service?
Scaling an Online Fax Service is harder than a simple software app because buyers expect uptime, deliverability, number management, compliance, and fast support. In the model, customer success grows from 1 specialist in Year 1 to 8 in Year 5, and security and DevOps rises from 1 to 3 FTEs. Marketing also scales from $120K to $10M, so income only improves if churn, CAC, telecom rates, and support tickets stay inside plan assumptions.
Why it’s harder
Uptime must stay high
Deliverability must be reliable
Numbers need active management
Compliance adds real overhead
What must scale
Support grows 1 to 8 FTEs
Security/DevOps grows 1 to 3 FTEs
Marketing can reach $10M
Churn and CAC must stay on model
Key Takeaways
More active paid subscribers drive MRR fastest.
Plan mix lifts ARPU, but churn must stay low.
Telecom fees and retries can crush gross margin.
CAC, retention, and overhead decide owner take-home.
Compare lean, base, and high-case online fax income scenarios
Owner income scenario table
Trial conversion, plan mix, CAC, and marketing spend drive owner income here. Break-even lands by Month 17, and payback follows by Month 39.
Low, base, and high cases show how owner cash flow changes as volume and margin improve.
Scenario
Low CaseLow Case: Month 17 break-even
Base CaseBase Case: Positive EBITDA
High CaseHigh Case: Month 39 payback
Launch model
This is the downside path with Year 1 revenue of $573K, a -$317K EBITDA result, and no clear owner distributions.
This is the middle path with Year 3 revenue of $2.901M and $669K EBITDA, so owner draw room opens.
This is the upside path with Year 5 revenue of $7.629M and $3.459M EBITDA, so owner cash flow is much stronger.
Typical setup
Year 1 stays Basic-heavy at 60%, uses $15, $35, and $99 monthly plans, runs on $120K marketing, 5.0% free-trial conversion, 15.0% trial-to-paid conversion, and 88.0% gross margin after carrier and cloud costs.
Year 3 shifts to a 50% Basic, 35% Professional, and 15% Enterprise mix, with $450K marketing, $40 CAC, 6.0% free-trial conversion, 18.0% trial-to-paid conversion, and 90.0% gross margin.
Year 5 moves to a 40% Basic, 35% Professional, and 25% Enterprise mix, with $1.0M marketing, $35 CAC, 7.0% free-trial conversion, 22.0% trial-to-paid conversion, and 92.0% gross margin.
Cost drivers
High CAC
$120K marketing
88.0% gross margin
15.0% trial-to-paid
Basic-heavy mix
$450K marketing
$40 CAC
90.0% gross margin
18.0% trial-to-paid
more Enterprise mix
$1.0M marketing
$35 CAC
92.0% gross margin
22.0% trial-to-paid
25% Enterprise mix
Owner income rangeBefore owner reserves
-$317K EBITDALow Case
$669K EBITDABase Case
$3.459M EBITDAHigh Case
Best fit
Use this to stress-test cash needs if paid conversion stays weak and the Basic plan keeps most of the mix.
Use this for the core operating plan if acquisition and conversion hold near model levels.
Use this to test upside if enterprise share rises and the funnel keeps improving without breaking margins.
!
Planning note: Scenario ranges are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distributions.
Online Fax Service Core Six Income Drivers
Subscriber count
Active Paid Subscriber Count
Here’s the quick math: only active paying fax accounts create MRR. Free trials, inactive users, and one-time fax users don’t count, so the real base is paid subscribers that stay live. In the model, visitor-to-trial improves from 50% to 70% and trial-to-paid from 150% to 220%, lifting revenue from $573K to $7,629M as volume scales.
This driver hits owner income first because each added paid account spreads support, compliance, and platform costs across more monthly revenue. The catch is quality: if customers churn before CAC payback, cash gets tight even when signups look strong. One line says it best: more paid accounts help only when they keep paying.
Track Paid Conversion Quality
Measure the full funnel by source: visitor-to-trial, trial-to-paid, and 30/60/90-day churn by cohort. Keep active paying accounts separate from trials and one-time fax users in every dashboard, or the subscriber base will look bigger than it is. The key test is simple: how many accounts still pay after acquisition cost has been earned back?
Use tighter targeting and pricing tests to raise paid subscriber count without buying weak traffic. If new accounts grow but retention falls, MRR stalls and owner draw weakens. Track payback by cohort, then cut channels that add accounts below the break-even retention window. One line: count the accounts that stay, not the ones that start.
Customer acquisition cost
Customer acquisition cost
For an online fax service, customer acquisition cost (CAC) is the cash spent to win one paying account. Here it moves from $45 in Year 1 to $35 in Year 5, even as marketing spend rises from $120K to $10M. That means growth is buying more accounts, but owner take-home still depends on whether those customers stay long enough to recover CAC.
Here’s the pressure point: paid search, SEO, affiliates, and business partnerships can all lower or raise CAC by channel. If churn is high, CAC payback slips and cash stays trapped in growth spend instead of distributable profit. The business also shows a $254K minimum cash need, so slow payback can delay owner draws even when revenue is rising.
Track CAC by channel
Measure CAC as marketing spend ÷ new paying customers, then split it by paid search, SEO, affiliates, and partnerships. Don’t mix free trials or inactive users into the count. The goal is simple: know which channel brings customers who stay past payback, not just which channel drives signups.
Watch CAC next to churn and payback period. If one channel looks cheap but cancels fast, it hurts cash flow and owner income. Keep an eye on the $45 to $35 CAC trend, because lower CAC only helps if retention holds and the subscription margin covers the upfront spend fast enough.
Churn and retention
Churn and retention
Churn is the share of paid accounts that cancel each month. In an online fax service, lower churn lifts lifetime value and cuts the replacement marketing spend needed to keep revenue steady, and that matters most for users tied to compliance workflows, saved numbers, routing rules, and support history.
Track the churn inputs
Make monthly churn an editable assumption, since it is not provided. Track paid accounts, cancellations, average monthly revenue per account, and replacement marketing cost; if reliability drops or onboarding is slow, cancellations rise and the $35 to $45 CAC payback gets weaker, which reduces cash available for owner pay.
Telecom usage cost control
Telecom usage cost control
For an online fax service, this driver is the gap between subscription revenue and the telecom bill. Carrier transmission fees are 80% of revenue in Year 1 and 60% in Year 5, while hosting falls from 40% to 20%. Gross margin comes before overhead and owner pay, so usage costs can crowd out profit fast.
Track active customers, plan mix, transactions per customer, retries, inbound volume, and outbound delivery failures. The disclosed usage ranges are 5, 12, and 50 transactions per active customer by plan. Heavy-user plans can compress margin, but overage fees and tight plan limits help protect take-home income.
Measure usage before it eats margin
Set plan limits from real fax volume, then watch usage cost per active customer and gross margin by plan. If retries or failed deliveries spike, the carrier bill rises without adding much revenue. That is the leak to fix first. One clean rule: when a higher tier pushes volume toward 50 transactions, price the extra load or cap it.
Build a monthly check on overage revenue, failure rate, and carrier fees as a share of revenue. The goal is to move from the Year 1 cost profile toward the Year 5 profile so more cash reaches overhead coverage and owner pay. If onboarding low-value users lifts volume but not margin, tighten qualification or plan rules.
ARPU and plan mix
Plan mix lifts ARPU
An online fax service makes more money when more paying users sit on $15 Basic, $35 Professional, or $99 Enterprise plans. Plan mix changes revenue through page allowances, users, storage, overages, and enterprise features, so blended subscription ARPU can rise even if total account count is flat.
Here’s the quick math: when enterprise mix rises from 100% to 250%, blended subscription ARPU moves from about $2,940 to about $4,300. That’s a direct boost to gross profit and owner take-home, but only if churn stays controlled and price hikes do not trigger stronger competitive pressure.
Track tier mix, not just signups
Measure paid accounts by tier, plus overages, added users, and storage use. A high signup count can still produce weak cash flow if most customers stay on the lowest plan. The key metric is blended ARPU, because it drives recurring revenue quality and the profit available for owner pay.
Track Basic, Professional, Enterprise mix
Watch overages and add-on fees
Test price before raising it
Check churn after each change
What this estimate hides: higher prices work only when customers keep value in the plan. If they need more pages, users, or storage, they may upgrade; if they do not, they may churn or push back on renewal. Forecast revenue by tier, not as one blended average.
Platform, support, and compliance overhead
Platform, support, and compliance overhead
$9K per month of fixed overhead covers HIPAA compliance audits, security tools, support platform, legal retainer, and admin wages. That sits below gross margin, so it still cuts owner pay. Add the listed roles — $140K CTO and lead developer, $110K product manager, $125K security and DevOps, $75K sales, and $55K customer success — and the payroll base is $505K a year, or about $42.1K a month.
Here’s the quick math: fixed overhead plus payroll is about $51.1K per month before variable usage costs. If usage is heavy or support demand rises, distributable income drops fast even when revenue and gross margin look healthy. The key check is whether recurring gross profit can cover this base and still leave cash for owner draw.
Track fixed cost per active account
Keep fixed overhead separate from variable transmission and hosting costs. Track monthly overhead, annual payroll, and active paying accounts so you can see the cost per customer and the true profit left for the owner. A clean ledger should show what is compliance, what is support, and what is product labor.
One line to watch: fixed cost ÷ active subscribers. If that ratio climbs while subscription growth stalls, owner pay gets squeezed before gross margin problems show up. Review hiring against churn, support tickets, and compliance load, and delay new headcount until recurring revenue can cover the full $51.1K monthly base plus variable usage.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.