Which Metrics Best Predict Owner Income from a Furniture Store?
For an owner-operated independent U.S. furniture showroom, a practical planning range is about $21,000 to $208,656 a year after modeled tax and reinvestment reserves, with a base case of $82,680 on $1.44 million in annual sales. The base case assumes a 48% gross margin after merchandise and other non-labor direct costs, $24,000 a month of non-owner payroll, $14,000 of fixed overhead, $5,000 of marketing, and $4,000 of debt service. The owner is assumed to work as general manager and buyer, so no hired general manager is included. This is a planning estimate, not a guaranteed salary, personal tax result, or guaranteed distribution.
Owner income$82.7KNet margin6%Revenue for target pay$1.48MBusiness difficultyHard
How much can a furniture store owner make?
For this article, “furniture store” means a U.S. retailer selling new household, outdoor, or office furniture, consistent with the Census NAICS 449110 definition, rather than a used-furniture shop or a custom manufacturer. The low, base, and high cases produce $21,000, $82,680, and $208,656 of annual owner income after the model's tax and reinvestment reserves. Those figures are economic owner cash, not an industry salary statistic.
The range is wide because owners control sales, merchandising, staffing, inventory, and financing. As a public-company reference rather than a small-store benchmark, Havertys reported a 2025 average ticket of $3,530, sales of $167 per weighted-average retail square foot, and a 60.7% gross margin in its 2025 Form 10-K. The base case below is more conservative: it uses a $2,400 realized ticket planning assumption, about 50 completed orders a month, and a 48% reconstructed gross margin to account for costs a small independent operator cannot assume will match a large chain.
Owner income calculator
Estimate owner cash after operating costs and modeled reserves, then test the revenue needed for a target owner pay.
i
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
1
Order volume and conversion
50 orders/mo
The base case needs roughly 50 completed $2,400 orders each month. A few extra converted showroom or web leads can move owner cash materially because fixed costs are already covered.
2
Average ticket and mix
$2.4K ticket
Bedroom groups, upholstery, protection plans, and design-assisted bundles can lift revenue per order without requiring the same increase in traffic.
3
Gross margin and markdowns
48% base
Vendor cost, freight, discounting, card fees, and clearance discipline determine how much of every sales dollar remains before payroll and occupancy.
4
Labor and owner role
$24K/mo
The base payroll excludes owner pay and assumes the owner covers general management and buying. Hiring that role requires enough extra gross profit to fund it.
5
Inventory and delivery cash timing
$3.7K/mo reserve
Inventory may be paid for before delivery revenue is recognized. The base tax and reinvestment reserves keep part of cash profit out of the owner's draw.
6
Showroom productivity and demand
$180/sq ft
An 8,000-square-foot planning showroom at $1.44 million annual sales produces about $180 per square foot, making lease and marketing productivity visible.
Want to test the assumptions in a full furniture store forecast?
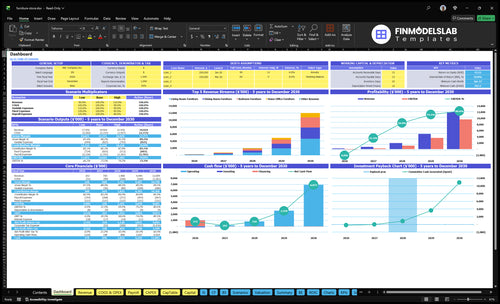
The Furniture Store Excel Financial Model for Startups can stress-test revenue, mix, margin, payroll, inventory, debt, and cash runway. The dashboard helps check whether sales growth becomes cash rather than only larger inventory needs.
What sales volume supports an $8,000 monthly owner target?
Under the base cost structure, the store needs about $123,558 of monthly revenue, or $1.48 million annualized, to support an $8,000 monthly owner-income target after reserves. For context, the U.S. furniture and home-furnishings store category recorded $11.315 billion of seasonally adjusted sales in June 2026 in the Census retail-sales series published through FRED; that national total shows category scale, not what one store should expect.
Translate revenue into orders
Base sales: $120,000 per month
Planning ticket: $2,400
Required completed orders: about 50 per month
Target-pay revenue: about $123,558 per month
Test store productivity
8,000-square-foot planning showroom
Base productivity: about $180 per square foot annually
Public-chain reference: $167 per square foot in 2025
Track written orders and delivered sales separately
Havertys reported a $3,530 average ticket in 2025, and defined ticket as sales divided by orders, in the same SEC filing. This model deliberately uses $2,400 because a single independent showroom may have a different category mix, financing offer, brand position, and design-service attachment. At $2,400, moving from 50 to 55 monthly orders adds $12,000 of revenue. At a 48% gross margin, that adds $5,760 of gross profit before any extra commission, delivery, marketing, or overhead required to serve those orders.
How much margin does a furniture store need before owner pay is safe?
In the base case, 48% is the gross-margin assumption that leaves enough room for $47,000 of monthly operating costs and a meaningful owner residual. Havertys reported 60.7% gross margin in 2025, but its 10-K cost presentation places delivery, occupancy, selling compensation, and other costs below gross profit, so a small store should not copy 60.7% into this calculator without reconstructing what is included.
Base cash waterfall
$120,000 monthly revenue
$57,600 gross profit at 48%
$47,000 operating costs including debt service
$10,600 cash profit before reserves
Know the two break-even bars
Operating break-even: about $97,917 monthly sales
That is about $1.175 million annualized
$8,000 owner target: about $123,558 monthly sales
Reserves make safe owner pay harder than simple break-even
Revenue is not profit. Gross profit is what remains after direct product-related costs. Accounting operating profit or EBITDA then subtracts operating expenses, with EBITDA excluding interest, taxes, depreciation, and amortization. This calculator's “profit before reserves” is different again: it subtracts the modeled principal-and-interest debt service, so it is a cash-planning residual, not EBITDA or GAAP net income. Owner income is the amount left after the tax and reinvestment reserves. A draw or distribution is merely how cash is transferred to an owner; it does not create extra profit.
Key Takeaways
The base case produces $82,680 annual owner income after modeled reserves on $1.44 million annual revenue.
Operating break-even is about $98,000 a month, but an $8,000 monthly owner target needs about $124,000 a month at base assumptions.
Owner labor is not hidden in payroll: the base case assumes the owner manages and buys, while $24,000 monthly labor covers non-owner staff.
Inventory, customer deposits, delivery timing, debt service, taxes, and reinvestment can make cash available for distribution much lower than accounting profit suggests.
Can the store run without the owner managing the floor?
Yes, but a manager-run store needs more gross profit than this owner-operated base case. May 2025 BLS national wage data put retail salespersons at a mean $17.94 an hour, or $37,310 annually, while hand freight and material movers averaged $20.32 an hour, or $42,260 annually. Those are employee wage benchmarks, not the cost of a general manager, and employer payroll taxes, benefits, commissions, and overtime can raise actual payroll above the wage rate.
Owner-operated base
Owner acts as general manager and buyer
$24,000 monthly non-owner payroll
Owner income is residual after modeled reserves
No second manager salary is added on top
Manager-run test
Add the full manager employment cost to labor
Require sales or margin to cover the new layer
Keep owner distributions separate from payroll
Do not treat passive ownership as free management labor
The distinction between salary and distributions is legal and tax-specific. The IRS guidance on paying yourself notes that corporate officers are generally employees and that wages should be commensurate with duties. For planning, this calculator reclassifies owner-manager compensation out of employee payroll so “labor cost” contains only non-owner staff; the resulting owner income is total economic cash compensation available to the owner after reserves. In actual books, an owner may receive W-2 salary, draws, distributions, or a combination depending on entity type. A salary recorded in payroll must not then be added again as an extra distribution on top of this model's owner-income figure.
Why can a profitable furniture store still run short of cash?
Furniture retail has a timing problem: inventory can be purchased, freight can be paid, and floor samples can sit before the final customer delivery turns an order into recognized sales. Havertys reported $35.5 million of customer deposits at year-end 2025 and said those balances change with merchandise-delivery timing in its SEC disclosure. A small store has the same mechanism at a smaller scale, even though its vendor terms and deposit policies may differ.
Cash that is not yet safe to draw
Customer deposits tied to undelivered orders
Cash committed to replenishment and floor samples
Sales and payroll taxes coming due
Debt principal and interest payments
Base reserve discipline
25% tax reserve on positive cash profit
10% reinvestment reserve
$3,710 retained in the base month
$6,890 left as monthly owner income
Debt can bridge working-capital needs, but it also lowers the cash available to the owner. The SBA 7(a) program allows eligible uses including short- and long-term working capital, but qualification and repayment capacity still matter. The base model therefore includes $4,000 monthly principal-and-interest service instead of treating financing as free cash. Tax reserves are also cash, not an accounting margin. The 25% setting here is only a planning reserve and must be replaced with entity-, state-, and owner-specific advice.
What do low, base, and high owner-income scenarios look like?
The cases move costs with sales instead of changing revenue alone. The low case keeps minimum fixed costs; the high case raises labor, overhead, marketing, and debt service. Each then applies tax and reinvestment reserves before owner income, so stronger sales do not automatically become fully distributable cash.
Owner income scenarios
Compare linked sales, margin, staffing, overhead, financing, and reserve assumptions across three furniture-store operating cases.
Low, base, and high furniture store owner-income planning cases.
Scenario
Low CaseConservative
Base CasePlanning case
High CaseUpside case
Launch modelDemand and owner role
Slower demand, owner manages, and owner draw remains tight.
Stable local showroom with the owner managing and buying.
Stronger demand with more staff, support costs, and inventory capacity.
Typical setupMonthly operating inputs
$100,000 revenue, 45% gross margin, and $42,500 operating costs.
$120,000 revenue, 48% gross margin, and $47,000 operating costs.
$180,000 revenue, 52% gross margin, and $66,000 operating costs.
Cost driversCosts that move with scale
$22,000 labor
$13,500 fixed overhead
$3,000 marketing; $4,000 debt
20% tax; 10% reinvestment reserve
$24,000 labor
$14,000 fixed overhead
$5,000 marketing; $4,000 debt
25% tax; 10% reinvestment reserve
$34,000 labor
$18,000 fixed overhead
$8,000 marketing; $6,000 debt
25% tax; 12% reinvestment reserve
Owner income rangeAfter modeled reserves
$21,000
Annual owner income after modeled reserves.
$82,680
Annual owner income after modeled reserves.
$208,656
Annual owner income after modeled reserves.
Best fitPlanning use
Stress test for weak conversion, discounting, or a slow ramp.
Operating budget for a stable owner-managed independent showroom.
Capacity test for stronger demand with the staffing and overhead needed to support it.
i
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
Which six drivers move furniture store owner income the most?
The strongest levers are order volume, average ticket, gross margin, labor structure, inventory and delivery cash timing, and showroom productivity. A small store should track that full economic chain while using its own local prices, lease, staffing, and vendor terms.
1. Order volume and conversion
Turn traffic into completed deliveries, not just written orders
The base model is about 50 completed orders a month at a $2,400 realized ticket. The financial mechanism is simple: orders multiplied by ticket equals revenue. Five additional monthly orders at the same ticket add $12,000 of sales; at a 48% gross margin, that is $5,760 of gross profit before any extra labor, delivery, marketing, or overhead. Havertys' 2025 KPI framework separately tracks traffic, conversion, written sales, and delivered net sales, a useful distinction because furniture orders can be written well before delivery.
Conversion is useful only when discounts, cancellations, and delivery exceptions stay controlled.
Track a weekly order funnel
Connect marketing activity to delivered gross profit rather than leads alone.
Qualified showroom and web leads
Lead-to-order conversion rate
Written orders versus delivered sales
Cancellations, returns, and gross profit per order
Owner income rises fastest when incremental orders fit existing showroom and delivery capacity.
2. Average ticket and product mix
Raise ticket without buying the same growth twice
The $2,400 base ticket is a planning assumption, not a national independent-store benchmark. Havertys reported a 2025 average ticket of $3,530 and a $7,781 average written ticket when design consultants were engaged in its Form 10-K. That large-chain result shows the potential effect of mix and design services, not a target a new independent store should copy.
At 50 orders a month, lifting realized ticket from $2,400 to $2,600 adds $10,000 in monthly revenue. If gross margin stays at 48%, gross profit rises by $4,800 before extra fulfillment cost. The higher ticket helps only when it comes from profitable mix or service attachment rather than deeper discounting.
Measure ticket quality, not just ticket size
Review average ticket alongside margin so a bigger order does not hide a weaker contribution.
Realized ticket by category
Gross profit dollars per order
Protection, accessory, and design attachment
Discount and financing-fee percentage
Use delivered revenue for owner-cash planning, especially where lead times are long.
3. Gross margin and markdown discipline
Protect the dollars that have to fund every fixed cost
The model uses 45%, 48%, and 52% gross margins for low, base, and high cases. Havertys reported 60.7% in 2025, but its SEC filing describes delivery, occupancy, selling costs, and other items below gross profit. This calculator instead asks gross margin to absorb merchandise, inbound freight, card or financing charges, and other non-labor direct costs before payroll is entered separately, so 48% is a deliberately reconstructed planning margin rather than a copied benchmark.
At $120,000 monthly sales, one margin point is $1,200 of gross profit. Moving from 48% to 45% cuts gross profit by $3,600 a month. With other base costs unchanged, that nearly eliminates the $6,890 monthly owner-income output after reserves. Track vendor terms, freight, damages, clearance, and markdowns alongside list price.
Close the margin leak by category
Use actual landed economics, not vendor MSRP, to judge whether a product family earns its floor space.
Landed product cost percentage
Markdown and clearance rate
Card and consumer-financing fees
Gross margin by vendor and category
A modest margin improvement can raise owner cash without adding another customer or square foot.
4. Labor and the owner's operating role
Price the management work the owner is actually doing
The base case budgets $24,000 a month for non-owner labor and assumes the owner performs general-management and buying work. May 2025 BLS wage data show national mean pay of $17.94 an hour for retail salespersons and $20.32 for hand freight and material movers. Those wage figures exclude the owner's work and do not by themselves include the full employer cost of taxes, benefits, commissions, or overtime.
This matters when comparing owner-operated and semi-absentee stores. If a hired management layer costs $7,000 a month all-in, simply adding that amount to base labor would push cash profit before reserves from $10,600 to $3,600. At the base 25% tax and 10% reinvestment reserves, owner cash would fall sharply unless revenue or gross margin rises. A passive owner's distribution is therefore not comparable with an owner-operator replacing paid labor.
Separate labor economics from owner withdrawals
Build a shadow cost for the owner's role even when the calculator intentionally keeps owner pay out of labor.
Sales payroll as a percentage of revenue
Delivery and warehouse hours per order
Commission and payroll-burden rate
Hours the owner spends managing, buying, and selling
For tax reporting, match salary and distribution treatment to the business entity rather than the calculator label.
5. Inventory and delivery cash timing
Keep profitable orders from creating a cash squeeze
Furniture cash flow can move before accounting revenue. Havertys disclosed that customer deposits cover undelivered merchandise and that changes in those deposits are driven by delivery timing; it also reported delivery fees of about $30.2 million and delivery costs of about $36.8 million in 2025 in its financial-statement notes. The small-store mechanism is similar: a deposit is not automatically free cash, and delivery still consumes capacity.
The base model retains 10% of positive cash profit for reinvestment and includes $4,000 of monthly debt service. If inventory expands faster than delivered sales, even that reserve may be insufficient. Borrowed working capital creates repayment obligations that must be covered before owner cash is safe.
Run a delivery-to-cash schedule
Forecast the timing of vendor payments, customer deposits, final collections, and delivery costs by week.
Inventory weeks on hand and aged floor samples
Customer deposits on undelivered orders
Vendor payment terms and freight due dates
Delivery gross profit and damage or re-delivery cost
Owner distributions should wait until restricted or committed cash is separated from genuinely surplus cash.
6. Showroom productivity and demand generation
Make every square foot and marketing dollar carry overhead
An 8,000-square-foot showroom is a planning assumption for the base case, not a national standard. At $1.44 million annual sales it produces about $180 per square foot, close enough to use Havertys' 2025 $167 per weighted-average retail square foot as an adjacent reasonableness check while recognizing its much larger scale. The broader Census monthly retail-sales series put June 2026 seasonally adjusted category sales at $11.315 billion nationally.
The base budget puts $14,000 a month into fixed overhead and $5,000 into marketing. That marketing spend is about 4.2% of base sales. Havertys disclosed $43.5 million of 2025 advertising expense on $759.0 million of net sales, roughly 5.7%, but a local store should budget from customer-acquisition economics rather than copying a chain percentage. The goal is qualified demand that covers showroom and delivery capacity without buying low-margin orders.
Track productivity as one connected system
Marketing is justified when it produces delivered gross profit after commissions, discounts, and fulfillment.
Annual sales per selling square foot
Marketing cost per delivered customer
Gross profit per marketing dollar
Weekend, holiday, and promotion-period conversion
When demand rises, add staff, inventory, and delivery capacity before promising the high-case owner income as if costs were fixed.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Furniture Store Bundle
Choosing a selection results in a full page refresh.