How Should an Owner Estimate Income from a Garden Nursery?
Garden Nursery Bundle
A full-time owner-operator of an independent U.S. garden nursery can reasonably plan around $92,400 a year of owner cash in a stabilized base case, with a much wider modeled range of about $14,700 to $157,600. This article models a retail nursery that sells plants and garden supplies to consumers, buys in much of its inventory, grows a limited share on site, and has the owner working in daily operations. The base case uses $840,000 of annual revenue, a 45% gross margin after product and plant costs, $120,000 of non-owner payroll, $78,000 of fixed overhead, $18,000 of marketing, and $30,000 of annual debt service. The $92,400 figure is after modeled tax and reinvestment reserves; it is not a separate salary plus a distribution, and it does not guarantee the owner's final personal tax bill. The scale is plausible in a large U.S. horticulture market: the USDA's 2024 horticulture census release reported $18.3 billion of horticultural sales and $5.34 billion of nursery-stock sales, but an individual retail nursery's result depends much more on local traffic, seasonality, ticket size, shrink, labor coverage, and cash tied up in inventory.
Owner income$92KNet margin11%Revenue for target pay$813KBusiness difficultyHard
Want to test your garden nursery owner pay?
The calculator below is a cash-planning bridge, not an accounting income statement. Its base gross margin of 45% is a reasoned retail-nursery assumption anchored by direct-market pricing logic; University of Maryland Extension describes 40% gross margin as a common direct-to-consumer producer target, while actual garden-center retail margins vary by product mix, sourcing, local competition, and shrink. All employee payroll is separated from gross margin here, and the owner's own labor is intentionally excluded from payroll so the residual output represents the total cash available to compensate the working owner and ownership capital.
Owner income calculator
Estimate owner take-home, break-even pressure, and the revenue needed for a target draw.
i
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
The base case breaks even on this cash basis at roughly $45,556 per month before owner reserves; supporting a $7,000 monthly owner target after reserves needs $67,778. This is not EBITDA because the bridge subtracts debt service, including principal. Accounting profit may subtract depreciation but not loan principal. Salary is payroll compensation; a draw or distribution is an ownership withdrawal; safe owner cash is what remains after vendors, payroll, debt, taxes, inventory, repairs, and liquidity reserves are funded.
Which six levers move garden nursery owner income most?
Garden-nursery economics are highly sensitive to price, labor, and product loss. A University of Florida greenhouse enterprise-budget study identifies price and labor as major profit sensitivities and uses a 10% shrink assumption. Because that is grower-side evidence, the cards below pair it with explicit retail planning assumptions.
1
Seasonal sales volume
$70K/month
Base annualized sales are $840,000, but the monthly average hides spring peaks and winter troughs; traffic conversion and sell-through set the revenue ceiling.
2
Gross margin
45%
Every margin point on $840,000 of sales is worth about $8,400 of annual gross profit before payroll and fixed costs.
3
Average ticket and mix
$58 ticket
The base case assumes roughly 1,207 transactions a month; bundles, larger specimens, soil, pottery, and add-ons can lift revenue without equal traffic growth.
4
Labor and owner role
$10K/month
Base payroll excludes the working owner. Adding a hired manager can absorb much of the residual owner cash unless sales and margin rise with the handoff.
5
Inventory turn and shrink
10% stress test
Live inventory can die, outgrow containers, become seasonal leftovers, or require discounting; shrink converts purchased inventory directly into lost margin and cash.
6
Fixed cost and debt load
$9K/month
Base fixed overhead plus debt service totals $9,000 monthly before marketing and payroll, so slow months still consume cash even when the sales floor is quiet.
Want to test the nursery assumptions in a full forecast?
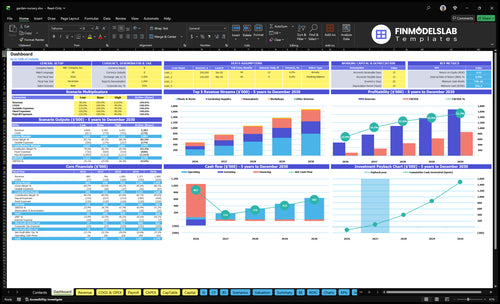
The Garden Nursery Financial Model Template for Excel and Google Sheets provides a business-specific dashboard for testing revenue streams, payroll, cost assumptions, cash flow, scenarios, and break-even. The screenshot is most useful here for checking whether transaction volume, gross margin, inventory purchases, staffing, debt, and owner-cash assumptions still work together after you replace national or adjacent benchmarks with local quotes.
How much revenue supports an $84,000 owner income?
The base case needs about $67,778 of monthly revenue, or $813,336 annualized, to support a $7,000 monthly owner target after 20% tax and 10% reinvestment reserves. At $70,000 of monthly sales, modeled owner cash is $7,700. USDA's 2024 horticultural expense table tracks purchased plants, containers, media, labor, utilities, repairs, rent, interest, marketing, and packaging—costs that can absorb higher sales quickly.
Base revenue engine
$840,000 annual sales equals $70,000 per average month.
At a $58 planning ticket, that is about 14,483 transactions per year.
Across 312 open days, the average is roughly 46 transactions per day.
At 45% gross margin, $70,000 of sales creates $31,500 of monthly gross profit.
What the revenue target hides
A nursery rarely sells the same amount every month; spring may carry a disproportionate share.
Peak traffic needs checkout, loading, watering, receiving, and customer-help capacity at the same time.
Wholesale or contractor accounts can raise volume but may lower margin or lengthen receivable timing.
Revenue can grow while owner cash falls if payroll, shrink, or markdowns rise faster.
What gross margin can a garden nursery realistically keep?
A useful retail planning range is 42% to 48% after plant and product costs but before payroll, with 45% used here. It is not a current national garden-center statistic. The UF/IFAS perennial enterprise budget recommends 30% to 40% grower gross margins and warns that labor materially changes profit. Retail markup can lift merchandise margin, but selling labor, shrink, markdowns, and site overhead still reduce owner cash.
One margin point matters
At $840,000 of sales, 1 gross-margin point equals $8,400 of annual gross profit.
Moving from 45% to 42% removes $25,200 before any payroll or rent changes.
A $10 plant that lands at $5.50 direct cost produces 45% gross margin at full price.
If that plant is marked down to $8, gross margin falls to about 31% before labor.
Separate margin from labor
The calculator keeps all payroll in labor cost so the same wage is not counted twice.
Watering, receiving, cashiering, plant care, and customer service belong in payroll.
Track margin by category because trees, annuals, houseplants, pottery, soil, and tools can behave very differently.
Can a garden nursery run without the owner?
Yes, but passive distributions require enough revenue and margin to pay a manager first. May 2025 BLS retail-trade wage data show mean annual pay of about $52,830 for first-line retail supervisors/managers and $37,170 for retail salespersons. With payroll burden, a manager can cost roughly $60,000 or more annually. The base case instead assumes the owner works full time and excludes a manager from the $120,000 employee-payroll budget.
Owner-operated base case
The owner covers buying, pricing, staff direction, customer escalation, and daily cash control.
Employee payroll is $10,000 per month, or $120,000 annually.
The $92,400 owner-income output compensates both owner labor and ownership risk.
Do not add a second $50,000 owner salary on top unless it is also added to payroll cost.
Manager-run test
Add manager wages and payroll burden to labor before calculating distributions.
If manager cash cost is $61,000 a year, base residual owner cash can fall sharply without higher sales.
To replace that cost at 45% gross margin requires roughly $136,000 of added annual sales before reserves.
A passive owner should judge the return after a market-rate manager, not after unpaid owner labor.
How should owner draws change through the seasons?
Owner draws should follow cash availability, not the profit reported after one strong weekend. Texas A&M's bedding-plant crop guide identifies March-June as the main spring selling period, with another fall window, and notes weather risk. Retail nurseries often spend on inventory, labor, freight, and watering before peak receipts arrive.
Use a seasonal cash rule
A planning curve might put 45% of annual sales in March-May and only 15% in December-February; treat that as an assumption, not a national statistic.
On $840,000 annual sales, that example means $378,000 in spring and $126,000 in winter.
Do not distribute the spring bank balance before reserving for fall inventory and winter fixed costs.
Keep owner draws lower when payables and preseason purchase orders are building.
Pay reserves before distributions
The base calculator holds 20% of positive cash profit for taxes and 10% for reinvestment.
Reinvestment cash covers replacement equipment, dead stock, repairs, and the next buying cycle.
Distributions become safer only after these obligations and debt payments remain funded.
Key Takeaways
The base owner-operator model produces about $92,400 of annual owner cash on $840,000 of revenue after modeled reserves.
Cash break-even is near $45,556 per average month, but a $7,000 monthly owner target needs about $67,778.
Gross margin, seasonal sell-through, and non-owner payroll matter more than revenue headlines alone.
A manager-run nursery must add market-rate management payroll before calling the remaining cash a passive distribution.
What do low, base, and high owner-income cases look like?
The scenarios change revenue, margin, labor, overhead, marketing, debt, and reserves together. They are planning cases, not industry averages. The SBA 7(a) program permits eligible uses including working capital, equipment, fixtures, and real estate, and most term loans are repaid through monthly principal-and-interest payments from business cash flow.
Owner income scenarios
Three coherent annualized operating cases using the same calculator presets.
Garden Nursery low, base, and high owner-income planning cases
Scenario factor
Low CaseSlow ramp
Base CaseStabilized
High CaseStrong demand
Launch modelAverage selling pace
$45,000 monthly revenue
$52 ticket assumption
About 865 transactions/month
$70,000 monthly revenue
$58 ticket assumption
About 1,207 transactions/month
$105,000 monthly revenue
$62 ticket assumption
About 1,694 transactions/month
Typical setupOwner and staffing
Owner-heavy coverage
Lean year-round team
Limited peak help
Full-time owner
Two core employees plus seasonal help
No hired general manager
Owner plus lead staff
Broader peak-season coverage
More receiving and loading capacity
Cost driversMargin and cash load
42% gross margin
$7,500 monthly payroll
$9,700 other monthly cash costs
45% gross margin
$10,000 monthly payroll
$10,500 other monthly cash costs
48% gross margin
$16,500 monthly payroll
$14,000 other monthly cash costs
Owner income rangeAfter modeled tax and reinvestment reserves
$14,688
$92,400
$157,608
Best fitWhen the case is credible
New or underscaled nursery with weak traffic, excess inventory, or high fixed-cost pressure.
Established local nursery with repeat customers, disciplined buying, owner-led management, and normal seasonal staffing.
Strong local demand, proven premium mix, high sell-through, added staff capacity, and disciplined working capital.
i
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
How do the six income drivers change cash in practice?
The six drivers below use the same model definitions as the calculator: direct product costs are inside gross margin; employee payroll is separate; the working owner is not in payroll; fixed overhead excludes marketing and debt; and owner income is the residual after modeled tax and reinvestment reserves. Track them together because a higher ticket can be erased by shrink, extra labor, or inventory that does not sell before the season turns.
1. Seasonal sales volume and sell-through
Model peak capacity before the spring rush
The base model needs $840,000 of annual sales. Nursery capacity is the number of customers you can attract, help, ring through, load, and restock while keeping plants saleable. At a $58 ticket, that is about 14,483 annual transactions. If 45% of sales fall in a three-month spring planning window, peak sales rise to about $126,000 per month.
Ten extra daily transactions at a $58 ticket across 90 peak days add about $52,200 of sales and roughly $23,500 of gross profit at 45% margin before added labor and marketing. Use the USDA horticulture sales release only as market context; local traffic counts should drive the forecast.
Track demand as a weekly operating number
Separate traffic, conversion, ticket, and sell-through so you know why revenue moved.
Transactions by day and weather condition
Conversion rate during peak weekends
Sales by category and week
Marketing spend per incremental gross-profit dollar
At 45% margin, the base $1,500 monthly marketing budget needs at least $3,333 of incremental sales just to cover itself before added labor.
2. Gross margin after product cost and shrink
Protect margin before chasing more revenue
At 45% gross margin, $70,000 of monthly sales leaves $31,500 after direct product and growing-material costs. Three margin points on the base $840,000 sales level equal $25,200 of annual gross profit, so margin drift can consume a large share of owner cash.
Price discipline matters because a living product has a clock. The University of Maryland pricing guide shows the cost-plus-margin relationship: selling price must cover direct cost and the desired gross margin. A plant landed at $11 must sell for $20 to generate 45% gross margin. Mark it down to $16 and the margin falls to about 31%, before any labor, occupancy, or watering cost.
Measure realized margin, not sticker margin
Use the point-of-sale system and inventory counts to reconcile what was expected with what actually sold.
Gross margin by plant and hardgoods category
Markdown dollars as a share of sales
Vendor freight and landed cost
Shrink by reason: death, damage, theft, overgrowth
One gross-margin point is worth about $8,400 a year at the base sales level, so modest pricing or shrink improvements can reach owner cash quickly.
3. Average ticket and product mix
Raise basket value without loading the cart with low-margin sales
The $58 base ticket is a planning assumption. It requires about 1,207 monthly transactions to reach $70,000 of revenue. Raising the ticket to $63 at the same volume adds about $6,000 of monthly sales and roughly $2,700 of gross profit at 45% margin before extra labor or marketing.
Product mix matters because categories carry different margins and labor demands. University of Georgia Extension notes that retail garden centers typically require diverse, higher-quality assortments across many sizes and cultivars. Variety can lift the ticket, but it can also create slow-moving inventory.
Track contribution by basket, not units alone
Use basket analysis to see whether add-ons create real gross-profit dollars.
Average transaction value by week
Units per transaction
Gross profit per transaction
Attachment rates for soil, pottery, fertilizer, and delivery
A $5 ticket increase across the base transaction count is worth roughly $72,000 of annual revenue, but the owner only benefits if the added categories preserve margin and do not create excess labor or dead stock.
4. Labor scheduling and the owner's operating role
Price the owner's labor before calling profit passive
Base non-owner labor is $10,000 per month, while the owner works full time. The $7,700 monthly owner output therefore compensates both labor and ownership. For a manager-run nursery, add market-rate management payroll first. BLS 2025 retail wage data put mean retail-supervisor pay near $52,830 before employer burden and benefits.
Labor should also rise in the high case. That is why the $105,000 monthly revenue preset carries $16,500 of payroll instead of leaving base staffing unchanged. The high case still produces more owner cash because the larger gross-profit pool more than covers the added staff. Conversely, if spring staffing is kept too lean, service bottlenecks can reduce conversion and damage plants, so cutting payroll can be self-defeating.
Schedule labor against sales and task load
Separate selling hours from plant-care, receiving, delivery, and maintenance work.
Payroll as a share of sales
Sales and gross profit per labor hour
Peak-week overtime and temporary labor
Owner hours replacing paid management
If a manager adds about $61,000 of annual loaded cash cost, the nursery needs roughly $136,000 of added sales at 45% margin just to replace that cost before reserves.
5. Inventory turns, shrink, and working capital
Treat unsold plants as cash still at risk
At 45% gross margin, direct product and material cost is 55% of sales, or about $38,500 in an average month. Inventory is usually purchased ahead of sales, so spring buying can drain cash weeks before customers arrive. USDA's 2024 horticultural expense data separately tracks purchased plants, media, containers, labor, rent, marketing, and other cash uses around inventory.
Shrink makes the timing problem worse. The UF perennial study used a 10% shrink assumption to account for production loss. For a retail nursery, use 10% as a stress test rather than a benchmark: if $100,000 of seasonally sensitive inventory loses 10% of cost value to death, damage, or unsellable overgrowth, $10,000 of cash disappears before counting the lost markup.
Build a buying-to-cash dashboard
Inventory discipline protects both margin and liquidity.
Inventory dollars by age bucket
Sell-through by delivery and category
Shrink at cost and at retail value
Weeks of inventory before each selling season
Do not treat a profitable spring P&L as distributable cash until supplier payables, next-season purchase orders, and a winter fixed-cost reserve are funded.
6. Fixed overhead, debt, and compliance load
Keep the unavoidable monthly burden below normal gross profit
The base model carries $6,500 of fixed overhead, $2,500 of debt service, $1,500 of marketing, and $10,000 of employee labor each month. At 45% gross margin, the resulting $20,500 cash burden creates break-even near $45,556 of monthly revenue before owner reserves or pay. More debt and occupancy cost leave less room for weak weather or traffic.
Compliance can also create real labor and process cost for nurseries that grow plants and use agricultural pesticides. The EPA's nursery and greenhouse guidance states that the Worker Protection Standard applies to covered nurseries and greenhouses and requires worker protections, training, and exposure mitigations. These are not reasons to avoid production; they are reasons to budget time, training, PPE, recordkeeping, and operating controls instead of treating compliance as free.
Track the fixed-cost coverage ratio every month
Know how much gross profit remains after commitments that cannot be postponed.
Fixed overhead plus debt as a share of sales
Monthly break-even revenue
Debt-service coverage from operating cash
Cash reserve measured in months of fixed commitments
Owner distributions should be the last cash use in the chain. Once vendors, payroll, debt, taxes, compliance, inventory, repairs, and a reinvestment reserve are covered, the remaining cash is far more defensible as owner income.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.