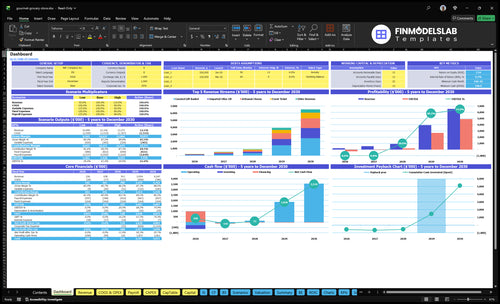
How Much Gourmet Grocery Store Owners Make: $778K Modeled Year 1
Gourmet Grocery Store Bundle
A gourmet grocery store owner can make strong income only when sales volume, gross margin, labor, rent, shrink, and reinvestment are tightly managed In the researched first-year case, modeled revenue is about $125M, gross margin after cost of goods sold is 85%, and visible operating cash before owner taxes and reserves is about $778K That figure is a planning assumption, not a salary promise It excludes taxes, debt service, owner living expenses, reserves, and any payroll not shown in the provided data
Owner income-$279k to $4.9MNet margin-22% to 13%Revenue for target pay$520kBusiness difficultyHard
Want To See What Really Drives Owner Income?
1
Sales Volume
$125K
More visitors and higher conversion lift revenue fastest, so this is the biggest cash driver.
2
Mix Margin
85%
Cheese, oil, chocolate, baskets, and tickets shape gross margin, and every mix shift moves take-home.
3
Labor Efficiency
$70K
The manager salary is the anchor, and staffing has to stay tight so labor does not outrun sales.
4
Lease Load
$164K
Lease size and site economics lock in fixed cost, and square footage is not provided so keep it editable.
5
Variable Costs
4%
Payment fees and promo spend can quietly drain cash, and shrink rate is not provided so keep it editable.
6
Owner Policy
$778K
Draw, debt service, and reserve policy decide what the owner keeps, so those inputs should stay editable.
Want To Test Your Owner Pay?
Owner income calculator
Estimate owner take-home and target-pay gap from revenue, margin, costs, reserves, and target pay.
!
Planning note: This is a researched planning estimate, not guaranteed salary, tax advice, or owner distribution advice.
Want to stress-test owner pay in a Gourmet Grocery Store model?
How Much Revenue Does A Gourmet Grocery Store Need To Pay The Owner?
If you’re asking what a Gourmet Grocery Store needs to bring in to pay the owner, the key point is that break-even is not owner pay. With 81% contribution margin after 15% COGS and 4% variable costs, the visible break-even revenue is about $289K, but real owner compensation needs more room for pay, reserves, debt service, taxes, and full staffing.
Break-even
81% contribution margin
About $289K visible break-even
Covers fixed costs and manager cost
Not safe owner income
Owner pay
Add owner salary to fixed costs
Include reserves and debt service
Taxes lift the revenue threshold
Full staffing raises the bar
How Does Owner-Operated Income Compare With Absentee Owner Income?
For the Gourmet Grocery Store, owner-operated cash can look about $70K higher if the owner replaces the included store manager role, but that is pay for work, not pure profit. An absentee owner usually needs more paid supervision and tighter inventory controls, and if staffing is thin, shrink risk, vendor buying, and customer experience can slip. So the key question is whether the owner is saving salary or just taking a different job.
Owner-run cash
$70K manager salary can shift
Owner labor is still a cost
Cash may rise, profit may not
Service stays closer to the floor
Absentee tradeoffs
Needs more paid supervision
Needs tighter inventory controls
Weak staffing can lift shrink
Vendor buying can lose edge
Can A Gourmet Grocery Store Owner Make A Living?
Yes, a Gourmet Grocery Store owner can make a living, but only after repeat sales cover rent, payroll, inventory, and cash reserves; the first-year model shows about $1.25M revenue and about $77.8K operating cash before owner taxes, reserves, debt, and missing payroll lines. That’s why What Is The Main Goal For Gourmet Grocery Store? is repeat local demand, not just premium foot traffic.
Owner Math
Model revenue: $1.25M year one
Operating cash: $77.8K before owner taxes
Visible fixed costs: $164.4K per year
Store manager cost: about $70K
Pay Timing
Pay owner after reserves stabilize
Count owner shifts as real payroll
Protect cash before debt payments
Delay salary if demand ramps slowly
Key Takeaways
Sales need traffic and basket size to cover fixed costs.
A 1-point margin gain adds about $125K first-year cash.
Manager pay is real cost; owner labor is not profit.
Rent, shrink, and weak repeat demand can drain cash.
Compare Low, Base, And High Gourmet Grocery Income Scenarios
Owner income scenarios
Owner income moves with traffic, repeat buys, and basket mix. Year 1 stays under pressure, Year 3 reaches scale, and Year 5 shows the mature case.
Compare low, base, and high owner income paths.
Scenario
Low CaseLow Case
Base CaseBase Case
High CaseHigh Case
Launch model
The store is still in the Year 1 ramp, so owner income stays negative while traffic and repeat buying build.
Year 3 scale lifts owner income as traffic, repeat purchase, and basket size all move up.
Year 5 maturity pushes owner income up as peak traffic, larger baskets, and a richer mix raise sales.
Typical setup
Use Year 1 traffic, 15% visitor-to-buyer conversion, 30% repeat customers, 2 units per order, and the full lease and wage load.
Use Year 3 traffic, 19% conversion, 40% repeat customers, 2 units per order, and a better mix from gift baskets and events.
Use Year 5 traffic, 23% conversion, 50% repeat customers, 3 units per order, and the strongest gift-basket and event mix.
Cost drivers
Year 1 traffic ramp
15% conversion
30% repeat share
12% specialty food COGS
2 units per order
Year 3 traffic growth
19% conversion
40% repeat share
11% specialty food COGS
2 units per order
Year 5 peak traffic
23% conversion
50% repeat share
3 units per order
richer gift-basket and event mix
Owner income rangeBefore owner reserves
-$279,000Low Case
$182,000Base Case
$4,907,000High Case
Best fit
Fits founders stress-testing the early operating ramp and slower-than-planned store traffic.
Fits the core plan most operators should underwrite for budgeting and hiring.
Fits upside planning for owners testing what a mature store can produce at full traction.
!
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distributions. They exclude taxes, debt, reserves, shrink, square-foot limits, and missing payroll.
Gourmet Grocery Store Core Six Income Drivers
Sales Productivity
Sales Productivity
Sales productivity is the store’s ability to turn 30,160 annual visitors into paying baskets that cover premium inventory, staff, and rent. At 15% conversion, that’s about 4,524 orders a year, or 86 orders a week. With 2 units per order, basket size has to stay strong or owner pay gets squeezed.
The repeat base is still thin: 30% repeat customers, 6-month lifetime, and 1 repeat order per month. That means cash flow will swing with seasonality and weak repeat demand. Sales per square foot cannot be calculated because store size is not provided, so traffic, conversion, and basket size are the real watchpoints.
Measure Traffic and Basket Size
Track weekly visitors, conversion rate, units per order, and repeat share every week. If traffic holds but conversion drops, service, pricing, or product mix needs work. If conversion holds but basket size falls, train staff to add the second item, not just the first.
Weekly visitors
Conversion rate
Units per order
Repeat share and lifetime
Watch repeat demand by cohort, not just total sales. If the 30% repeat share does not hold past the first 6 months, owner draws will depend on new traffic every week, which is risky for a seasonal grocery. Keep the model editable so profit and take-home cash reflect real demand.
Gross Margin And Product Mix
Gross Margin Mix
The owner’s take-home rises when the store keeps COGS at 15% in year one and protects that margin mix. The planned mix is 30% artisanal cheese, 25% imported olive oil, 20% gourmet chocolate, 15% curated gift baskets, and 10% event tickets. That blend matters because each 1 margin point changes first-year cash by about $125K.
Here’s the quick math: higher-margin packaged goods and tickets help fund lower-margin perishables, but waste can erase the gain fast. What this estimate hides is spoilage, slow-moving imports, and supplier cost pressure. By Year 5, COGS falls to 12%, so the owner keeps more gross profit only if stock turns fast and markdowns stay tight.
Track Mix and Waste
Watch gross margin by category, not just total sales. Track category mix, sell-through, spoilage, and import cost changes each week so you can see which items pay rent and payroll. If cheese or chocolate sits too long, the posted margin is fake and owner pay drops even when revenue looks fine.
Use these inputs in the model: sales mix, COGS, waste, and supplier pricing. Push more of the mix into shelf-stable, premium items and event tickets when perishables slow down. One clean rule helps: protect the margin first, then grow volume.
Track margin by SKU
Cut slow-moving imports
Price baskets for waste
Review supplier cost changes
Owner Salary Versus Profit
Owner Salary Versus Profit
Owner salary is pay for work, while distributions are profit paid out. Reserves are cash kept in the store, and debt service is loan repayment. The first-year model shows about $778K before owner taxes, reserves, debt, and missing payroll lines, so that number is not the same as safe take-home.
Cash can get tied up fast in seasonal buying, equipment, inventory growth, and expansion. If the reserve policy gets stricter, near-term owner draws fall, but the store is safer. The key inputs are pretax profit, payroll, debt payments, reserve target, and working capital needs. One clean rule: profit on paper is not cash in hand.
Protect Draws With Cash Rules
Track three lines every month: owner pay, reserve build, and distribution capacity. Keep the model editable for missing payroll and debt service so draws do not come from guesswork. If inventory or expansion spend rises, trim distributions first, not cash controls.
Use a simple draw test: only pay distributions after funding reserves and known obligations. That keeps the store from funding owner income with money needed for stock or equipment. In this model, the right question is not “how much profit exists?” but “how much cash is still free after obligations?”
Separate salary from profit draws.
Fund reserves before distributions.
Keep debt service visible each month.
Model inventory growth as cash use.
Labor Efficiency
Labor Efficiency
Staffing drives owner income because it pays for checkout coverage, receiving, stocking, product knowledge, tastings, and customer service. This model includes a store manager at $70K per year in each model year. If the owner replaces that role, cash can improve by $70K, but the owner has still bought a full-time job.
The key inputs are paid hours, manager pay, owner hours, and service level. Unpaid owner labor should not be treated as true profit. If the store runs too lean, checkout slows, shelves slip, and service quality falls, which can hurt repeat sales. Missing payroll lines should stay editable so the model shows the real labor load.
Track labor by task
Split labor into checkout, receiving, stocking, tastings, and floor help. Compare paid hours to traffic and basket size, then test the leanest schedule that still keeps shelves full and service fast. One clean rule: if guests wait or stock looks thin, labor is too tight.
Track manager hours separately
Log owner hours as payroll
Review service gaps weekly
Keep payroll lines editable
Build owner pay from after-payroll cash, not from free labor. If the owner covers manager duties, treat that labor as a salary substitute in the model. That keeps cash flow, profit, and take-home pay from looking stronger than they are.
Shrink And Inventory Turnover
Shrink And Inventory Turnover
Shrink is inventory lost to spoilage, damage, theft, expiration, or counting errors. In this store, that hits imported oils, specialty chocolate, cheese, and gift basket parts first, so reported sales can look fine while gross profit quietly falls. If shrink is not set as an editable cost line, owner pay gets overstated and cash tied up in stock gets missed.
Here’s the quick math: inventory turnover = COGS ÷ average inventory. Lower turnover means more cash sitting on shelves and more risk that the owner is funding displays, events, or seasonal buys out of pocket. That can delay draws, raise write-offs, and make the business look healthier than it is on paper.
Tighten Counts And Buying
Track purchases, counted stock, write-offs, and average inventory every week. Separate shrink by cause: spoilage, damage, theft, and count errors. Use that data to set reorder points for slow movers, especially gift basket components and imported specialty items, so you buy for demand, not for a full display.
Test smaller buys before seasonal pushes and events. If a product sells slowly, cut the next order even if revenue is strong, because cash tied in dead stock cannot pay rent, payroll, or the owner. The goal is simple: keep turnover up and shrink down so more gross profit reaches take-home income.
Rent And Location Economics
Rent Must Follow Sales
The lease is $10K per month, or $120K per year, so location has to earn its keep. In a gourmet grocery store, a better site can lift traffic, basket size, and repeat visits, but only if the area supports premium pricing and weekly repeat purchases.
The model already shows $1.644M in visible fixed operating costs before manager salary, so rent sits inside a very heavy fixed base. A cheaper site is not automatically better if it cuts parking, access, or walk-in traffic. The real risk is signing the lease before proving demand and basket size.
Test Traffic Before You Lock Rent
Track weekly visitors, conversion rate, average order size, and repeat purchase rate before you commit. Here’s the quick math: rent only works if sales productivity covers the lease plus the rest of the fixed base. If the trade area cannot support premium pricing, the store will struggle to pay the owner.
Measure walk-ins by week.
Check parking and access.
Test repeat buys early.
Compare rent to gross sales.
If a site gets decent traffic but weak repeat visits, the location is expensive in disguise. A stronger neighborhood is worth more only when it supports full-price sales and regular reorders, not just one-time curiosity.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.