Handwriting Analysis Owner Income: Year 5 Profit Near $168K
Handwriting Analysis Service Bundle
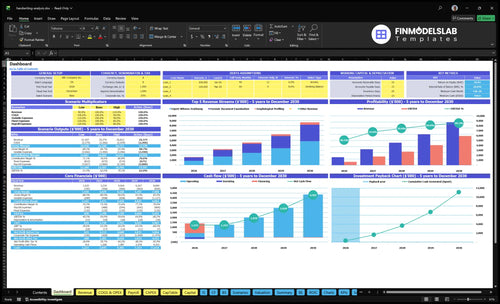
You’re selling expertise, not a fixed paycheck, so owner income depends on paid case volume, hourly pricing, testimony work, and overhead Under researched staffed assumptions, Year 1 revenue is about $271k with about -$305k operating profit, while the mature year reaches about $126M revenue and $168k operating profit before taxes, reserves, debt service, and owner distributions
Owner income$0 to $168kNet margin73% to 80%Revenue for target pay$226k to $105kBusiness difficultyHard
Want to test your owner pay?
Owner income calculator
Estimate owner take-home and the target-pay gap from revenue, margin, costs, reserves, and target pay.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice. If CAC stays near $850 and case volume runs below break-even, owner pay tightens fast.
Want the six drivers that matter most?
1
Case Volume
55-169/mo
More assignments drive the whole model; the plan rises from about 55 paid cases a month in Year 1 to 169 in the mature year, so volume is the biggest revenue lever.
2
Case Fee
$41K-$62K
Higher fees lift revenue without the same jump in case count; the modeled average case value rises from about $41K to $62K, so pricing and case complexity matter.
3
Expert Add-Ons
$450-$550
Court work pays the highest hourly rate; expert witness testimony runs from $450 to $550 an hour, and a few hearing days can move monthly income fast.
4
Service Mix
65%-75%
A stronger share of forensic work improves credibility and keeps the best-paying cases flowing; the mix shifts from 65% to 75% forensic document work, which supports take-home.
5
Analyst Capacity
1-3 FTE
More full-time analysts speed review and protect turnaround; as staffing rises, you can keep more work moving without bottlenecks or overtime loss.
6
Overhead Control
$11.25K/mo
Fixed overhead is the cash floor; monthly overhead is $11.25K, so reserve discipline helps protect income when collections slow.
Want to see the full Handwriting Analysis Service model?
What margins should a handwriting analysis business expect?
Gross margins look attractive for a Handwriting Analysis Service, but owner income can still be thin; for setup steps, see How To Launch Handwriting Analysis Service Business?. Year 1 variable costs are 27% of revenue, so gross margin is 73%; in the mature year, variable costs fall to 20%, lifting gross margin to 80%.
Gross margin math
27% variable costs in Year 1
73% gross margin in Year 1
20% variable costs mature year
80% gross margin mature year
Cost pressure points
$11,250/month fixed overhead
Marketing rises $45k to $85k
Capex includes $57k for equipment
Separate case costs from overhead
Can a handwriting analysis business scale beyond the owner?
Yes, a Handwriting Analysis Service can scale beyond the owner, but only if the work is standardized and tightly reviewed. In the mature year, staffing grows from 1 junior analyst to 3 and from 1 case manager to 2, while average billable hours per active customer rise from 85 to 105 per month. Testimony can bring premium revenue, but it also adds calendar risk, and owner review time plus credential scrutiny can cap growth.
How it scales
Standardize intake from day one
Use report templates for repeat work
Keep evidence workflows secure
Shift routine cases to juniors
What slows it
Owner review time becomes a bottleneck
Testimony blocks the calendar
Credential checks can slow sales
Quality slips when volume outruns control
How many handwriting analysis cases per month do I need?
You need about 14 modeled assignments per month to break even before owner distributions; for owner draw, plan above that. In What Does It Cost To Run A Handwriting Analysis Service?, Year 1 demand is 66 assignments/year, or 5.5/month, while mature volume reaches 203/year, or 16.9/month. The target moves with average fee, case mix, and fixed costs.
Case target
Break-even: 14/month
Year 1: 66/year
Year 1 monthly: 5.5/month
Mature volume: 16.9/month
Main levers
Marketing budget: $45,000
Customer acquisition cost: $850
Expert testimony: $6,750–$11,000
Owner draw needs extra cases
Key Takeaways
Paid cases drive revenue; vanity traffic does not pay.
Higher fees come from stronger credentials and complex cases.
Testimony lifts revenue, but capacity becomes less predictable.
Overhead and reserves protect owner pay and runway.
Compare lean, base, and mature owner-income scenarios
Owner income scenarios
Owner income here moves with case volume, billable hours, and overhead. The three cases show early losses, a growth gap, and when scale can turn profit.
Three planning views of owner income.
Scenario
Lean CaseEarly loss
Base CaseGrowth gap
Mature CaseProfit at scale
Launch model
The lean case keeps volume small and still runs at a loss.
The base case models a fuller operating year but still comes up short.
The mature case assumes stronger volume and turns profitable before taxes and reserves.
Typical setup
Year 1 assumptions keep revenue near $271k, gross margin at 73%, and volume at 55 assignments a month, but payroll, marketing, and fixed overhead still drive a loss.
Year 3 assumptions lift revenue to about $606k, gross margin to 77%, and volume to 101 assignments a month, yet the $685k overhead base still leaves a loss.
Year 5 assumptions push revenue to about $1.26M, gross margin to 80%, and volume to 169 assignments a month, and the $840k overhead base can support profit.
Cost drivers
Low case volume
fixed payroll
marketing spend
lab overhead
security and software
Case volume
billable hours
staffing scale
marketing
travel and referral fees
Higher case volume
stronger pricing
more analyst FTEs
overhead spread
court travel
Owner income rangeBefore owner reserves
-$305kEarly loss
-$218kGrowth gap
$168kProfit at scale
Best fit
Use this to test a small launch where cash stays tight and owner pay is not reliable.
Use this for Year 3 planning and to see how long the growth gap lasts.
Use this to test what steady case flow and better pricing can pay the owner.
!
Planning note: Scenario ranges are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distributions.
Handwriting Analysis Service Core Six Income Drivers
Paid Case Volume
Paid Case Volume
Paid case volume is the number of qualified leads that turn into paid reports, consultations, and verification cases. The model points to 53 customers in Year 1 from $45k spend at $850 CAC and 131 customers in a mature year from $85k spend at $650 CAC. That lifts assignments from about 66 to 203 per year, so owner income rises only if each case clears its delivery cost.
The risk is vanity traffic that never becomes paid legal or verification work. More cases can lift revenue fast, but it also raises report writing, review time, and owner oversight, so profit can stall if capacity does not grow with demand.
Track Conversions, Not Traffic
Track leads, qualified leads, close rate, CAC (customer acquisition cost), and completed cases. If $45k of spend buys 53 customers, every channel has to prove it can convert into paid work. The key test is simple: how many inquiries become paid cases, and how many hours does each case take.
Measure lead-to-paid conversion weekly.
Compare CAC to case value.
Cut weak traffic sources fast.
Staff for case volume, not clicks.
If case volume rises faster than review capacity, turnaround slips and owner pay gets squeezed. Build the forecast from paid cases first, then add analyst hours, admin support, and owner time so growth turns into usable profit, not just more work.
Service Mix And Credibility
Service Mix And Credibility
When more work shifts into forensic verification and litigation support, each case can carry a bigger ticket. In the research set, forensic mix rises from 65% to 75%, testimony from 40% to 50%, and profiling from 20% to 30%. That matters because forensic assignments run about $3,300 to $4,620, while profiling is only about $1,350 to $2,240.
Credibility drives attorney referrals, report pricing, and conversion. Here’s the quick math: testimony at $450 to $550 an hour for 15 to 20 hours is about $6,750 to $11,000 before variable cost. If the owner overstates scientific or legal claims, conversion risk rises and price power falls. Chain of custody, credentials, and report quality have to support the fee.
Raise the Share of Higher-Ticket Work
Track revenue by service line, not just case count. Watch forensic share, testimony share, and profiling share each month, plus referral source, close rate, and average revenue per assignment. If profiling starts taking more time than it earns, the mix is drifting toward lower-value work. One clean rule: price the report to match the proof.
Test pricing against proof. Strong credentials, clean chain of custody, and tight report writing let you defend higher fees and lower discounting. If a case needs court use, build in testimony time up front, since 15 to 20 billable hours can add $6,750 to $11,000. That protects margin and keeps owner pay tied to better cases.
Expert Witness Add-Ons
Expert Witness Add-Ons
Qualified testimony can lift owner income fast because it prices on court time, not just report time. At $450 to $550 per hour and 15 to 20 billable hours per assignment, one case can bring in about $6,750 to $11,000 before variable costs. That makes each win more valuable, but the work is less predictable than standard document review.
If testimony mix rises from 40% to 50%, revenue per client should improve, but capacity can tighten. Court dates, prep time, travel, credential review, and case delays can push out other billable work, so the owner’s take-home depends on how many hours stay usable after testimony prep. One delayed hearing can stall cash flow.
Track Testimony Hours
Measure hourly rate, billable hours per case, prep hours, travel time, and collection timing. Here’s the quick math: rate × 15 to 20 hours sets gross revenue, but owner pay only improves if prep and court time do not crowd out paid casework. Track realized margin by case type, not just total receipts.
To improve this driver, pre-qualify cases that need testimony, price travel and rush work separately, and forecast court dates into the schedule before accepting new files. If testimony work starts pushing out ordinary assignments, revenue may look stronger while cash flow gets choppier. Keep a log of canceled, delayed, and rescheduled matters so the mix stays profitable.
Overhead And Reserve Discipline
Overhead And Reserve Discipline
Strong revenue does not equal owner pay. Fixed overhead is $11,250 a month for lease, insurance, software, security, accreditation, admin, and utilities. If variable costs drop from 27% to 20% of revenue, every $100,000 sold keeps $7,000 more in cash before tax and owner draw.
Reserves still reduce distributable cash even when operating profit is positive. So the owner should treat reserves as a real cash use, not spare profit. One clean rule: pay the owner only after fixed overhead, variable costs, and reserve funding are covered for the month.
Protect Owner Draw
Track a monthly cash bridge: revenue, variable cost rate, fixed overhead, reserve deposit, and owner draw. If the reserve target is too loose, the business can look healthy on paper and still leave the owner short when cases slow or payment timing slips.
Watch monthly cash after reserves.
Test draw from free cash only.
Hold overhead under $11,250.
Push variable cost toward 20%.
Capacity And Turnaround
Capacity And Turnaround
Faster turnaround matters when it raises completed cases without adding rework. Profiling can take 6 service hours and mature-year testimony can take 20, so case mix drives throughput. If billable hours per active customer rise from 85 to 105 a month, the owner can bill more work and stop being the only bottleneck, but only if quality and admissibility stay intact.
Track Hours, Not Just Cases
Track intake, analysis, review, and final-report time, plus rework and subcontracted share. Those inputs show whether faster work creates more monthly revenue or just more supervision. Hire junior analysts, case managers, and admin support before the owner becomes the choke point. If you subcontract, budget extra review time so speed does not cut margin or weaken the report.
Track hours by case stage.
Watch rework and review time.
Staff admin before the owner.
Average Revenue Per Assignment
Average Revenue Per Assignment
This is the fee earned on each case, and it moves owner income fast because the work has high gross margin. Research puts average assignment revenue at about $41k in Year 1 and $62k in the mature year. Forensic assignments run about $3,300 to $4,620, while profiling runs about $1,350 to $2,240.
The main inputs are case complexity, number of questioned documents, report depth, and credential strength. With 73% to 80% gross margin, a $1,000 pricing gain can add about $730 to $800 in gross profit before fixed overhead. The risk is pricing above the trust level the market gives you, which can cut conversion and hurt cash flow.
Price for complexity, not just time
Track average fee by case type, document count, and report scope. Split forensic work from profiling, then watch revenue per assignment, gross margin, and close rate together. If higher-complexity work does not raise fee, you are leaving margin on the table. Each stronger case should also support owner pay after analyst labor.
Quote higher fees for more documents
Charge more for deeper reports
Price court-ready work above profiling
Test close rate after every price lift
Keep fees aligned with credentials
Use the fee floor that your proof can support. Multiple questioned documents, stronger credentials, and clearer report quality should justify the price. If pricing rises but win rate falls, the higher ticket is not helping income. The cleanest path is to raise fees where trust already exists, then protect margin with tight scope control.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.