Does Owner Income in a Hot Pot Restaurant Depend More on Volume or Margin?
Hot Pot Restaurant Bundle
A realistic stabilized target for an owner-operated U.S. hot pot restaurant is about $148,200 a year of owner income in the base case, with modeled low and high cases of $22,500 and $233,640. The scope is one independent, roughly 90-seat, all-you-can-eat restaurant in a mid-cost suburban market at $150,000 monthly revenue, a $34 blended check, and about 145 covers a day. Base costs use a 66% gross margin, $44,000 employee payroll before owner pay, $27,000 fixed overhead, $3,000 marketing, and $6,000 debt service. The owner works as GM, so owner wage is excluded from payroll. The $148,200 is after modeled 25% tax and 10% reinvestment reserves; it is not guaranteed salary, passive income, GAAP net income, or automatically safe to distribute.
Owner income$148KNet margin8%Revenue for target pay$1.80MBusiness difficultyHard
What can a hot pot owner-income model realistically support?
Restaurant-sector data sets the guardrails. In 2024, full-service respondents in the National Restaurant Association food-cost analysis reported 32.0% median food and non-alcohol beverage cost, while its labor-cost analysis reported 36.5% median wages and benefits and 34.2% for profitable respondents. The base model uses 34% non-labor direct cost, including a small planning allowance above food cost, with employee payroll separate. The owner-GM is excluded from laborCost so owner compensation is not counted twice.
This calculator is a cash-planning bridge, not an accounting income statement. Revenue is guest sales; gross profit is sales after non-labor direct costs. “Profit before reserves” is cash after employee labor, fixed overhead, marketing, and debt service, so it is not EBITDA. Accounting profit can also reflect depreciation, taxes, and accrual items. Owner salary pays for work; a draw or distribution transfers equity cash. Safe distributable cash comes only after operations, debt, tax reserve, reinvestment, and working capital.
Owner income calculator
Adjust hot pot sales, margins, staffing, overhead, financing, reserves, and target pay to estimate owner take-home.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
What drives hot pot restaurant owner income most?
Hot pot combines full-service prime-cost pressure with long table occupancy and customer-controlled ingredient use. The National Restaurant Association's 2025 operations commentary reported a 2.8% median income-before-tax margin for full-service respondents in 2024, so sales alone do not determine owner income. These six levers drive the 90-seat model.
1
Covers and table turns
145 covers/day
The base case needs roughly 4,400 monthly guests. Empty tables and long dwell times cut revenue before most fixed costs move.
2
Average check and mix
$34 blended check
Lunch, dinner, beverages, add-ons, and group mix determine how much revenue each occupied seat produces.
3
Food cost and AYCE waste
34% direct cost
The base margin assumes ingredient and other direct costs stay controlled despite unlimited servings and premium proteins.
4
Labor productivity
$44K/month
Employee payroll is about 29% of base sales before owner pay; adding a hired GM materially lowers residual owner cash.
5
Repeat demand and acquisition
$3K/month
Local marketing must create enough first visits and repeat covers to pay back before discounts train guests to wait for deals.
6
Occupancy, utilities, and debt
$33K/month
Base fixed overhead plus debt service is $33,000 before a single owner distribution, so lease and financing terms matter every month.
Want to test covers, checks, and owner pay in a full forecast?
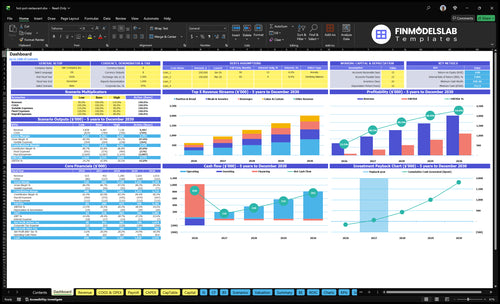
The Hot Pot Restaurant Financial Model Template in Excel lets you test guest volume, pricing, food cost, payroll, debt, cash runway, and owner income over time. The dashboard helps show whether a profitable year can still contain weak cash months during ramp-up, repairs, or seasonal softness.
How many covers does a hot pot restaurant need to pay the owner?
In this model, the answer is roughly 145 covers a day at a $34 blended check to reach the $150,000 monthly base revenue, and slightly more revenue—$150,350 a month—to support a $12,500 monthly owner-pay target after reserves. That check is a planning average, not a national hot pot benchmark. For a real market anchor, an official KPOT Webster, Texas menu lists $21.99 adult lunch, $33.99 adult dinner, and a two-hour dine-in limit; beverages, taxes, and location differences can move the realized check.
For 90 seats, 145 daily covers equal about 1.6 average daily turns, but daypart matters more than the all-day average. Base monthly covers are about 4,412. Ten extra covers per day add about $10,336 monthly revenue at a $34 check and about $6,822 gross profit at a 66% gross margin before incremental labor.
Cover math to monitor
Base: about 4,412 covers per month
Base: about 145 covers per day
90 seats: about 1.6 average daily turns
Track lunch, dinner, weekday, and weekend separately
What the average hides
A two-hour table on Saturday has a different value from an empty Tuesday lunch table
Group size changes seat utilization
Wait times can coexist with unused single seats
Promotions can raise covers while lowering check and margin
What margin makes hot pot owner take-home sustainable?
A hot pot restaurant can feel busy and still have little distributable cash. The National Restaurant Association's 2024 operating results show full-service respondents at only 2.8% median income before taxes, and its occupancy-cost analysis puts median full-service occupancy at 5.7% of sales. The base case here is intentionally stronger than the median because it assumes an owner-operated, stabilized location with controlled food waste, but it still requires enough room for debt service and reserves.
At $150,000 monthly sales and a 66% gross margin, gross profit is $99,000. Modeled labor, overhead, marketing, and debt total $80,000, leaving $19,000 before reserves and $12,350 after the 25% tax and 10% reinvestment reserves. Static operating break-even is about $121,212 a month. Supporting the $12,500 monthly owner-pay target requires about $150,350 a month, or $1.80 million annualized.
Profit layers
Revenue: $150,000 per base month
Gross profit: $99,000 after direct costs
Cash profit before reserves: $19,000
Owner income after modeled reserves: $12,350
Do not mix these labels
EBITDA is not the same as cash after loan payments
Accounting profit is not the same as a bank balance
Owner salary pays for work performed
Owner draws should come from residual cash, not unpaid bills
Can a hot pot restaurant run without the owner?
Yes, but the economics change because a manager is a real operating cost. The BLS Food Service Managers profile reports a $65,310 national median annual wage in May 2024 and $63,040 for food service and drinking places. The base calculator deliberately removes the owner-GM from labor so owner income does not get counted twice. If the owner steps away, add the replacement manager to laborCost rather than pretending the same distribution remains available.
At $63,040, a replacement manager is about $5,253 a month before payroll taxes, benefits, or bonuses. With the model's 35% combined reserve rate, that wage alone reduces annual owner income by about $41,000 after reserves. The BLS cooks profile puts the May 2024 median for restaurant cooks at $17.71 an hour. Guest cooking reduces some line work, but prep, slicing, receiving, dish, sanitation, hosting, bussing, and service remain.
Owner-operated case
Owner acts as GM
Owner wage is reclassified out of laborCost
Residual income includes compensation for owner work
Do not describe the full amount as passive profit
Manager-run case
Add a market-rate GM and payroll burden
Keep owner distributions separate from payroll
Require stronger sales or lower other costs
Track owner hours so “profit” is not free labor
How do debt, taxes, and reserves change the owner's draw?
Debt can turn a profitable restaurant into a low-cash restaurant. The base model deducts $6,000 monthly before owner reserves. Current SBA 7(a) guidance says rates are negotiated subject to SBA maximums and many non-real-estate terms are ten years or less, so use the actual lender payment. Removing $6,000 of debt lowers target-pay revenue by about $9,091 a month and raises modeled annual owner income by about $46,800 after reserves.
The 25% tax reserve is a planning buffer, not a tax rate. The IRS estimated-tax guidance notes that sole proprietors, partners, and S corporation shareholders may need estimated payments. Reinvestment also matters because refrigeration, ventilation, tabletop systems, dish equipment, furniture, and smallwares wear out. A distribution is safe only when payroll, sales-tax remittance, vendors, repairs, and the next debt payment remain funded.
Cash before owner draw
Pay vendors and employee payroll
Pay occupancy, utilities, insurance, and marketing
Make principal-and-interest debt payments
Fund tax, repair, and working-capital reserves
Owner-pay policy
Set a market value for the owner's operating role
Treat extra distributions as variable
Use trailing cash flow, not one strong weekend
Pause draws when reserves fall below the operating floor
Key Takeaways
The base owner-operated model produces $148,200 annual owner income after modeled tax and reinvestment reserves on $1.80 million annual sales.
Static operating break-even is about $121,212 monthly sales, but supporting a $12,500 monthly owner-pay target requires about $150,350.
Owner income is not passive profit when the owner is also the general manager; a replacement manager materially lowers distributions unless revenue rises.
Covers, check size, food waste, labor productivity, repeat demand, and fixed financing burden should be reviewed together because improving one metric can worsen another.
How do low, base, and high hot pot income scenarios compare?
All three cases use the same 90-seat owner-operated format, but costs rise with volume. Annual sales move from $1.32 million to $1.80 million to $2.82 million while labor, overhead, marketing, and debt also increase. The direction is consistent with the National Restaurant Association's 2024 volume analysis, which found 31.0% median food cost for full-service respondents at $2 million or more versus 33.7% below $2 million.
Owner income scenarios
Low, base, and high cases reconcile to the calculator presets and show owner income after modeled tax and reinvestment reserves.
Hot Pot Restaurant low, base, and high owner-income planning cases.
Scenario
Low CaseDownside
Base CaseBase
High CaseUpside
Launch modelDemand path
About 117 covers per day at a $31 blended check; slower demand keeps owner cash thin.
About 145 covers per day at a $34 blended check; stabilized owner-operated target.
About 209 covers per day at a $37 blended check; stronger turns require more staff and support cost.
Owner income rangeAfter tax + reinvestment reserves
$22,500
Annual owner income after modeled reserves.
$148,200
Annual owner income after modeled reserves.
$233,640
Annual owner income after modeled reserves.
Best fitPlanning use
Use to test a soft launch, weak weekday demand, and limited distribution capacity.
Use for a stabilized owner-operated restaurant in a mid-cost suburban market.
Use to test high utilization with the extra labor, marketing, overhead, and financing needed to support it.
!
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
Six income drivers to track in a hot pot restaurant
The six drivers below are the same six levers used in the compact ranking, expanded into operating decisions. They matter because hot pot combines fixed dining-room capacity with variable ingredient consumption, service labor, and a cash-heavy equipment base. The goal is not to maximize one metric; it is to protect owner cash after all six interact.
1. Covers and table turns
Protect revenue per seat-hour, not just headcount
The base model needs about 4,412 covers a month, or 145 a day, at a $34 blended check. The operating issue is table time: the official KPOT Webster menu cited above states a two-hour dine-in limit, which illustrates why interactive hot pot operators manage dwell time explicitly. In a 90-seat room, 145 daily covers equal about 1.6 daily seat turns on average, but the peak dinner window can be much tighter than the all-day average.
Ten additional covers per day add about $10,336 monthly revenue and $6,822 gross profit at a 66% margin before extra labor. If those covers require another host, busser, or closing shift, subtract that payroll. Filling weak weekday capacity with existing staff is usually more valuable than forcing another peak turn.
Track the seat-hour bottleneck
Review covers by daypart with the number of available seats and average party dwell time.
Covers per open hour
Seat utilization by daypart
Average table time and reset time
Turnaways, waitlist abandonment, and no-shows
Owner cash improves when incremental covers fit existing capacity without triggering a disproportionate staffing step-up.
2. Average check and menu mix
Raise the check without buying unprofitable traffic
The base check is $34, between a value-oriented lunch and a higher-priced dinner once beverages and mix are considered. The same official menu used above lists $21.99 lunch and $33.99 dinner before extras, showing why daypart mix matters. A $1 increase in realized check across 4,412 monthly covers adds about $4,412 of monthly sales. At the 66% base gross margin, that is roughly $2,912 of additional gross profit before any change in labor or marketing.
Beverages, premium broth, dinner mix, and reduced discounting can lift the realized check. But if higher pricing also increases premium-protein consumption, direct cost can rise too. Track gross profit dollars per cover, not menu price alone.
Separate price from mix
A strong average check should be traceable to specific guest behavior rather than a blanket increase.
Lunch versus dinner check
Beverage revenue per cover
Discount dollars per cover
Gross profit dollars per cover
When a $1 check increase holds the gross margin, modeled owner income rises after reserves; when food consumption rises with it, the gain can disappear.
3. Food cost and all-you-can-eat waste
Control protein yield and leftover food by cover
The base case assumes a 34% non-labor direct-cost load. That sits just above the 32.0% median food and non-alcohol beverage cost reported for full-service restaurants in 2024 by the National Restaurant Association, because this model also leaves room for payment processing and other direct costs. For an all-you-can-eat hot pot restaurant, that percentage can move quickly with beef, lamb, seafood, portioning, trim, spoilage, buffet replenishment, and food left on tables.
One direct-cost point on $150,000 monthly sales equals $1,500. Cutting direct cost from 34% to 33% raises pre-reserve profit by $1,500 a month and modeled owner income by about $975 a month, or $11,700 a year, after base reserves.
Measure food consumption per guest
Inventory percentage alone is too slow to diagnose an all-you-can-eat leak.
Protein ounces or cost per cover
Waste and discard dollars per cover
Purchase-price variance by major protein
Weekly actual food cost versus theoretical
Owner cash responds to tiny percentage changes because every guest consumes inventory before any distribution can be paid.
4. Labor productivity and owner coverage
Price the owner's labor before calling it profit
Full-service labor is a major constraint: the National Restaurant Association reported 36.5% median wages and benefits in 2024, versus 34.2% among profitable full-service respondents. The base calculator uses $44,000 monthly employee payroll, about 29% of sales, because the owner-GM is reclassified out of laborCost. Adding the owner's market manager role back conceptually brings the economics closer to the full-service benchmark.
A one-point labor swing is $1,500 a month at base sales and about $975 of owner cash after reserves. Replacing the owner is larger: the May 2024 BLS food-service manager wage benchmark is about $63,000 in food service and drinking places. That salary alone cuts modeled owner income by about $41,000 a year after reserves, before payroll burden.
Track labor by cover and by hour
Percent of sales is useful, but scheduling decisions happen in hours.
Labor dollars per cover
Covers per labor hour
Overtime and call-out coverage
Owner hours worked each week
The owner should know how much of take-home is compensation for management work and how much remains as a true return on ownership.
5. Repeat demand and paid acquisition
Make marketing pay back in covers, not impressions
The base model spends $3,000 a month on local marketing, about 2% of sales. That is a planning assumption rather than an industry benchmark. At a $34 check and 66% gross margin, an extra $1,000 of marketing needs roughly 45 incremental covers just to produce $1,000 of gross profit before any incremental labor: $1,000 divided by $34 times 66%. If the campaign only shifts existing regulars into a discounted visit, it can reduce owner income despite looking busy.
A campaign that brings 50 truly incremental covers produces about $1,700 of sales and $1,122 gross profit at base economics. That barely clears a $1,000 campaign before labor, so the economics improve only if enough guests return without another acquisition payment.
Connect promotions to repeat behavior
Measure whether new guests come back at full price and whether group bookings create more than one future visit.
Acquisition cost per first-time cover
30-, 60-, and 90-day repeat rate
Discount dollars by campaign
Revenue from loyalty guests versus paid traffic
Marketing should be scaled only when contribution after discount, direct cost, and incremental labor is positive.
6. Occupancy, utilities, equipment, and debt
Keep the fixed-cost floor below normal weekday sales
The base case carries $27,000 monthly fixed overhead plus $6,000 debt service. As a scale check, the National Restaurant Association reported 5.7% median occupancy cost for full-service restaurants in 2024; 5.7% of this model's $150,000 monthly revenue is about $8,550. The rest of fixed overhead must cover utilities, insurance, cleaning, repairs, software, administration, smallwares, and the extra equipment burden of a tabletop-cooking restaurant.
The FDA Food Code 2022 is the current full model code used by jurisdictions to shape retail food-safety rules, relevant to hot pot's raw meats, seafood, produce, shared utensils, and customer cooking. Base static break-even is $121,212 monthly revenue. Removing $6,000 of debt service lowers the target-pay threshold by about $9,091 a month and raises modeled annual owner income by $46,800 after reserves.
Track fixed cash before signing long contracts
Lease and loan decisions are difficult to reverse after the room is built.
Occupancy cost as a percentage of sales
Utilities and repair cost per cover
Debt service coverage from trailing cash flow
Months of payroll and fixed-cost reserve
Owner distributions should be the flexible line. Rent, equipment failures, lender payments, and tax deadlines are not.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.