How Much a Legislative Analysis Service Owner Can Make: $185K Case
Legislative Analysis Service Bundle
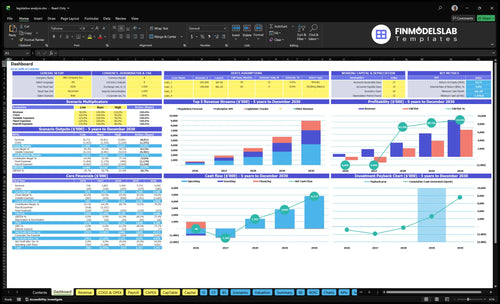
In this researched assumption set, the owner’s planned cash pay is $185,000 per year as CEO, but true owner income above that is limited until the firm clears its early losses Revenue grows from $738,000 in Year 1 to $90 million in Year 5, while EBITDA moves from negative $760,000 to $6606 million Contribution after data/API fees and payment processing is about 87% in Year 1 and 91% in Year 5 Because minimum cash reaches negative $1451 million in Month 25 and payback takes 41 months, distributions should be treated as scenario output, not guaranteed salary
Owner income$185kNet margin87%–91%Revenue for target pay$203k–$213kBusiness difficultyHard
Want the six biggest income drivers?
1
Retainer clients
↑$6.6M
More retainer clients spread the $19.5K monthly fixed base across more billable work, so owner take-home rises faster after the team is covered.
2
Retainer value
$450-$8.5K
Higher monthly pricing moves each account from the low-cost tracker tier to the richer forecast and API tiers, which lifts revenue per client.
3
Analyst utilization
87%-91%
Keeping analysts busy protects the 87%-91% contribution band, so wage growth does not eat the profit pool.
4
Service mix
5%-20%
A bigger share of Regulatory Forecast and Enterprise API work raises average contract size and supports the Year 5 revenue ramp.
5
Data costs
↓8%-6%
Cutting data and API fees from 8% toward 6% keeps more gross profit in the business and improves cash.
6
Reserve policy
41 mo
Keeping cash back delays owner draws, but it helps the firm survive the Month 25 cash trough and reach payback in Month 41.
Want to test your owner pay?
Owner income calculator
Estimate owner take-home and the target-pay gap from revenue, margin, costs, reserves, and target pay.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
How does a legislative analysis service make money?
A Legislative Analysis Service makes money mainly from monthly retainers, with extra revenue from issue-specific reports, billable research projects, rapid-response analysis, and premium monitoring packages. In Year 1, researched monthly prices are $450 for basic legislative tracking, $2,200 for regulatory forecasts, and $8,500 for enterprise access; by Year 5, they rise to $550, $2,600, and $10,500. The key is recurring work covering payroll and fixed overhead before custom projects, because premium packages only work when scope, turnaround, and analyst review time are priced into the retainer.
Core revenue
Monthly retainers drive base cash flow
Issue reports add one-off revenue
Billable research raises ticket size
Rapid-response work charges for speed
Pricing logic
$450 basic tracking in Year 1
$2,200 regulatory forecasts in Year 1
$8,500 enterprise access in Year 1
Year 5 rises to $550, $2,600, and $10,500
Can a legislative analysis service scale?
Legislative Analysis Service can scale, but not like passive income. The lift comes from moving founder-led analysis into analyst teams, standardizing deliverables, and selling recurring retainers; in the scenario, staffing grows from 60 FTE in Year 1 to 160 FTE in Year 5, while revenue per FTE rises from about $123,000 to about $563,000. The owner shifts from primary analyst to quality control, sales, hiring, and client strategy, and rework, long onboarding, data costs, client churn, and slow legislative cycles can still slow growth.
How it scales
60 FTE to 160 FTE
Standardize repeatable deliverables
Sell recurring retainers
Raise revenue per FTE
What can slow it
Rework drives margin loss
Onboarding can take too long
Data costs can climb fast
Churn hurts recurring revenue
How many clients does a legislative analysis service need?
A Legislative Analysis Service needs about 9 clients at a $2,200 monthly retainer to cover $19,500 in monthly fixed overhead, but closer to 56 clients for Year 1 break-even if payroll, marketing, overhead, and 13% revenue costs are included; track this with What Are The 5 KPIs For Legislative Analysis Service?.
Quick math
$2,200/month retainer equals $26,400/year
7 clients cover a $185,000 CEO salary
9 clients cover $19,500 monthly overhead
56 clients support full Year 1 break-even
What matters
Retainer size drives client count
Service depth drives analyst capacity
Churn can erase growth fast
Workload matters more than raw volume
Key Takeaways
Retainer clients stabilize revenue and support staffing.
Pricing lifts income faster than client count.
Utilization protects margins, but quality must stay high.
Reserves decide when profit becomes owner pay.
Compare low, base, and high owner-income scenarios
Owner income scenarios
Owner income changes with scale, margin, and payroll. Early losses leave no distribution room, while Year 3 and Year 5 levels create more room for pay and draws.
Low, base, and high cases show how profits and owner pay can change as the model scales.
Scenario
Low CaseLean case
Base CaseBase case
High CaseUpside case
Launch model
This low case assumes Year 1 scale, negative EBITDA, and no modeled distribution capacity.
This base case assumes Year 3 scale and positive EBITDA, with room for owner pay after reserves.
This high case assumes Year 5 scale and strong EBITDA, with the most room for owner pay and draws.
Typical setup
Year 1 revenue is $738,000, EBITDA is negative $760,000, the planned CEO salary is $185,000, payroll is $795,000, and marketing is $250,000.
Year 3 revenue is $3.449 million, EBITDA is $2.136 million, and the business is past early losses, so owner pay can start to come from profits.
Year 5 revenue is $9.0 million, EBITDA is $6.606 million, contribution margin is 91%, payroll is $1.96 million, and marketing is $1.35 million.
Cost drivers
negative EBITDA
$250,000 marketing
$795,000 payroll
$185,000 CEO salary
no distribution capacity
$3.449 million revenue
$2.136 million EBITDA
stronger scale
reserve-tested upside
owner pay room
$9.0 million revenue
$6.606 million EBITDA
91% margin
$1.96 million payroll
$1.35 million marketing
Owner income rangeBefore owner reserves
No owner drawNo draw
Meaningful draw roomProfit room
Largest draw roomTop upside
Best fit
Use this to stress-test the launch year if growth is slow and cash stays tight.
Use this as the main planning case if the business reaches steady client demand and controlled payroll.
Use this to test mature-scale owner income if sales, margin, and staffing all land near the Year 5 model.
!
Planning note: These scenario ranges are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distributions.
Legislative Analysis Service Core Six Income Drivers
Recurring Retainer Client Count
Recurring Retainer Client Count
More retainer clients stabilize monthly revenue and show staffing impact, but owner pay still depends on margin after fixed overhead and reserve needs are covered. Here, average monthly revenue grows from $61,500 in Year 1 to $750,000 in Year 5, so the upside is real. One clean line: volume only pays if the team can deliver it.
This driver includes active clients, monthly retainer value, analyst hours, and rework. Retained monitoring clients fund recurring payroll better than one-off reports, while low-fit clients can create scope creep and rework that cuts profit and delays owner draw.
Track Client Mix and Load
Track active retainer count, monthly billings, analyst hours per client, and rework rate. Here’s the quick math: monthly revenue equals retainer clients times monthly fee, then delivery costs and overhead come out. If workload rises faster than capacity, the extra revenue may not reach take-home income.
Set clear scope rules before selling the retainer. Watch for custom requests outside the agreed service, because they usually look good on revenue but weak on margin. The goal is simple: keep recurring work high enough to pay payroll, then convert the rest into profit and owner pay.
Research Platform And Data Costs
Legislative Data and Platform Spend
This driver is the spend on legislative tracking software and policy research databases. It is a required input, not a nice-to-have, because the work depends on live data and source access. In Year 1, data/API fees are 8% of revenue; at $61,500 monthly revenue, that is about $4,920, plus $1,800 per month in software subscriptions.
By Year 5, the data/API share falls to 6%, so margin improves if revenue grows faster than tool spend. If the owner buys enterprise tools before enterprise clients pay for them, take-home drops fast. Faster delivery helps, but only when paid coverage areas and client tiers cover the fixed stack.
Match Tools to Paid Coverage
Match each tool to a billable service line. Track monthly revenue, data/API fees as a percent of revenue, software subscriptions, and gross margin by client tier. Here’s the quick test: if a tool does not support paid coverage or cut turnaround time, it should wait. One clean rule: pay for what clients already buy.
Watch for margin drag when the subscription base is small. The fixed $1,800 monthly stack hits hardest early, so price lower-touch monitoring to cover it and reserve premium databases for higher retainers. If a data source raises quality but does not lift price, retention, or speed, it is a cost, not a profit driver.
Reserve And Reinvestment Policy
Reserve And Reinvestment Policy
If the firm is still burning cash, owner pay has to wait. This driver is the gap between profit on paper and cash in the bank: reserves fund payroll, renewals, contractor work, marketing, and slow legislative cycles. Here’s the quick math: early EBITDA losses of negative $760,000 and negative $1350 million reduce distribution capacity, with minimum cash at negative $1451 million in Month 25, breakeven in Month 26, and payback in Month 41.
Track Cash Floor Before Any Draw
Measure monthly cash balance, EBITDA, and the size of committed bills due in the next 60 days. The key inputs are retained earnings, client renewals, contractor load, and marketing spend, because those decide how much cash can be reinvested versus paid out. If the owner draws too early, payroll stress rises fast; if cash stays above the reserve floor after Month 26, owner income becomes steadier.
Track cash before owner draw.
Match spend to renewal timing.
Hold reserves through slow cycles.
Delay draws until cash recovers.
Sector Specialization
Sector Specialization
Sector specialization means building one policy lane, like healthcare, energy, or financial services, so analysts reuse the same sources, templates, and logic. That usually lifts average retainer, shortens turnaround time, and lowers rework rate. The owner’s income improves when that speed and fit let the firm charge more for the same labor hours.
Here’s the tradeoff: a tighter niche can support premium pricing, with Year 1 source prices of $450, $2,200, and $8,500 per month rising to $550, $2,600, and $10,500 by Year 5. But if the niche gets too narrow, pipeline volume can stall, and owner pay slows even when margins look strong.
Price the expertise, then watch the fit
Track average retainer, retention, turnaround time, and rework rate by sector. If a niche cuts research time and keeps renewals high, raise price for deeper coverage and faster briefs. That is where specialization turns into cash flow, not just busyness.
Keep one adjacent sector ready if new logos slow down. Use standard templates for repeat issues, and check whether senior analyst time is still being spent on custom work. If scope keeps drifting, margins fall and the owner’s take-home income gets squeezed.
Analyst Utilization
Analyst Utilization
Analyst utilization is the share of staff time that turns into paid client work. For this service, the owner’s income rises when billable hours, review hours, and turnaround stay tight enough to support margin on recurring retainers. With payroll at $795,000 in Year 1 and $196 million in Year 5, idle time or rework cuts cash available for owner pay fast.
The main inputs are analyst capacity, scope per retainer, review load, turnaround time, and rework rate. A senior policy analyst at $125,000 must be matched to the right client volume and complexity. Push utilization too high and quality drops, which can hurt renewals and lower long-term income. One clean rule: paid hours must stay ahead of correction hours.
Track billable hours, not just headcount
Measure billable hours ÷ total available hours each month, then split it by analyst level. If senior analysts spend too much time on low-value review or rework, the labor margin shrinks even when revenue looks stable. Track turnaround time and rework rate beside utilization, because high utilization with bad quality just turns into churn and refund risk.
Set scope limits by retainer tier so coverage depth matches the price paid. Use capacity plans that show how many analyst hours each client consumes, including review and revisions. If a team is near full but rework is rising, slow sales into that tier or raise price. Better utilization should improve profit, not burn out the team.
Average Retainer Value
Average Retainer Value
When average retainer value rises, income grows faster than client count. In Year 1, pricing runs from $450, $2,200, and $8,500 per month; by Year 5 it moves to $550, $2,600, and $10,500. Higher-priced monitoring and executive briefings can add revenue without the same lift in analyst hours, so owner pay improves once scope stays tight.
The risk is underpriced custom analysis. If a low-fee retainer pulls senior staff into repeated edits, margin drops and cash gets stuck in delivery. A higher average fee only helps when coverage depth, turnaround, and client value are clear enough to price the work correctly.
Price by scope, not by guesswork
Track monthly fee per tier, hours per client, rework rate, and exceptions. If a premium client needs faster turnaround or executive briefings, charge for that scope instead of folding it into a basic plan. That keeps revenue per client high and protects margin.
$450, $2,200, and $8,500 start points
$550, $2,600, and $10,500 Year 5 points
Cap custom work in writing
Review analyst time by retainer
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.