Does Owner Income in a Makeup Artist Depend More on Volume or Margin?
For an owner-operated U.S. makeup artist focused on bridal and special-event makeup, a practical planning range is about $26,000 to $101,000 a year in owner income after modeled tax and reinvestment reserves, with a base case of $61,908 on $180,000 of annual revenue. The base case assumes $15,000 of monthly sales, an 82% gross margin after products, disposables, payment fees, and unreimbursed travel, then $1,000 of assistant labor, $2,000 of fixed overhead, $1,200 of marketing, and $400 of debt service each month. It then holds back 25% of positive cash profit for taxes and 8% for reinvestment. Owner income here pays for the owner’s own working time plus residual profit; it is not passive profit or a guaranteed salary. It excludes personal health insurance, retirement contributions, and state or local tax differences.
Owner income$62KNet margin34%Revenue for target pay$177KBusiness difficultyModerate
How does a makeup artist turn bookings into owner income?
The revenue unit is a paid makeup service or event booking, not the gross wedding budget. The Knot’s 2026 wedding beauty data reports an average $150 for wedding makeup and $100 for wedding-party makeup, while also showing meaningful regional and experience-level variation. This model therefore treats published bridal prices as anchors, not as a universal rate card. The base case reaches $180,000 a year through a broader mix of bridal services, party makeup, trials, special-occasion work, travel fees, and higher-value grouped bookings.
The calculator deliberately keeps the owner’s own pay out of labor cost. Base labor of $1,000 per month is assistant coverage only. The 82% gross margin is a planning assumption after non-labor direct costs; it is not a published industry margin. Payroll, fixed overhead, marketing, debt service, tax reserve, and reinvestment reserve are modeled separately so the same expense is not counted twice.
Owner income calculator
Adjust revenue, margin, staffing, overhead, reserves, and target pay to estimate monthly owner income and the sales level needed to support it.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
1
Average service revenue
$150 bridal benchmark
Published bridal pricing is only the anchor; trials, travel fees, party packages, add-ons, and premium positioning determine the realized dollars per paid service.
2
Paid service volume
About 21 services/week
The base case needs roughly 1,030 paid service equivalents a year at about $175 collected per service, so calendar utilization matters as much as list price.
3
Party density and travel
76¢/mile tax benchmark
Grouping several faces at one venue and charging travel outside a core radius protects margin that would otherwise disappear into drive time and vehicle cost.
4
Assistant productivity
$5.5K/month high-case labor
Assistants unlock larger parties and parallel bookings, but only when the extra gross profit exceeds payroll, coordination time, and additional overhead.
5
Direct-cost discipline
82% base gross margin
Products, disposables, card processing, and unreimbursed travel are small individually but can move owner cash materially when they erode several margin points.
6
Acquisition efficiency
8% base marketing spend
The base model spends $14,400 a year on acquisition and promotion; referrals and repeat clients reduce the number of paid leads needed to refill the calendar.
Want to test the booking mix in a full forecast?
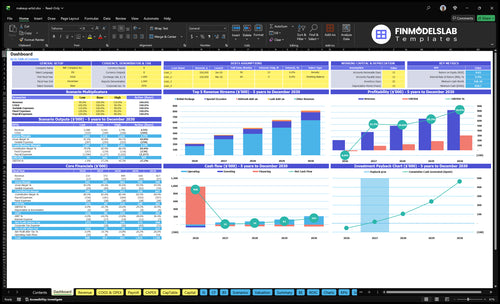
The dashboard preview tests how bridal packages and special-occasion services build revenue, where payroll and operating costs rise, and how scenarios change cash. The Makeup Artist Financial Model Template in Excel is most useful after replacing defaults with your own service menu, booking calendar, assistant plan, financing, and reserve policy.
What revenue level supports a $60,000 owner take-home?
In the base case, the business needs about $14,711 of monthly revenue, or $176,532 a year, to support a $5,000 monthly owner take-home after the modeled 25% tax reserve and 8% reinvestment reserve. That is much higher than simple operating break-even. Using the SBA break-even formula, $4,600 of monthly operating costs divided by the 82% contribution-like gross margin gives a cash operating break-even near $5,610 per month before owner pay and reserves.
The gap between $5,610 and $14,711 is the owner-income reality. Operating costs can be covered while the business still lacks enough cash for full-time owner pay, taxes, kit replacement, and slow months. Debt principal also reduces cash even though it is not an operating expense on an income statement.
Base threshold
$5,610 monthly cash operating break-even before owner pay and reserves
$14,711 monthly revenue needed for the $5,000 owner target
$176,532 annualized target-revenue threshold
$159 monthly base-case cash above the owner target
What must be paid first
Products, disposables, processing, and variable travel inside gross margin
$1,000 monthly assistant labor in the base case
$2,000 overhead, $1,200 marketing, and $400 debt service
25% tax reserve plus 8% reinvestment reserve before owner cash
How much does pricing and bridal mix change makeup artist income?
Pricing changes income quickly because most non-labor direct costs are a minority of the ticket. The same 2026 national wedding beauty study reports $150 average bridal makeup and $100 wedding-party makeup, but it also shows regional differences and higher pricing for more experienced artists. A founder should therefore model the realized collected revenue per service, not just the posted bridal rate.
Here’s the quick math: if an established artist performs 1,000 paid services a year, a sustainable $10 increase in realized revenue per service adds $10,000 of annual sales. At an 82% gross margin, that adds about $8,200 before fixed-cost changes. After the base 33% combined tax and reinvestment reserves, roughly $5,494 could reach owner income if labor, marketing, and overhead do not need to rise. If the higher price requires more paid ads, longer applications, luxury products, or an extra artist, subtract those incremental costs first.
Price the full event
Separate bride, wedding-party, trial, travel, and touch-up charges
Track discounts against the normal menu, not just headline price
Measure revenue per paid face and revenue per event day
Charge for time-heavy extras only when they cover extra time and product
Mix changes capacity
More bridal work raises ticket but can consume prime Saturdays
Party services can improve venue-level revenue density
Trials create another paid touchpoint before wedding day
Special-occasion work helps fill weekdays and off-season dates
Can a makeup artist business grow without the owner doing every face?
Yes, but the economics change once growth depends on hired artists. The BLS May 2025 wage data show a $17.21 median hourly wage for hairdressers, hairstylists, and cosmetologists and $46.71 for theatrical and performance makeup artists. Those are adjacent employee benchmarks rather than bridal-contractor quotes, but they show why a realistic staffing plan needs a wide labor band. The high scenario therefore raises monthly assistant labor from $1,000 to $5,500 while revenue doubles from $15,000 to $30,000.
The high case produces $101,184 of annual owner income after larger reserves, not twice the base, because more bookings require assistants, marketing, overhead, and reinvestment. If the owner stops performing services, add replacement lead-artist or manager labor; this model assumes the owner still sells, schedules, and works with clients.
Owner-operated model
Owner labor is paid through the residual owner-income output
Base assistant labor is $1,000 per month
Owner controls quality, sales, and calendar decisions directly
Capacity is limited by the owner’s available service and travel hours
Team-supported model
High-case assistant labor rises to $5,500 per month
Revenue must grow faster than payroll and coordination cost
Use written service standards and event staffing thresholds
Track revenue produced per assistant labor dollar
How should a makeup artist separate salary, distributions, and safe cash?
Revenue is not owner pay, and accounting profit is not automatically distributable cash. In the base case: $15,000 revenue becomes $12,300 gross profit, then $7,700 after $4,600 of operating costs including debt service; $2,541 is reserved, leaving $5,159 for owner income. Because debt service is deducted, the $7,700 is a cash-planning measure, not EBITDA.
For a self-employed owner, tax treatment also depends on entity and household facts. The IRS self-employed tax guidance explains that self-employed individuals generally file an annual return and pay estimated taxes quarterly, while the IRS self-employment tax topic states the federal self-employment tax rate is 12.4% Social Security plus 2.9% Medicare on the applicable net-earnings base. That is why the model uses a 25% tax reserve as a planning buffer rather than pretending it is the owner’s exact tax rate.
If an entity structure puts the owner on payroll, do not add that salary on top of the calculator’s residual owner income. Reclassify part of the residual as wages and the rest, if legally and financially appropriate, as distribution. Cash is safe to distribute only after upcoming payroll, vendor bills, card refunds, debt payments, taxes, kit replacement, and a slow-month reserve are funded.
Five money layers
Revenue: client and event sales before expenses
Gross profit: revenue after non-labor direct costs
Operating or EBITDA-style profit: before financing and owner distributions
Owner compensation: pay for work actually performed
Safe distribution: residual cash after debt, taxes, reinvestment, and reserves
Distribution test
Keep customer deposits matched to future service obligations
Fund quarterly tax and sales-tax obligations before draws
Keep enough cash for kit replacement and slow months
Do not count the same owner salary once in payroll and again as a draw
Key Takeaways
The base planning case is $61,908 of annual owner income after reserves on $180,000 of revenue.
The business can cover operating costs well before it can support a $60,000 owner take-home; the target-pay threshold is about $176,532 a year.
Owner income is compensation for the owner’s labor plus residual profit, so it should not be read as passive return or GAAP net margin.
Pricing, calendar utilization, travel density, assistant productivity, direct-cost control, and acquisition efficiency are the six strongest cash levers in this model.
What do low, base, and high makeup artist income scenarios look like?
The scenarios change costs with revenue: the high case adds labor, marketing, overhead, debt service, and larger reserves, while the low case stays owner-solo with weaker utilization. Licensing also varies by location; California’s Board of Barbering and Cosmetology says paid makeup services generally require a cosmetology or esthetician license unless exempt, while Texas TDLR guidance says makeup application itself is not regulated there. Replace compliance and insurance assumptions with local rules.
Owner income scenarios
Low, base, and high cases show how revenue, gross margin, staffing, overhead, marketing, debt service, and reserves change owner cash.
Low, base, and high Makeup Artist owner-income planning cases.
Scenario
Low CaseLow income
Base CaseBase income
High CaseHigh income
Launch modelDemand and staffing posture
Solo owner with a partial booking calendar and limited paid acquisition.
Owner-operated business with recurring bridal and special-event demand plus limited assistant coverage.
Owner-led team handling fuller wedding parties, stronger referral flow, and more parallel bookings.
Typical setupMonthly operating assumptions
$7,500 revenue, 78% gross margin, no assistant labor, $1,800 overhead, $700 marketing, and $300 debt service per month.
$15,000 revenue, 82% gross margin, $1,000 assistant labor, $2,000 overhead, $1,200 marketing, and $400 debt service per month.
$30,000 revenue, 84% gross margin, $5,500 assistant labor, $3,000 overhead, $2,500 marketing, and $600 debt service per month.
Cost driversWhat compresses owner cash
22% non-labor direct costs
Solo owner delivery
$700 monthly marketing
$300 monthly debt
28% combined reserves
18% non-labor direct costs
$1,000 assistant labor
$1,200 monthly marketing
$400 monthly debt
33% combined reserves
16% non-labor direct costs
$5,500 assistant labor
$2,500 monthly marketing
$600 monthly debt
38% combined reserves
Owner income rangeAfter modeled tax + reinvestment reserves
$26,352After modeled reserves
$61,908After modeled reserves
$101,184After modeled reserves
Best fitWhen to use the case
Use to stress-test a slower calendar, lower realized pricing, and an owner who remains solo.
Use as the normal planning case for a full-time owner with steady bookings and limited assistant support.
Use to test a strong team-supported calendar where extra labor and marketing are fully funded by extra demand.
!
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
Which six drivers matter most to makeup artist owner income?
These six drivers connect the booking calendar to owner cash, ranked by their effect on revenue capacity and retained dollars. The base case is an owner-operated mobile/event model; salon-heavy, film, retail-counter, or production makeup needs different assumptions.
1. Average service revenue and package mix
Raise realized revenue, not just the posted bridal price
The Knot’s 2026 data puts average bridal makeup at $150 and wedding-party makeup at $100, with pricing moving higher for experience, travel, and service complexity. The base model assumes about $175 collected per paid service equivalent across bridal makeup, party members, trials, special-occasion clients, travel fees, and add-ons. At $180,000 annual revenue, that is roughly 1,030 paid service equivalents.
A $10 increase across 1,000 services adds $10,000 of sales. At 82% gross margin, $8,200 reaches cash profit before fixed-cost changes; after the 33% combined reserves, about $5,494 can reach owner income. Subtract any extra acquisition, service-time, product, or labor cost required to earn that higher price.
Track the money per paid face
Separate service price from the event invoice so you can see what actually lifts owner cash.
Collected revenue per paid service
Trial and add-on attachment rate
Discount dollars as a percent of menu price
Travel fee collected versus travel cost
2. Paid service volume and calendar utilization
Protect prime dates without overbooking the owner
Makeup capacity is time-constrained. Zola’s wedding beauty timing guide suggests 60 to 90 minutes for the person getting married and 30 to 45 minutes for wedding-party members, before travel, setup, sanitation, and admin. About 1,030 annual base-case service equivalents means roughly 21 to 22 per week across 48 working weeks.
Three extra $175 services each week add about $25,200 of annual revenue. If they fit existing routes without new payroll, 82% gross margin creates about $20,664 before reserves, or roughly $13,845 after the base reserve rate. The scarce unit is a sellable service slot on a date clients want.
Track usable capacity, not vanity bookings
A full Saturday can still be weak if it contains low-value travel gaps and unpaid waiting.
Paid service equivalents per week
Revenue per working day
Inquiry-to-deposit conversion rate
Cancellation, reschedule, and no-show rate
3. Wedding-party density and travel recovery
Make one venue produce more revenue per mile
Mobile makeup businesses can lose margin in the car. For July through December 2026, the IRS business mileage rate is 76 cents per mile. It is a tax benchmark, not a perfect cash-cost measure, but a 50-mile round trip represents $38 before valuing the owner’s drive time.
Four separate 50-mile round trips equal 200 miles, or $152 at that benchmark. One 50-mile trip serving several party members uses $38, a $114 difference before time. Price both distance and opportunity cost when a remote event blocks another booking window.
Track revenue density by event
Travel should be a measurable unit, not a vague cost hidden in the owner’s schedule.
Miles per paid service
Revenue per venue trip
Travel fees collected
Unpaid travel and setup hours
4. Assistant labor productivity
Add labor only when it expands profitable capacity
The BLS May 2025 national wage table reports median employee wages of $17.21 per hour for hairdressers, hairstylists, and cosmetologists and $46.71 for theatrical and performance makeup artists. Bridal assistants are a different market, so neither figure is used as a contractor quote. The model instead budgets $1,000 monthly assistant labor in base and $5,500 in high.
High-case revenue is $15,000 per month above base, while assistant labor rises $4,500, overhead $1,000, marketing $1,300, and debt $200. Owner income rises from $5,159 to $8,432 per month. Each added artist must create enough incremental gross profit to cover labor plus the extra coordination and acquisition cost.
Track labor against revenue it unlocks
Do not hire because the calendar looks busy; hire because the extra capacity earns a return.
Revenue per assistant labor dollar
Gross profit per staffed event
Owner hours freed by assistants
Rework, lateness, and quality-control costs
5. Direct-cost control and gross margin
Keep small per-service leaks from becoming a large annual drag
The 82% base gross margin is a planning assumption, leaving 18% for products, disposables, card processing, and unreimbursed variable travel while payroll stays separate. Square Appointments pricing lists 2.6% + 15¢ for tap, dip, or swipe on its entry plan and 3.3% + 30¢ for online payments, so payment mix can consume several points before product or travel cost.
At $180,000 annual revenue, a two-point gross-margin drop removes $3,600 before reserves and about $2,412 from owner income after the base reserves, assuming other costs do not change. Measure direct cost by service category because bridal, party, trial, and long-distance work have different variable costs.
Track gross margin by service line
A single blended margin can hide which offers create owner cash and which only create activity.
Product and disposable cost per service
Card processing as a percent of sales
Unreimbursed travel cost
Gross margin by bridal, party, trial, and event service
6. Marketing conversion and referral efficiency
Buy booked revenue, not just inquiries
There is no reliable national customer-acquisition-cost benchmark for independent makeup artists, so marketing is a planning assumption. Base marketing is $1,200 a month, or $14,400 a year, equal to 8% of revenue. The Knot reports that 72% of couples in its 2025 Real Weddings Study hired a wedding beauty professional, but local conversion and pricing still vary.
At 82% gross margin, $14,400 of annual marketing needs about $17,561 of incremental revenue to cover itself at the gross-profit level. At roughly $175 per service equivalent, that is about 101 paid services before owner time. Referrals, reviews, repeat clients, and venue relationships can reduce paid-acquisition dependence.
Track the funnel to deposited revenue
The useful marketing metric is the cost of a booked, paid client—not clicks, followers, or inquiry volume.
Cost per booked service
Inquiry-to-deposit conversion
Booked revenue by source
Referral and repeat share of revenue
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Makeup Artist Bundle
Choosing a selection results in a full page refresh.