How Much Can a Metered Dose Inhaler Supplies Owner Make at $203M Revenue?
Metered Dose Inhaler Supplies Bundle
You’re trying to turn high unit volume into real owner income, not just a big sales number Based on the provided first-year model, this metered dose inhaler supply business reaches $203M in revenue and about 864% gross margin after stated COGS, before taxes, debt service, added staff, inventory reserves, and reinvestment This page covers business economics only, not clinical guidance, reimbursement approval, legal advice, or tax planning
Owner income$15.0M-$102.8MNet margin73.7%-80.5%Revenue for target pay$20.3M-$127.7MBusiness difficultyHard
Want to test your owner pay scenario?
Owner income calculator
Estimate owner take-home and the target-pay gap from monthly revenue, gross margin, costs, reserves, and target pay.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, owner distribution advice, reimbursement guidance, or clinical guidance.
Want the six income drivers that matter most?
1
Unit Volume
300K-1.68M
Year 1 volume is 300K units and Year 5 reaches 1.675M, so fixed costs get spread over more sales and cash rises fast.
2
Pricing
$35-$200
Prices run from $35 to $200 per unit, so contract wins or discounts move revenue and owner take-home right away.
3
Product Mix
80%-81%
Spacer attach holds near 80% to 81% of inhaler volume, and more combo or steroid sales lift cash per unit.
4
Supplier Terms
$3.2-$7.9/u
Direct input costs run from $3.20 to $7.90 per unit before overhead, so better buy terms protect margin on every sale.
5
Overhead
$1.06M
Year 1 fixed overhead is about $1.06M, so keeping rent, audits, insurance, marketing, IT, legal, and payroll in line matters a lot.
6
Working Capital
$1.24M
The model needs $1.235M minimum cash in Month 1, so inventory build can pinch owner cash even when EBITDA is strong.
Want to see how owner income fits the full financial model?
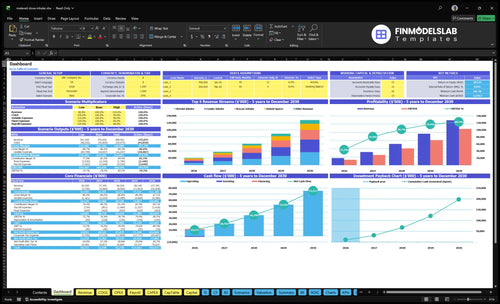
This dashboard ties owner income to revenue, margin, costs, reserves, and take-home assumptions in the Metered Dose Inhaler Supplies Financial Model Template. It shows revenue by product, COGS, variable expenses, fixed expenses, scenario testing, cash flow, and owner outputs; Year 1 revenue is $203M, Year 5 is $1,277M, gross margin rises from 864% to 871%, and fixed overhead is $222k a year. Open the model.
Owner-income model highlights
Owner take-home output
Revenue and gross margin
Scenarios and cash flow
How much revenue does a metered dose inhaler supply business need to pay the owner?
For Metered Dose Inhaler Supplies, there is no single revenue target for owner pay; it depends on gross margin, fixed overhead, collections, inventory buys, debt, and reserves. The clean formula is (owner pay + fixed overhead + reserves) ÷ contribution margin, and the Year 1 model shows 794% contribution before fixed overhead, with fixed overhead at $185k per month. So a $250k owner pay plus $222k of fixed overhead needs far less revenue at that margin than at a lower collected margin, but payer denials and slow cash can change the answer fast.
Owner pay drivers
Margin sets the revenue need
$185k monthly fixed overhead matters
Reserves must be funded too
Collections can shrink cash fast
Cash reality check
$250k owner pay is only one input
$222k fixed overhead raises the bar
Payer denials hit cash timing
Slow cash changes the math fast
Can a metered dose inhaler supplies business support a full-time owner?
Yes, Metered Dose Inhaler Supplies can support a full-time owner in the provided model, but only if volume, collections, compliance, and inventory cash stay on plan; see How To Launch Metered Dose Inhaler Supplies Business? for the launch path. Here’s the quick math: $2.03M Year 1 revenue on 300,000 units, less $275.5k COGS, leaves $1.7545M gross profit and about $1.59M before owner pay, taxes, debt, reserves, and reinvestment.
Owner Pay Math
Sell 300,000 units in Year 1
Average revenue is about $6.77 per unit
COGS is about $0.92 per unit
Keep wages separate from distributions
Cash Before Pay
Protect billing and collections timing
Fund inventory before taking draws
Add staff before scale strains service
Hold reserves for compliance costs
What risks reduce owner income in a metered dose inhaler supplies business?
Owner income in Metered Dose Inhaler Supplies falls when cash arrives slower than inventory bills, when products expire, when sales sit in a few contracts, or when compliance payroll gets added. At 300,000 units in year 1, the known $222,000 fixed overhead is about $0.74 per unit before billing staff, warehouse labor, software, and management. Supplier shortages can also raise COGS or lower fill rates, and scaling still ties up more working capital if the process stays manual.
Cash pressure
Slower cash cuts owner draws
Inventory bills hit before collections
Expiry turns stock into loss
Denials delay payment and cash
Scale risks
Contract concentration raises income risk
Compliance work adds payroll cost
Supplier shortages lift COGS
Manual systems need more working capital
Key Takeaways
Collected price sets the owner pay ceiling.
Volume helps only if cash and stock keep up.
Spacer-heavy mix can lift gross profit.
Lean overhead and terms protect distributable cash.
Compare low, base, and high owner income scenarios
Owner income scenarios
Owner pay moves with collections, compliance work, and inventory reserves. This model can look rich on paper, but working capital can cut what the owner can actually take.
Low, base, and high owner income capacity for the first five model years.
Scenario
Low CaseLow case
Base CaseBase case
High CaseHigh case
Launch model
This case assumes lower owner pay capacity from a soft start and slower cash conversion.
This is the modeled owner pay path from the base operating plan.
This case assumes stronger owner pay capacity as volume scales and fixed costs spread out.
Typical setup
Lower collected price, slower collections, added staffing, higher inventory reserves, and lower unit throughput keep cash tight.
Year 1 lands at 300,000 units, $20.3M revenue, and $15.0M EBITDA before owner pay exclusions.
Year 5 reaches 1.675M units, $127.7M revenue, and $102.8M EBITDA with a larger QA and ops team.
Cost drivers
Lower unit throughput
slower collections
added staffing
higher inventory reserves
compliance costs
Sales commissions
shipping and logistics
GPO rebates
quality control testing
sterilization services
Higher unit throughput
more favorable pricing mix
scale dilution of fixed costs
QA staffing
compliance load
Owner income rangeBefore owner reserves
$0 - $15.0MLow case
About $15.0MBase case
About $102.8MHigh case
Best fit
Use this to stress-test early cash pressure and contract delays.
Use this as the standard planning case for budgeting and lender talks.
Use this to test upside if volume lands and collections stay clean.
!
Planning note: Scenario ranges are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distributions.
Metered Dose Inhaler Supplies Core Six Income Drivers
Payer And Contract Pricing
Payer and Contract Pricing
Realized revenue per order sets the ceiling for owner pay. With a weighted average selling price of $6,767 in Year 1 and $7,624 in Year 5, the mix of Medicare, Medicaid, private insurance, cash-pay, schools, clinics, and institutional buyers matters a lot, but eligibility and rates must be verified. If collections slip or a contract cuts price, gross profit falls before overhead.
Clinic contracts can lift volume but often compress price. Cash-pay spacer sales may collect faster, which helps cash flow. The key inputs are billed price, collected price, payer mix, and denial rate. One line matters most: higher collected price = higher take-home income.
Track Realized Price by Channel
Measure billed, allowed, and collected price by payer and contract. That shows where revenue leaks before it reaches the bank. A fast check is simple: compare each channel’s net collected dollars per order against the $6,767 Year 1 benchmark and the $7,624 Year 5 benchmark.
Push up the mix of faster-paying, better-priced orders where allowed, and document every rate change. If a contract lowers price but only adds volume, make sure gross profit still covers labor, shipping, and billing time. Price quality drives owner draw.
Track denial and underpayment rates.
Reprice low-yield contracts.
Separate cash-pay from reimbursed sales.
Product Mix And Spacer Attach Rate
Spacer Attach Rate
Product mix changes income because it shifts both average selling price and gross margin. Here’s the quick math: $45M + $60M + $28M + $16M + $54M = $203M in Year 1 product revenue. With 120k spacer units versus 180k inhaler units, the implied spacer attach rate is about 67% if each spacer is paired to one inhaler sale.
That mix matters because spacer-heavy sales can improve cash-pay accessory economics, while inhaler volume can be more exposed to reimbursement pressure. More spacer attach can lift owner take-home only if pricing is compliant and collections stay clean; otherwise, the gain gets diluted by slower cash and weaker realized profit.
Track Mix and Margin
Track spacer attach by channel, SKU, and collected margin. The inputs you need are inhaler units, spacer units, realized price, and gross profit per unit. Use spacer units ÷ inhaler units as the main ratio, and separate valved, pediatric, and combo sales so you can see which mix actually funds overhead and owner draw.
Watch attach by clinic and pharmacy.
Test price against collected margin.
Flag slow cash on reimbursed items.
If spacer share rises while collections hold, cash flow usually improves before headcount needs to change. If attach rate climbs but price is too low, the extra units add work without adding much to owner income.
Operating Overhead And Staffing
Lean Overhead, Cleaner Pay
Overhead hits owner pay before profit does. The named fixed lines total $41k/month — $12k warehouse lease, $25k ISO 13485 audit fees, and $4k liability insurance — but the source also states $185k monthly and $222k annually, so the budget needs a clean reconciliation before anyone sizes distributions.
Year 1 variable expenses are 70% of revenue, so billing staff, compliance administration, software, warehouse labor, commissions, shipping, and GPO rebates can absorb cash fast. Lean staffing protects owner income, but if billing or compliance slips, collections slow and fulfillment risk rises. One missed process can cost more than one saved salary.
Track Overhead Per Shipped Unit
Measure fixed overhead per unit sold, plus the share of revenue taken by variable costs. Here’s the quick math: if revenue rises and fixed overhead stays flat, owner income improves only when collections and fulfillment stay on time. Build a monthly view for lease, audits, insurance, commissions, freight, rebates, and labor.
Keep a lean core team, but don’t starve billing or compliance. Track days to collect, order fill rate, and audit tasks on time. If understaffing creates a billing delay or shipping miss, cash flow takes the hit first, then owner pay follows.
Track billing lag days
Track fill rate weekly
Track audit task completion
Track overhead per unit
Supplier Cost And Purchasing Terms
Supplier Cost And Purchasing Terms
If you buy $380 rescue units, $620 steroid units, $320 valved spacers, $340 pediatric spacers, and $840 combo units before payer cash comes in, supplier terms can decide whether paper profit turns into usable cash. The model also carries 70% revenue-based COGS for quality control, sterilization, regulatory fees, inventory insurance, and waste, so every price break and rebate moves gross profit and owner pay.
Track landed cost and payment lag
Measure landed cost, not just unit price: purchase price, freight, minimum order size, rebates, and days to pay suppliers. If inventory is bought before collections clear, cash gets tied up even when sales look strong. Push for longer terms, smaller buys, and written rebate credits so lower COGS turns into cash the owner can actually take home.
Unit Volume And Recurring Demand
Recurring Unit Volume
Volume matters because it spreads fixed overhead across more units. Moving from 300k units in Year 1 to 1,675M in Year 5, with revenue rising from $203M to $1,277M, can raise owner pay only if margin holds and cash keeps moving. Repeat refill demand, school orders, clinic supply agreements, and seasonal respiratory demand all add repeat volume.
The catch is simple: more units help only when fulfillment, inventory, and collections keep pace. Stockouts, slow payer cash, and warehouse bottlenecks can turn growth into working capital stress instead of profit.
Track Reorders and Cash
Measure repeat units per customer, fill rate, and days to collect cash. Those inputs tell you whether volume is improving take-home income or just filling the warehouse. If unit growth outpaces shipping capacity or collections, the owner sees less free cash even when sales look strong.
Use reorder points and contract forecasts to match expected demand. One clean rule: no inventory plan, no owner draw plan. If collections lag, hold more cash before lifting pay.
Inventory Working Capital And Expiration Risk
Inventory Cash and Expiration Risk
Inventory cash is not owner cash. When unit volume grows from 300k in Year 1 to 1,675M in Year 5, the business must buy more stock before it collects cash, so more money sits in shelves instead of in the owner’s pocket.
Here’s the quick math: a combo inhaler can cost $840 per unit before collection. Add 20% waste and scrap inside revenue-based COGS, plus 05% inventory insurance, and expirations, slow-moving SKUs, returns, recalls, or payer delays can shrink distributable cash fast. More reserve lowers take-home pay, but it keeps the operation alive.
Track Stock Age and Cash Gap
Track days on hand, expiry date, return rate, and payer collection days by SKU. That tells you which items are safe to buy, which ones are tying up cash, and which ones should get smaller reorder sizes. One clean rule: if a SKU can’t sell before expiry, it should not sit on the shelf.
Units sold by SKU
Unit COGS and reorder size
Days to collect cash
Expiry and return rate
Test smaller buys on high-cost stock like the $840 combo inhaler, and keep a reserve for spoilage, recalls, and late payments. If inventory spend rises faster than collections, owner draws should wait until the cash gap closes.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.