How Much Can a Monitor Stand Sales Owner Make on $646k Revenue?
Monitor Stand Sales Bundle
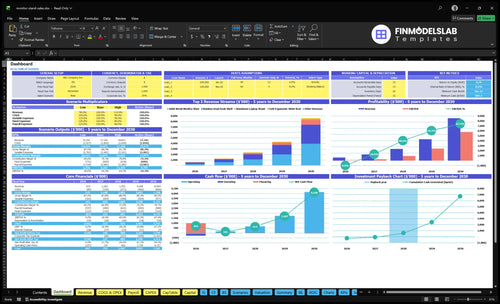
You’re selling monitor stands, risers, and desk accessories, so revenue is not the same as owner pay This page estimates $110,000 planned annual founder pay, modeled revenue from $646k in Year 1 to $72M in Year 5, margins, costs, reserves, and possible distribution capacity before personal taxes
Owner income$9.2k/moNet margin87%-90%Revenue for target pay≈$674kBusiness difficultyHard
Want to test your owner pay?
Owner income calculator
Estimate owner take-home and target-pay gap from revenue, margin, costs, reserves, and target pay.
!
Planning note: This is a research-based planning estimate, not guaranteed salary, tax advice, or owner distribution advice. It excludes taxes, financing, and one-time startup costs unless you add them separately.
What drives owner take-home most?
1
Volume & AOV
$217-$348
More orders and a higher basket lift revenue from $615K in Year 1 to $8.6M in Year 5, which is the main feed into owner pay before taxes.
2
Landed Margin
87%-90%
Direct materials and packaging stay near 10% to 13% of sales, so each unit keeps more gross profit for the owner.
3
CAC Mix
$45-$35
As marketing spend scales from $120K to $500K, customer acquisition cost falls, so more of each sale survives to profit.
4
Fulfillment Cost
5.5%-7%
3PL logistics and payment fees run about 7.0% in Year 1 and 5.5% by Year 5, and that spread drops straight into EBITDA.
5
Cash Reserve
$685K
Cash bottoms at $685K in Month 13, just before breakeven in Month 14, so reserves decide whether growth can keep funding owner income.
6
Founder Pay
$110K
The founder is paid $110K a year, but that only becomes real take-home if the fixed base and staff costs stay under control.
Want to check owner income in the Monitor Stand Sales model?
How much revenue is needed to make $100k selling monitor stands?
For Monitor Stand Sales, you need about $657k in annual revenue to pay the owner $100k and cover roughly $303.8k in non-owner wages and fixed overhead, assuming a 61.4% contribution margin. At a $217 average order value, that is about 3,030 orders a year, or about 252 orders a month. If the average order is 1.2 units, that works out to about 3,630 units a year.
Revenue math
$657k covers the target pay and overhead.
$217 AOV means about 3,030 orders.
That equals about 252 orders per month.
This is planning math, not cash in the bank.
What it hides
It excludes personal taxes.
It excludes debt payments and reserves.
It excludes inventory cash needs.
Margin must hold after product, fulfillment, fees, and marketing.
Is selling monitor stands profitable and owner-operated?
Monitor Stand Sales can be profitable at scale, but cash gets tight before it gets easy: Year 1 shows $646k revenue and about -$17k operating profit after the $110k founder salary, while Year 3 shows $22M revenue and about $926k operating profit after founder pay. It can stay owner-operated early for sourcing, listings, service, and marketing, but scaling adds payroll, software, design assets, fulfillment oversight, and inventory cash needs, with minimum cash need at $685k in Month 13 and higher sales raising reorder risk.
Early-stage fit
Owner can run sourcing.
Owner can manage listings.
Owner can handle service.
Owner can run marketing.
Scale pressure
Year 3 revenue: $22M
Operating profit: $926k
Month 13 cash need: $685k
Higher sales raise reorder risk.
What profit margin do monitor stands have?
Monitor Stand Sales can show a very high gross margin: about 87% in Year 1, improving to 90% by Year 5, when you only count direct manufacturing, materials, packaging, and inserts; see How To Launch Monitor Stand Sales Business?. But that is not take-home profit, because 3PL fulfillment and logistics run 4% to 3%, payment and platform fees can take 3% to 25%, and marketing can cost $120k to $500k a year.
Higher AOV matters only when bundles stay profitable.
Gross margin gains swing results more than volume.
Marketing and fees can erase revenue fast.
Hold cash until inventory and reserves are funded.
Compare lean, base, and high monitor stand income cases
Owner income scenarios
Owner income moves fast in this business because gross margin is high, but marketing, payroll, and fixed overhead also scale fast. The low case protects cash; the high case tests upside and inventory discipline.
Low, base, and high owner income cases for a monitor stand business.
Scenario
Low CaseLow Case
Base CaseBase Case
High CaseHigh Case
Launch model
This is a lean Year 1 ramp with limited scale and founder pay still pressuring profit.
This is the modeled Year 3 run-rate with stronger volume and a clear profit step-up.
This is a strong Year 5 scale case with much larger profit, but only if cash, inventory, and staffing stay tight.
Typical setup
Year 1 revenue is about $615k, gross margin is about 87%, and early marketing plus fixed staff costs keep owner income near zero.
Year 3 revenue is about $2.352M, gross margin is about 88.5%, and the larger order base starts to absorb fixed payroll and rent.
Year 5 revenue is about $8.564M, gross margin is about 90%, and scale lifts profit, but inventory and cash needs rise too.
Cost drivers
Early marketing
fixed payroll
rent and software
fulfillment fees
founder pay
Order volume
product mix
repeat orders
marketing efficiency
larger support team
Much higher volume
premium mix
repeat demand
bigger marketing budget
working capital needs
Owner income rangeBefore owner reserves
-$87kLow Case
$941kBase Case
$5.775MHigh Case
Best fit
Use this to stress test cash burn, hiring, and how long the launch phase can run.
Use this as the main planning case for hiring, ad spend, and working capital.
Use this to test upside, dividend capacity, and how much cash the business must keep on hand.
!
Planning note: Scenario ranges are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distributions.
Monitor Stand Sales Core Six Income Drivers
Sales Volume and Average Order Value
Orders and AOV
Revenue starts with orders, but income starts with profitable orders. Using the disclosed plan, 2,974 orders × $217 AOV produces about $646k in Year 1. The Year 5 input of 20,714 orders × $348 AOV equals about $7.2M on the math, so the stated $72M revenue figure does not reconcile.
AOV rises as units per order move from 12 to 18 and mix shifts across risers, shelves, stands, and wrist rests. Bundles can raise cash per order, but only if the added items still cover fulfillment and fees; otherwise, revenue goes up while owner take-home falls.
Track net order value
Measure orders, AOV, units per order, bundle attach rate, shipping cost, and fee load by product type. One clean rule: if AOV rises but contribution per order drops, the bundle is too expensive to ship or process.
Test bundles by margin, not sales.
Price add-ons after freight math.
Track return rate by item type.
Forecast cash on contribution, not gross revenue.
Fulfillment, Fees, and Returns
Fulfillment, Fees, and Returns
This driver covers storage, pick-and-pack, shipping, payment, platform fees, returns, replacements, and damage. In Year 1, fulfillment and logistics run 4% of revenue and fees add another 3%, so leakage is about 7%, or roughly $45k on $646k revenue. That comes straight out of gross profit, so it lowers cash available for owner pay.
Bulky monitor stands can push this higher because size drives storage and freight, and damage creates extra replacements. One damaged unit can trigger two costs: the replacement shipment and the lost margin on the original order. By Year 5, fulfillment and logistics improve to 3%, so packaging and shipping control matter more as volume grows.
Measure Cost by Order, Not Just Revenue
Track cost per order by product type: storage, pick-and-pack, postage, damage, and returns. The useful inputs are orders, average order value, box size and weight, return rate, and payment and platform fee rates. If a stand ships in a larger box than a riser, it should carry a higher margin target or a shipping fee built into price.
Orders by product type
Average order value
Box size and weight
Return and damage rates
Fee rate by channel
Test a free-shipping threshold, stronger packaging, and return rules by item. Protect margin before scale: a product with fewer returns and lower damage can fund more owner pay even at the same sales volume. Measure returns separately for stands, risers, shelves, and accessories so weak SKUs do not hide inside the average.
Owner Role and Fixed Overhead
Owner Role and Fixed Overhead
This driver is the founder’s share of the work plus the cost of keeping the lights on. In the model, fixed overhead is shown as $1,015k per month and $1,218k per year, while payroll starts at $292k in Year 1, including the $110k founder salary, then climbs to $646k by Year 5. That means owner pay depends on how much sourcing, listings, creative direction, service oversight, and marketing stays in-house without adding headcount too fast.
Hiring can protect growth and service quality, but every added role lifts the revenue needed before extra distributions make sense. If overhead grows faster than gross profit, cash that could go to the owner gets absorbed by payroll and admin.
Keep the founder in the highest-value work
Track which tasks the founder handles directly: supplier selection, SKU listings, creative direction, customer issues, and marketing calls. If the founder can keep those decisions in-house, owner income improves because payroll stays closer to the Year 1 base of $292k.
Before hiring, test the role against cash. Will it lift sales, reduce returns, or protect service enough to pay for itself? If not, it delays owner distributions and makes the business need more revenue before profit can reach the founder.
Landed Product Margin
Landed Product Margin
Landed product margin is the profit left after direct manufacturing, materials, packaging, and inserts. In this model, margin improves from 87% in Year 1 to 90% in Year 5. On $646k of Year 1 revenue, each 1-point margin change is about $6.5k before fulfillment, ads, and overhead, so small cost moves can change owner pay fast.
The inputs are simple: unit cost, packaging cost, insert cost, inbound freight, damage rate, and SKU mix. If supplier prices rise, freight changes, or packaging gets upgraded, gross profit drops right away. Slow-moving colors or materials also tie up cash and can force markdowns, which cuts the cash available for reorders and owner draws.
Track landed cost per SKU
Measure landed cost by product, not just by order. Build the check from supplier price + materials + packaging + inserts + freight + damage/write-offs, then compare it to selling price. That shows which monitor stands or desk accessories truly fund profit and which ones only create revenue.
Review margin by SKU monthly.
Track freight and damage rates.
Reprice after supplier changes.
Clear slow stock before it ages.
If packaging or freight drifts, margin can fall even when sales hold steady. A 2-point margin drop on $646k revenue cuts gross profit by about $12.9k, and that comes straight out of money available for operating costs and owner income.
Channel Mix and Ad Efficiency
Channel Mix and Ad Efficiency
Customer acquisition cost (CAC) falls from $45 in Year 1 to $35 in Year 5, but marketing still rises from $120k to $500k. That spend equals about 186% of Year 1 revenue and 69% of Year 5 revenue, so the owner only keeps more cash if paid traffic converts well and repeat buyers keep coming back.
Repeat customers rising from 12% to 25% of new customers helps offset ad cost, and direct traffic cuts fee drag. Here’s the quick math: a channel can boost sales volume and still hurt take-home income if ad spend and fees eat the margin, so net contribution matters more than top-line orders.
Track Net Contribution by Channel
Measure each channel by net contribution after ad spend and fees. Use orders, AOV, CAC, payment fees, fulfillment fees, and repeat rate to see which traffic actually funds owner pay. One clean rule: if a channel does not cover its own variable costs, it is not helping profit, even when revenue looks strong.
Track CAC by channel monthly
Compare spend to gross margin
Watch repeat rate and direct traffic
Cut low-margin channel volume
Use the same view for every channel so paid search, paid social, email, and direct traffic get judged on cash left after fees. That makes it easier to forecast owner distributions, because higher sales only matter when they leave enough contribution to cover overhead and still pay the founder.
Inventory Cash Flow and Reserves
Inventory Cash and Reserves
Accounting profit is not the same as cash the owner can take home. In this model, the business needs a $685k minimum cash balance in Month 13, even with a planned $110k founder salary, because cash gets tied up in inventory buys, supplier minimums, slower-moving colors or materials, and safety stock.
That gap matters for income. Owner distributions should wait until reorders and reserves are funded, or the business can look profitable on paper while still running short on cash. One clean rule: if stock, tools, and marketing spend rise faster than collections, owner pay has to stay deferred.
Protect Reorder Cash First
Track cash by use: inventory purchases, reorder timing, safety stock, and capital spend. Here’s the quick math: if cash is also funding $45k tooling and molds, $35k website development, and $22k packaging design, the reserve has to cover both operating stock and project spend before any draw is safe.
Measure sell-through by color and material, then cut slow movers before they trap cash. Keep a reorder reserve that covers the next buy cycle plus a cushion, and tie owner distributions to that reserve being intact. Cash on hand, not profit, pays the owner.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.