Where Does Owner Income Come From in a Motorcycle Manufacturing Business?
Motorcycle Manufacturing Bundle
A founder-led U.S. specialty motorcycle manufacturer can realistically produce about $0 to $731,000 a year in owner income after the modeled tax and reinvestment reserves, with a base case of $196,560 on $4.5 million of annual revenue. The base model assumes 15 motorcycles shipped per month at a $25,000 average manufacturer invoice, a 40% contribution margin before payroll, and an owner who serves as general manager rather than drawing a separate wage through the payroll input. Purchased powertrains, frames, electronics, freight, factory labor, warranty exposure, compliance, tooling debt, and inventory timing are the main constraints. The estimate is cash-planning output, not guaranteed salary, passive income, GAAP net income, or a promise that the cash is distributable; it excludes the owner's personal tax return, investor preferences, depreciation, and unmodeled capital calls.
Owner income$197KNet margin4%Revenue for target pay$4.4MBusiness difficultyHard
How much can a motorcycle manufacturing owner safely take home?
In the base case, $375,000 of monthly revenue leaves $150,000 after purchased components, inbound freight, consumables, and other non-labor direct costs. Payroll, fixed overhead, marketing, and debt service then consume $124,000, leaving $26,000 before reserves. A 25% tax reserve and 12% reinvestment reserve remove $9,620, so the model produces $16,380 per month, or $196,560 per year, for owner compensation and distributions combined.
This structure intentionally separates factory payroll from the owner's residual. It also uses a 40% pre-payroll contribution margin rather than copying a public manufacturer's reported gross margin. That reconstruction matters because Harley-Davidson reported that its 2025 gross margin fell as tariffs, lower volume, and negative operating leverage hit results; its reported margin includes cost categories that this calculator shows separately. The 2025 Harley-Davidson results are therefore a stress signal, not a small-factory margin target.
Owner income calculator
Adjust sales, production economics, payroll, financing, and reserves to estimate owner cash.
i
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
What moves motorcycle manufacturing owner income the most?
Six levers dominate the answer: monthly shipments, realized manufacturer invoice, purchased-component cost, labor throughput, dealer demand and warranty efficiency, and the cash burden of inventory, debt, and compliance. A founder can have attractive accounting gross profit and still have no safe draw if completed bikes sit unsold or supplier deposits absorb the bank balance.
1
Shipment volume
15 units a month
The base plant must ship, not merely assemble, roughly 180 motorcycles a year to spread minimum payroll and facility costs.
2
Net price and mix
$25K invoice
A $1,000 increase in realized price across 15 monthly units adds $15,000 of revenue before associated selling costs.
3
Bill of materials
60% direct cost
The base case allows $15,000 per $25,000 bike for purchased components, freight, and direct consumables before payroll.
4
Labor throughput
$65K monthly
Cross-trained assembly and quality staff must support 15 monthly shipments without overtime, rework, or a premature manager hire.
5
Dealer and warranty economics
4.8% of sales
The base marketing budget is $18,000 monthly; slow dealer sell-through or warranty claims can erase the residual owner cash.
6
Working capital and debt
$16K monthly debt
Deposits, parts inventory, certification, and tooling are paid before retail customers create cash, so leverage directly reduces distributions.
Want to test unit volume, pricing, and tooling cash in a full forecast?
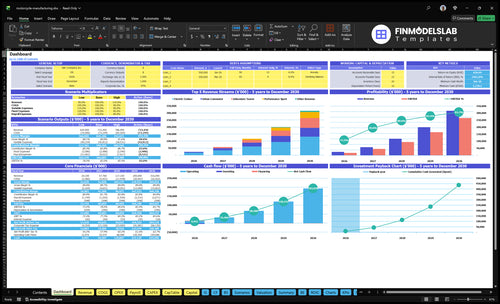
The Motorcycle Manufacturing Five-Year Financial Model Template provides a structured place to test product-line revenue, COGS, payroll, equipment, debt, scenarios, break-even, and cash runway. The dashboard preview helps a founder see whether an attractive owner-income result is supported by liquidity, capital investment, and a balanced set of financial statements.
What sales volume supports a real owner paycheck?
The base case needs about $369,524 of monthly revenue to support $15,000 of monthly owner pay after reserves. At a $25,000 blended manufacturer invoice, that is just under 15 shipped units per month. The model rounds operationally to 15 because a fraction of a completed motorcycle does not pay a bill. For market context, a 2026 Honda Rebel 1100 lists at $9,699 before destination, while higher-spec variants list above $11,000 on Honda's U.S. model page. A small specialty manufacturer using a $25,000 invoice therefore needs clear differentiation, premium specifications, options, or a channel structure that supports that value.
40% pre-payroll contribution = $150,000 to fund payroll and overhead.
$124,000 of operating cash costs leaves $26,000 before reserves.
$16,380 remains after modeled reserves, only $1,380 above target.
What the shipment count hides
Dealer orders are not the same as retail sell-through or collected cash.
Options can lift price while increasing parts complexity and build time.
Seasonal demand can bunch production and working-capital needs.
Returns, incentives, freight claims, and warranty accruals reduce realized price.
Can the founder take both a salary and distributions?
Yes, but the calculator's $196,560 base output is the total residual owner-income pool, not $196,560 of distributions on top of a separate owner salary. The model assumes the owner works as general manager and excludes owner pay from the $65,000 monthly labor line. In the real books, an active owner may need to classify part of that pool as wages and the remainder as a distribution, depending on entity type and tax advice. For an S corporation, IRS research on shareholder compensation explains that profit distributions must be preceded by reasonable compensation for services.
Build the compensation bridge
Revenue is not income; it first pays components, freight, and factory labor.
Operating profit is after operating costs but before modeled owner reserves.
EBITDA can ignore interest, taxes, depreciation, and some cash demands.
Safe owner cash is the residual after debt, reserves, and liquidity checks.
When ownership becomes passive
Replacing the founder as general manager creates a new payroll burden.
BLS reports a $148,790 mean wage for manufacturing general and operations managers in its manufacturing occupation data.
A full replacement hire could consume most of the base owner-income pool.
Passive distributions should be modeled only after replacement management is funded.
How much cash should stay inside the factory?
A practical base-case reserve is roughly $450,000 to $825,000, before any large tooling program. The low end equals about two months of the base model's $225,000 monthly purchased-component spend. The upper end adds roughly three months of the $124,000 operating-cost base. This is a planning range, not an industry rule. It protects supplier deposits, work in process, finished motorcycles, warranty claims, and the lag between shipment and dealer payment.
Do not use accounting profit as the withdrawal ceiling. Polaris reported lower 2025 motorcycle dealer inventory, while its North American 900cc cruiser, touring, and standard segment still saw a high-single-digit industry retail-sales decline in its 2025 Form 10-K. That is the cash-cycle warning: wholesale orders, dealer inventory, and consumer sell-through can move at different speeds.
Cash that is not owner pay
Supplier deposits and minimum-order components.
Work in process and completed but unshipped motorcycles.
Warranty reserve, recalls, rework, and service parts.
Certification tests, tooling revisions, and annual model updates.
Match debt to the asset
The base model carries $16,000 of monthly principal and interest.
SBA lender guidance lists 7(a) uses that include equipment, inventory, facilities, and working capital.
Do not finance recurring warranty losses with long-lived equipment debt.
Run a downside case before committing to personal guarantees.
What should a motorcycle manufacturing founder remember?
Key Takeaways
The base owner-income estimate is $196,560 after modeled reserves, not a guaranteed distribution.
About 15 monthly shipments at a $25,000 blended invoice are required to support the base target.
The founder's general-manager labor is embedded in owner income; adding a manager must reduce distributions.
Inventory, supplier deposits, warranty obligations, certification, and debt can make cash availability much lower than accounting profit.
What do low, base, and high owner-income cases look like?
The low case produces no owner income because minimum payroll and overhead exceed gross profit. The base case earns $196,560 after reserves, while the high case reaches $730,512 only after supporting higher output with more payroll, facility cost, marketing, debt service, and a larger reinvestment reserve. The high case is not a promise; it is a sensitivity showing what stronger shipment volume and margin could produce when capacity costs rise with sales.
Owner income scenarios
Three internally consistent operating presets for a founder-led U.S. specialty motorcycle assembler.
Low, base, and high motorcycle manufacturing planning cases
Scenario dimension
Low CaseRamp risk
Base CasePlanning case
High CaseCapacity test
Launch modelCommercial posture
Slow dealer onboarding and incomplete factory absorption
Founder-led specialty assembler with repeat dealer orders
Multi-region dealer network with premium product mix
Typical setupMonthly operating preset
$180,000 revenue; 32% margin; $42,000 payroll
$375,000 revenue; 40% margin; $65,000 payroll
$720,000 revenue; 44% margin; $110,000 payroll
Cost driversMain cash pressure
Underabsorbed labor, facility floor, and tooling debt
Purchased components, skilled payroll, warranty, and dealer support
Added labor, facility, marketing, inventory, and debt
Owner income rangeAfter modeled tax and reinvestment reserves
$0 annually
$196,560 annually
$730,512 annually
Best fitFounder profile
Prototype-stage founder with outside runway and no expected draw
Hands-on operator with validated product and dealer pipeline
Experienced team with proven demand and expansion capital
i
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
Which six operating decisions determine motorcycle manufacturing income?
The compact cards identify the levers; the next six sections show how to manage them. Keep the measurement basis consistent: shipped and accepted units, realized manufacturer invoice, non-labor direct cost, payroll before owner pay, cash marketing and warranty spend, and cash committed to inventory and financing.
1. Shipment volume and factory utilization
Build to validated orders, not optimistic capacity
The base model ships 15 units monthly and earns $25,000 per unit, while the low case at $180,000 of revenue cannot absorb a $42,000 payroll floor plus overhead, marketing, and debt. At a 32% contribution margin, low-case gross profit is only $57,600 against $93,000 of operating cash costs. Owner income is therefore $0, even though motorcycles are being built. Public-company results show the same mechanism at larger scale: Harley-Davidson said lower 2025 volume created negative operating leverage and helped reduce gross margin.
Here's the quick math: one additional base-case shipment at a $25,000 invoice and 40% contribution produces $10,000 before any incremental payroll, marketing, warranty, or freight beyond the modeled direct-cost percentage. That addition is valuable only if it is sold, accepted, and collected without forcing a new shift or expensive rework.
Track throughput to cash
Use a weekly funnel from confirmed dealer order to collected invoice, not a single production count.
Units started, completed, shipped, accepted, and paid.
Assembly hours and quality holds per completed unit.
Capacity utilization by work center, especially final test.
Backlog age and dealer cancellation rate.
2. Realized invoice and product mix
Price for a defensible niche and channel margin
The base $25,000 manufacturer invoice is a planning assumption for a premium specialty product, not a national average. Mainstream U.S. motorcycles can list far lower, so a founder needs evidence that specifications, design, limited production, electric drivetrain, customization, fleet application, or brand community justify the premium. Separate MSRP, dealer invoice, incentives, destination, options, parts, and recognized revenue; blending them hides discount leakage.
A $1,000 realized-price improvement across 15 monthly shipments adds $15,000 of revenue. At the base cost structure, that can add close to $9,450 after the 25% tax and 12% reinvestment reserves if it does not raise direct cost or operating expense. But a $2,000 retail option does not create $2,000 of manufacturer revenue when the dealer keeps a share and the option adds components and installation time.
Track the price waterfall
Reconcile the advertised price to the cash and receivable the manufacturer actually records.
MSRP, dealer invoice, incentive, freight credit, and net revenue per unit.
Gross dollars per model, trim, and option package.
Discount approval rate and aged dealer credits.
Mix of premium, entry, fleet, and accessory revenue.
3. Bill of materials and supplier terms
Protect contribution before adding volume
The base case allocates 60% of revenue, or $225,000 monthly, to purchased engines or motors, frames, suspension, brakes, electronics, batteries where relevant, inbound freight, packaging, and direct consumables. All payroll remains outside this percentage. A two-point deterioration in contribution margin reduces gross profit by $7,500 at $375,000 of monthly revenue. After the same operating costs and reserves, owner income falls from $16,380 to $11,655 per month, a $56,700 annual decline.
Tariffs and supplier concentration deserve explicit scenarios. Harley-Davidson attributed part of its 2025 margin decline to incremental tariffs, while Polaris also cited tariff charges and mix pressure. A small manufacturer has less purchasing leverage and may face minimum order quantities, prepaid tooling, and expedited freight, so the 40% base contribution should be proved at the purchase-order level.
Track landed cost, not catalog cost
Update the standard cost whenever supplier price, exchange rate, tariff, or freight assumptions change.
Landed bill of materials by model and revision.
Purchase-price variance and expedited freight per unit.
Supplier deposit days and minimum-order exposure.
Scrap, obsolete parts, engineering changes, and recovery claims.
4. Labor throughput, quality, and owner role
Use skilled payroll where defects are most expensive
The base $65,000 monthly payroll covers assembly, engineering support, quality, logistics, and sales before owner pay. BLS reports a May 2024 median wage of $48,750 for assemblers and fabricators in transportation equipment manufacturing in its assembler wage profile. The employer's full cost is higher after payroll taxes, benefits, overtime, recruiting, and training. A founder should therefore model loaded payroll by role rather than multiplying a shop-floor wage by headcount.
The owner serves as general manager in the base case. If the owner steps back and adds a $12,000 monthly loaded manager cost, base profit before reserves falls from $26,000 to $14,000 and monthly owner income falls to $8,820 after reserves. That is $105,840 annually, about $90,720 below the hands-on case. It is the cleanest test of whether the business provides wages for a job or returns on ownership.
Track first-pass yield and loaded hours
Labor efficiency must include rework, supervision, inspection, and paid downtime.
Loaded labor dollars and paid hours per shipped unit.
First-pass yield, rework hours, and final-test failures.
Overtime by bottleneck and schedule adherence.
Founder hours that a replacement manager would inherit.
5. Dealer demand, acquisition, and warranty
Measure retail pull-through, not wholesale enthusiasm
The base model spends $18,000 monthly, 4.8% of revenue, on dealer development, demos, digital demand generation, creative work, and launch support. That is a planning assumption. It excludes warranty and service parts, which should be accrued in direct cost or a separately reconciled reserve rather than hidden inside marketing. Dealer orders can temporarily make shipment revenue look healthy while unsold units accumulate downstream.
Harley-Davidson's 2025 results showed North American retail sales down 13% for the year, while Polaris reported softer North American industry retail demand in its relevant large-motorcycle categories. Those are adjacent large-brand indicators, not a forecast for a differentiated startup, but they justify a low case with slow sell-through. If the manufacturer spends $18,000 and ships 15 units, marketing cost is $1,200 per shipment before warranty support. A 20% increase without additional shipments raises cost by $3,600 and reduces owner cash by about $2,268 after reserves.
Track sell-through and field quality
Link each acquisition channel to retail registration, cash collection, and later warranty cost.
Dealer leads, signed dealers, orders, retail sales, and reorder rate.
Marketing dollars per collected shipment and per retail buyer.
Warranty claims, severity, repeat repair, and service-parts fill rate.
Dealer inventory age and incentive dollars per unit.
6. Working capital, debt, and compliance
Fund certification and cash timing before distributions
A motorcycle manufacturer is not simply an assembler with a brand. NHTSA's manufacturer portal identifies VIN requirements, manufacturer reporting under Part 566, and World Manufacturer Identifier records. EPA guidance explains that new highway motorcycles are subject to emissions standards and that small-volume manufacturers have specific compliance treatment in its highway motorcycle emissions guidance. State dealer, sales, facility, environmental, and occupational-safety obligations may add more cost depending on location and sales channel.
The base model's $16,000 monthly debt service reduces profit before reserves dollar for dollar. Eliminating it would raise monthly profit before reserves from $26,000 to $42,000 and owner income after the same reserve rates from $16,380 to $26,460, an annual increase of $120,960. But paying cash for tooling can create the same danger earlier by exhausting working capital. The decision should compare debt coverage, supplier deposits, inventory days, and a downside runway, not merely the interest rate.
Track liquidity with compliance milestones
A distribution is safe only after near-term production and regulatory commitments are funded.
Cash runway, borrowing availability, and debt-service coverage.
Supplier deposits, inventory days, receivable days, and customer deposits.
Certification, testing, documentation, and model-year milestone spend.
Warranty reserve, recall exposure, tooling refresh, and covenant headroom.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.