Municipal Contractor Owner Income On $1975M Year 1 Revenue
Municipal Government Contracting Service Bundle
You’re estimating owner income for a US public works contractor, not an employee wage The supplied model shows $1975M in first-year awarded revenue growing to $6061M in Year 5, but owner pay still depends on overhead, payroll, equipment, debt, retainage, bonding capacity, and reserves
Owner income$1.86M to $5.72MNet margin9.4%Revenue for target pay$19.75M to $60.61MBusiness difficultyHard
Want to test your owner pay case?
Owner income calculator
Estimate owner take-home and the target-pay gap from revenue, margin, costs, reserves, and target pay.
!
Planning note: Research-based planning estimate only. Actual owner income depends on revenue, margin, payroll, overhead, reserves, and debt timing. It is not guaranteed salary, tax advice, or owner distribution advice.
Want to see what drives owner take-home?
1
Bid Wins
18-43 projects
More wins push the model from 18 to 43 projects and lift revenue from $19.75M to $60.61M, which is the main path to higher pre-tax take-home.
2
Pricing
$1.2M-$4.28M
On jobs priced from $1.2M to $4.28M, a small bid error can wipe out a lot of profit, so pricing accuracy protects owner take-home.
3
Gross Margin
35%-40%
With 35% to 40% of revenue already going to listed job costs, every point of gross margin you save drops into EBITDA and pre-tax income.
4
Utilization
7-14 FTE
Keeping 7 to 14 FTE busy across more projects spreads fixed labor and equipment over more revenue, so idle time does less damage to profit.
5
Overhead
$15K-$68K
Permits, testing, safety, and reporting can add $15K to $68K per project, so lean compliance work keeps more cash for the owner.
6
Cash Buffer
$1.33M
A $1.333M minimum cash need in Month 1 means weak reserves can slow billing and execution, even when the revenue line looks strong.
Want to check owner pay in the Municipal Government Contracting Service forecast?
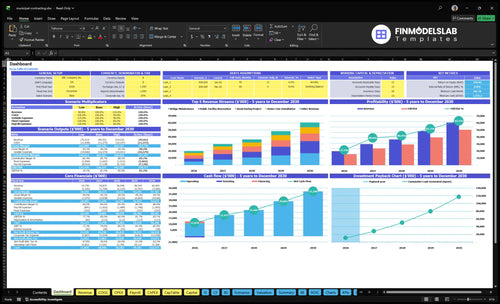
The Municipal Government Contracting Service Financial Model Template shows the dashboard, revenue by project type, job cost assumptions, gross margin, overhead, reserves, cash flow, and owner take-home. It also charts revenue growth from $1,975M to $6,061M, project count from 18 to 43, and gross profit pool from $1,856M to $5,718M; treat unlisted costs as scenario planning, not promised income.
Owner-income model highlights
Owner pay outputs shown
Revenue and margin charts
Scenario assumptions included
How much revenue does a municipal contractor need to pay the owner?
Municipal Government Contracting Service owner pay should be reverse-engineered from distributable margin, not from revenue alone: target owner pay ÷ distributable margin = required revenue. The model shows scale from $1,975M across 18 projects in Year 1 to $6,061M across 43 projects in Year 5, but it does not give the final net margin, so don’t promise a fixed salary; retainage and bonding can tie up cash.
Pay math
Start with target owner pay.
Subtract direct costs first.
Then payroll, overhead, reserves.
Divide by distributable margin.
Cash risk
Year 1 revenue: $1,975M.
Year 1 project count: 18.
Year 5 revenue: $6,061M.
Year 5 project count: 43.
How much can a municipal contractor owner make?
A Municipal Government Contracting Service owner can take home only what’s left after direct job costs, payroll, overhead, equipment, bonding, retainage, taxes, and reinvestment; reported profit is not safe cash to pull out. In the supplied assumptions, Year 1 shows $1.975M revenue and $1.856M pre-overhead gross profit, while Year 5 shows $6.061M revenue and $5.718M pre-overhead gross profit; for planning the payout rules, see How To Write Municipal Government Contracting Service Business Plan?. The owner’s real paycheck depends on cash timing, not just contract awards.
Owner cash drivers
Start with $1.975M Year 1 revenue
Protect payroll before distributions
Fund equipment and bonding needs
Hold cash for retainage delays
Profit reality
Year 5 revenue reaches $6.061M
Pre-overhead gross profit hits $5.718M
Taxes reduce owner cash
Reinvestment keeps projects moving
What profit margin should a public works contractor expect?
If you’re pricing a Municipal Government Contracting Service job, the supplied direct costs point to about 94.0% to 94.4% gross margin, but that’s before full field labor, subcontractor scope, payroll, overhead, equipment debt, and taxes. If you’re building out How Do I Start Municipal Government Contracting Service Business?, treat that number as a narrow screen, not the margin you’ll keep.
Direct-cost view
Shows 94.0% to 94.4% gross margin
Excludes full field labor
Excludes subcontractor scope
Excludes payroll, overhead, taxes
Margin risk drivers
Prevailing wage labor moves margin
Materials and mobilization matter
Bonding, safety, inspections add cost
Retainage and missed hours hit profit
Key Takeaways
Win more bids, but only if execution stays profitable.
Price contracts for all direct and hidden costs.
Gross margin matters more than revenue headlines.
Cash can stay trapped in retainage and reserves.
Scenario objective for low, base, and high owner-income planning
Owner income scenarios
Owner pay moves with project mix, staffing, and overhead. The same revenue can produce very different take-home once reserves, debt, taxes, and the owner's role are included.
Low, base, and high cases show how project count changes earnings.
Scenario
Low CaseLow Case
Base CaseBase Case
High CaseHigh Case
Launch model
The low case starts with Year 1 scale: 18 projects, $19.75M revenue, $1.19M direct costs, and $18.56M pre-overhead gross profit.
The base case uses Year 3 scale: 29 projects, $36.55M revenue, $2.13M direct costs, and $34.42M pre-overhead gross profit.
The high case uses Year 5 scale: 43 projects, $60.61M revenue, $3.43M direct costs, and $57.18M pre-overhead gross profit.
Typical setup
That assumes a smaller launch mix with 4 road paving jobs, 2 bridge projects, 8 sewer installs, 1 renovation, and 3 park builds.
That reflects a steadier run with more project management and compliance support, plus enough volume to spread fixed costs across more jobs.
That assumes a broader project mix, more field capacity, and a back office big enough to keep bidding and delivery moving.
Cost drivers
Permitting fees
bonding premiums
subcontractor labor
safety oversight
quality control testing
Bonding premiums
utility coordination
surveying services
inspection fees
project documentation
Structural analysis fees
asbestos abatement
HVAC commissioning
accessibility audits
electrical inspection
Owner income rangeBefore owner reserves
$15.4M EBITDALow Case
$29.4M EBITDABase Case
$50.4M EBITDAHigh Case
Best fit
Use this to test a slower first year and tighter owner draw planning.
Use this as the working plan for steady bid wins and normal execution.
Use this to stress-test upside, staffing pressure, and working-capital needs.
!
Planning note: These scenario ranges are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution targets.
Municipal Government Contracting Service Core Six Income Drivers
Bid Win Rate And Backlog
Bid Win Rate and Backlog
Owner income starts when qualified bids turn into awarded municipal contracts. Here, supplied backlog rises from 18 projects in Year 1 to 43 projects in Year 5, which is about 2.4x growth. That helps only if the firm can staff, bond, finance, and finish the work without margin erosion.
Track bid volume, win rate, awarded revenue, backlog months, and gross profit per award. A bigger backlog can raise owner pay, but thin pricing or poor execution can turn busy revenue into weak take-home.
Watch the Award Quality
Measure the pipeline from bid to award to start date. If wins rise but gross profit per award falls, the backlog is carrying too much low-quality work. That is a cash and profit problem, not a growth win.
Use a simple rule: do not chase volume unless the team can deliver it. If staffing, bonding, or working capital is tight, reject thin bids and protect owner income. Busy is not the same as profitable.
Working Capital And Reserves
Working Capital
Working capital is the cash left after you fund payroll, pay vendors, cover deposits, and wait for agency payments. In municipal contracting, retainage, bonding capacity, payables, equipment deposits, payroll timing, and reinvestment can trap cash even on profitable jobs. The quick test is simple: cash available for owner pay is not the same as accounting profit.
A project can look strong on paper and still limit draws if receivables are slow or the balance sheet must stay heavy for bonding. The calculator should keep retainage %, reserve %, and minimum cash editable because the supplied data does not give fixed percentages. One clean rule: profit does not pay the owner until cash clears.
Track Cash Traps
Track cash by project, not just companywide profit. Build a weekly forecast for collections, payroll, subcontractor payables, deposits, and owner draws, then compare that to the bonding cash target. If a job needs a bigger deposit or slower payment comes in, cut the draw first, not later.
Retainage % per contract
Days to collect receivables
Reserve target balance
Payroll timing gap
Bonding cash requirement
Owner draw limit
Test one change at a time: faster billing, tighter payables, smaller deposits, or less reinvestment. If the forecast falls below the reserve floor, delay distributions even when profit looks strong on paper. That keeps the business bondable and protects future owner pay.
Labor And Equipment Utilization
Labor and Equipment Utilization
Labor and equipment utilization is how much paid crew time and machine time turns into installed work. In public works, idle crews, rental days, fuel, mobilization, and rework eat margin fast. A road job can carry about $5k in heavy-equipment fuel, a bridge job about $20k in crane operations, and sewer excavation support about $5k; wasted hours turn those costs into lower owner pay.
Here’s the quick math: if the team finishes on time and avoids schedule slippage, more of each contract price becomes gross profit instead of extra labor and equipment cost. Crew utilization means billed productive hours divided by paid hours. If utilization drops, cash flow slows too, because the job takes longer while payroll, rentals, and supervision keep running.
Cut Idle Job Time
Track crew utilization, equipment downtime, rental days, fuel per job, mobilization days, and rework. Tie each job to a labor code and machine log so you can see where time leaks out. If one site keeps slipping, fix sequencing, crew sizing, or subcontract timing before you bid the next one.
Compare planned versus actual days
Review idle equipment each week
Flag jobs over budgeted fuel
Cut rework before closeout
Use the numbers to protect margin, not just revenue. A job that looks big on paper can still shrink owner income if it drags on and burns extra fuel, rental time, and supervision. The best target is simple: finish work cleanly, with no idle time and no unpaid delay.
Contract Pricing Accuracy
Contract Pricing Accuracy
When a public works bid is too low, owner income drops before the job even starts. Pricing has to cover labor, materials, subcontractors, mobilization, bonding premiums, insurance, escalation, traffic control, inspections, safety oversight, and contingency; with 35% to 40% revenue-based costs, the job only leaves 60% to 65% before overhead and tax.
That matters most on $1M+ contracts, where a thin bid can still win but leave little distributable cash. The unit-cost range of $15k to $68k only helps if the estimate matches the real scope and risk; otherwise, the owner takes the award and the cash strain.
Price Every Risk Line
Build bids from clean inputs, not gut feel. Track estimate-to-actual by line item and keep a simple review on each bid: labor, materials, subs, mobilization, bonding, insurance, escalation, traffic control, inspections, safety, and contingency. If one of those lines is missing, the owner’s take-home income is already at risk.
Labor and crew hours
Materials and supplier quotes
Subcontractors and mobilization
Bonding and insurance premiums
Escalation and contingency
Traffic control and inspections
Reprice fast when scope changes. If a bid only works at perfect productivity, it is too thin; the owner may win the work, but cash for salary or profit draw can disappear once compliance and field costs hit.
Overhead And Compliance Burden
Overhead And Compliance Burden
Municipal work needs estimating, project management, certified payroll, insurance, bonding, safety, documentation, inspections, and public notices. Those costs are not bad by themselves. They matter only if they help win more work, protect compliance, and support bigger bonded jobs. If back-office staff grows faster than gross profit, owner take-home falls.
Use owner pay = gross profit - overhead - debt service - reserves. When backlog rises from 18 projects in Year 1 to 43 projects in Year 5, overhead should scale with revenue quality, not headcount. Waste shows up when added staff do not improve bid accuracy, collections, execution, or compliance, and then the company pays fixed cost without getting more margin.
Measure The Back-Office Load
Track overhead as a percent of revenue and per active project. Split it by function: estimating, PM, payroll, insurance, bonding, safety, docs, inspections, and public notices. Then compare each line to awarded revenue and closeout speed. If one hire does not lift win rate, billing speed, or compliance pass rate, it is not earning its keep.
Track overhead per active project.
Review bid accuracy monthly.
Price compliance work into bids.
Cut roles without payoff.
Watch the cash effect too. Public work can delay billing when certified payroll or inspection files are wrong, so a small admin miss can slow collections and hold back owner draws. The test is simple: does each support role help the next award, the current job, or the final payment? If not, trim the spend or bake it into contract pricing.
Job Gross Margin
Job Gross Margin
For public works, gross margin is the first step from contract revenue to profit. On the provided figures, Year 1 revenue of $1,975M minus $119M direct costs leaves $1,856M gross profit, or about 94.0% gross margin.
By Year 5, $6,061M of revenue minus $343M of direct costs leaves $5,718M gross profit, about 94.3%. This is not net profit. Overhead, payroll, debt service, reserves, and taxes still come out before the owner can pay themselves.
Protect Gross Profit Per Job
Track each job’s revenue, direct labor, materials, subcontractors, equipment, fuel, and permit or inspection costs. Here’s the quick math: gross profit = contract revenue minus direct costs. If direct costs drift up by even 1 point on a large award, take-home can shrink fast.
Use a job cost report weekly, not after closeout. Watch direct costs as a percent of revenue, change-order recovery, and rework. If a project looks profitable on paper but direct cost control slips, gross margin falls first, then owner draw gets squeezed.
Revenue by project
Direct costs by cost code
Change orders billed and approved
Rework and delay costs
Gross margin % by job
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.