How Should an Owner Estimate Income from a Musical Instrument Store?
Musical Instrument Store Bundle
An owner-operated musical instrument store in the United States can plausibly produce about $14,000 to $166,000 a year in owner income after modeled tax and reinvestment reserves across the low-to-high cases used here. The base case produces about $85,680 a year from $1.50 million of annual revenue, assuming a 42% gross margin after merchandise and other non-labor direct costs, $19,000 of monthly paid labor, $16,000 of fixed overhead, $4,000 of marketing, and $3,000 of debt service. The owner is assumed to work as general manager, so owner compensation is not buried in payroll. These figures are planning estimates, not a guaranteed salary or distribution, and they exclude the owner's final personal tax outcome and any return on separate equity invested in the store.
Owner income$86KNet margin6%Revenue for target pay$1.54MBusiness difficultyHard
How much can a musical instrument store owner make?
For a full-line independent store, a useful base planning case is roughly $125,000 of monthly sales and $7,140 of monthly owner income after reserves. The scope follows the full retail category: the U.S. Census NAICS definition covers musical instruments and supplies and can include stores that combine retail with repair, rental, or instruction. Customers can include hobbyists, students, working musicians, schools, houses of worship, and studios.
The latest final 2023 Census AIES retail table reports about $5.36 billion of U.S. employer-firm sales for musical instrument and supplies stores and about $862 million of annual payroll. Payroll was therefore about 16.1% of sales at the industry level. It is not a store-level profit margin, but it is a useful labor check: the base case below uses $228,000 of annual paid labor, or 15.2% of modeled sales, before any owner compensation.
Demand is also cyclical and discretionary. The broader NAMM 2025 Global Report estimates 2024 U.S. music-products shipments to retailers at $8.27 billion, down 2.1% from 2023 after several years of post-pandemic normalization. It is a broader demand indicator, not a direct store-sales benchmark, so owner pay should be modeled from normal-month traffic, ticket, mix, margin, and cash needs rather than a holiday peak.
Owner income calculator
Adjust monthly sales, margin, costs, reserves, and target pay to estimate owner cash.
i
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
1
Transaction volume
26 sales/day
At the $185 planning ticket and 26 open days, about 26 completed sales a day supports the $125,000 monthly base revenue.
2
Average ticket and mix
$185 ticket
Higher-value instruments lift the basket, while accessories, consumables, used gear, repairs, and rentals can improve margin quality and repeat visits.
3
Gross margin
42% base
One extra gross-margin point on $1.50 million of annual sales adds about $15,000 of gross profit before other costs change.
4
Inventory discipline
$300K plan
A $300,000 average inventory exposure is a planning guardrail; a 10% markdown or write-down would consume $30,000 of cash and margin.
5
Labor productivity
$19K/month
Base paid labor is 15.2% of sales and assumes the owner covers the general-manager role instead of adding another management salary.
6
Overhead, demand spend, debt
$23K/month
Fixed overhead, marketing, and debt service consume $23,000 a month before the tax and reinvestment reserves reduce owner cash further.
Want to test the assumptions in a full store forecast?
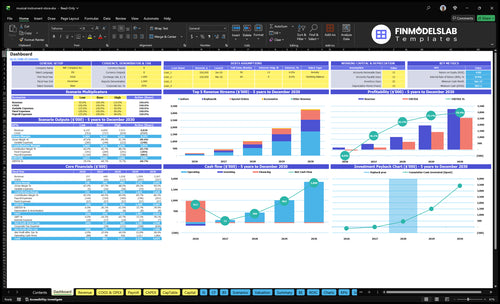
The Musical Instrument Store Financial Projections Template in Excel lets you pressure-test sales volume, product mix, payroll, inventory, debt, and cash runway together. The dashboard preview is useful for comparing the $125,000 base monthly-sales case with a slower ramp or a higher-cost manager-run setup without treating any one outcome as guaranteed.
How much revenue does a musical instrument store need to support $8,000 monthly owner pay?
In this base model, the store first needs about $100,000 a month, or $1.20 million a year, just to cover operating costs before owner reserves and owner pay. To support the chosen $8,000 monthly owner-pay target after the 22% tax reserve and 10% reinvestment reserve, required revenue rises to $128,011 a month, or $1.536 million a year. That is why a store can look busy and still miss the owner's cash target.
The math starts with gross margin, not markup. The Census retail glossary defines gross margin as sales less cost of goods sold. For calculator compatibility, this article uses a slightly broader direct-cost bucket: the 42% margin is what remains after merchandise purchase cost, inbound freight, card processing, and other non-labor direct costs, while payroll stays entirely in the separate labor field. That avoids counting labor twice.
Payment acceptance is material because instrument baskets can be large. As one current U.S. reference point, Square Retail pricing lists 2.6% plus $0.15 for base-tier in-person tap, dip, or swipe transactions and 3.3% plus $0.30 for base-tier online payments. A store using another processor may pay something different, but the direction is the same: a shift from cash or lower-cost payments toward higher-cost card-not-present volume can shave gross margin unless pricing or supplier terms absorb it.
Base revenue bridge
$125,000 monthly sales
42% gross margin = $52,500 gross profit
$42,000 monthly operating costs
$10,500 profit before reserves
Owner pay test
22% tax reserve = $2,310
10% reinvestment reserve = $1,050
$7,140 monthly owner cash remains
$860 monthly shortfall versus the $8,000 target
Revenue is therefore not the same thing as income. Gross profit is revenue after direct merchandise and transaction costs. Operating profit is what remains after payroll and overhead; EBITDA would normally exclude interest, taxes, depreciation, and amortization, so the calculator's cash result should not be called EBITDA because it explicitly deducts debt service. Owner salary is compensation for work. Owner distribution is a separate transfer of residual profit or capital. The model's owner-income output is the cash pool left after modeled operating costs and reserves; if the owner runs payroll for a salary, part of that same pool should be reclassified as salary rather than added on top of it.
Can the store still pay you if you hire a manager?
Yes, but not at the same sales level unless the manager adds enough productivity to cover the extra payroll. If a full-time manager adds a $6,500 monthly loaded labor cost in this planning example, the $125,000 base-revenue store falls from $85,680 of annual owner income to about $32,640 after the same reserves. Restoring the $8,000 monthly target would require about $143,487 of monthly sales, or $1.72 million annually, if gross margin and other costs remain unchanged.
The wage number is deliberately a planning assumption rather than a national manager benchmark, because store-manager pay varies sharply by geography and experience. For frontline context, BLS retail-sales wage data puts the May 2024 median retail salesperson wage at $16.62 per hour nationally. Musical-instrument selling also demands product knowledge, demos, inventory handling, and customer follow-up, so experienced staff can cost more than a generic retail median.
Owner-operated base
Owner works as general manager
Paid labor: $19,000 per month
Owner cash: $7,140 per month
No owner wage is duplicated inside labor cost
Manager-run sensitivity
Add $6,500 monthly loaded manager cost
Owner cash falls to about $2,720 per month
About $1.72M annual sales supports the $8K target
Manager must lift conversion, ticket, hours, or owner freedom enough to justify cost
Entity structure matters too. For an S corporation, the IRS reasonable-compensation guidance says payments to shareholder-officers for services must be treated as wages to the extent they represent reasonable compensation. So an active owner should not simply label all cash as distributions. In this article's operating model, the correct sequence is: calculate the total owner cash pool, determine a defensible wage for services with a tax professional, run that wage through payroll, and treat only the remaining eligible cash as a distribution. That may change payroll taxes, but it must not create a second layer of owner earnings.
Why can a profitable music store still run short of cash?
Because inventory, debt service, seasonality, and reinvestment consume cash before the owner can safely draw it. The base case may show $10,500 of monthly profit before reserves, yet only $7,140 is modeled as owner income after a $3,360 reserve. Separately, this article uses a $300,000 average inventory exposure as a planning guardrail; a 10% markdown or write-down on that stock would be $30,000, equal to about 35% of base annual owner income.
Retail inventory is cash tied up on the shelf. The Census inventory definition treats merchandise inventories as goods held for sale valued at cost. That accounting point matters operationally: a wall full of slow-moving guitars or keyboards can look valuable while reducing liquidity. The broader NAMM industry report notes that the inventory imbalances and glut that affected the music-products channel had receded by 2024, but it also describes profit-damaging discounting during the correction. That is a warning to buy depth selectively rather than equating assortment with cash safety.
Debt makes the cash floor harder. The model includes $3,000 of monthly principal-and-interest service in the base case. Actual terms depend on lender, collateral, maturity, and credit profile; the SBA 7(a) guidance, for example, publishes maximum variable-rate spreads over a base rate rather than one universal loan rate. The owner's safe draw should therefore come after required debt payments and after enough working capital remains to reorder fast sellers, cover a slow month, and fund repairs or store improvements.
Cash gets trapped here
Slow-moving high-ticket instruments
Seasonal pre-buys before demand arrives
Markdowns that turn inventory into less cash than planned
Debt payments due even in weak sales months
Pay yourself after these checks
Vendor bills and payroll are covered
Required debt service is funded
Tax reserve is segregated
Inventory and working-capital reserve stays intact
Key Takeaways
The base model turns $1.50M of annual revenue into about $85,680 of owner cash after modeled reserves, not a guaranteed salary.
Operating break-even is about $1.20M of annual revenue, while the $96,000 annual owner-pay target needs about $1.536M under base costs and reserves.
Hiring a manager without more revenue can reduce owner cash sharply; owner labor must be priced rather than treated as free profit.
Inventory aging, card fees, debt service, and reinvestment can make accounting profit look healthier than cash that is safe to distribute.
What do low, base, and high owner-income cases look like?
The three scenarios produce about $13,824, $85,680, and $166,320 of annual owner income after modeled tax and reinvestment reserves. They are deliberately cost-aware: the high case raises paid labor, fixed overhead, marketing, debt service, and reserve rates along with revenue, while the low case keeps a meaningful fixed-cost floor. That is more useful than changing sales while pretending staffing and inventory never move.
The base case is also anchored to an external labor check. The 2023 Census AIES table reports revenue, payroll, expenses, inventories, and related operating statistics for employer businesses; the musical-instrument retail row shows payroll at about 16.1% of sales. The base model's paid labor is 15.2% before owner compensation, close enough to serve as a reasonableness check while still leaving room for local wage and staffing differences.
Owner income scenarios
Low, base, and high cases show how sales, margin, staffing, overhead, financing, and reserves change the owner's cash pool.
Musical Instrument Store low, base, and high owner-income planning cases.
Scenario factor
Low CaseConservative
Base CasePlanning case
High CaseStrong demand
Launch modelDemand and owner role
Owner-heavy coverage
$95K monthly sales
38% gross margin
Owner-operated general manager
$125K monthly sales
42% gross margin
Expanded team
$180K monthly sales
45% gross margin
Typical setupMonthly paid cost base
$15K labor
$14K fixed overhead
$2.5K marketing
$3K debt service
$19K labor
$16K fixed overhead
$4K marketing
$3K debt service
$31K labor
$18K fixed overhead
$6K marketing
$4K debt service
Cost driversMargin and reserves
38% margin
20% tax reserve
8% reinvestment reserve
Higher markdown risk
42% margin
22% tax reserve
10% reinvestment reserve
Disciplined category mix
45% margin
25% tax reserve
12% reinvestment reserve
More inventory and team support
Owner income rangeAfter modeled tax and reinvestment reserves
$13,824
$85,680
$166,320
Best fitHow to use the case
Slower ramp
Owner covers more shifts
Weak category demand
Established independent store
Balanced traffic and mix
Normal paid staffing
Strong traffic
Extra paid labor
Deeper inventory and marketing
i
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
Which six income drivers matter most for a musical instrument store?
The six strongest levers in this model are completed transaction volume, average ticket and category mix, gross margin, inventory discipline, labor productivity, and the combined burden of overhead, marketing, debt, and reserves. They interact: ticket, margin, staffing, and inventory can offset one another. The broader BLS retail productivity analysis is a useful reminder that sales growth and margin productivity can move differently; for the combined sporting-goods and musical-instrument category, sales productivity grew faster than margin productivity over 2007–2022.
1. Transaction volume and conversion
Turn normal-month traffic into about 26 completed sales a day
The base model uses a $185 blended transaction and 26 open days. $125,000 divided by $185 is about 676 monthly transactions, or roughly 26 completed sales per day. It is a planning assumption, not a national store average, but it converts revenue into an observable floor-team KPI. If daily completed sales fall to 22 at the same ticket, monthly revenue falls to roughly $105,820 and the owner-pay cushion disappears quickly.
Conversion quality matters because instrument sales are consultative. The BLS retail-sales profile specifically describes recommending products, explaining features, processing payments, stocking, and tracking inventory. For a music store, product demos and knowledgeable matching can materially affect conversion.
Track conversion by traffic source
Separate walk-ins, appointment shoppers, school referrals, local events, and online-originated visits so traffic growth is not mistaken for sales productivity.
Completed transactions per open day
Visitor-to-buyer conversion
Revenue per staff hour
Lost-sale reasons by category
2. Average ticket and category mix
Raise the basket without relying only on expensive instruments
The $185 base ticket blends high-ticket instruments with strings, reeds, sticks, cables, cases, stands, sheet music, maintenance items, used gear, and service revenue. The Census industry definition explicitly accommodates stores that combine retail with repair, rental, or instruction, so a diversified store can use services and repeat-purchase items to smooth the gap between major instrument purchases.
Here's the quick math: raising the average ticket from $185 to $195 at the same 676 monthly transactions adds about $6,760 of revenue. At a 42% gross margin, that is roughly $2,839 of additional monthly gross profit before any extra labor, marketing, or direct-cost mix changes.
Measure mix, not just the headline ticket
A higher ticket matters only if the mix still produces cash; track accessories and services with the instrument sale.
Average transaction value
Accessory attach rate
Used-versus-new sales mix
Repair, rental, and lesson-related revenue share
3. Gross margin and direct-cost control
Protect each margin point before chasing more sales
The base model uses a 42% gross margin after merchandise, inbound freight, payment processing, and other non-labor direct costs. It is a planning assumption, not a published national margin. The accounting foundation is consistent with the Census definition of gross margin, while the calculator broadens the direct-cost bucket slightly so payroll stays separate.
One margin point on $1.50 million of annual revenue equals $15,000 of gross profit. That is about 18% of base annual owner income before tax effects. Card fees, supplier discounts, freight, returns, and markdowns therefore deserve the same attention as topline sales.
Review realized margin by category weekly
List price is not realized margin. Use landed cost and actual transaction fees, then compare new instruments, used gear, accessories, and service work.
Gross margin dollars and percent
Landed cost by supplier
Discount rate and return rate
Payment-processing cost as a percent of sales
4. Inventory discipline and markdown risk
Do not let assortment turn into trapped owner cash
This model uses a $300,000 average inventory exposure as a planning ceiling for the base store, not an industry benchmark. If 10% of that stock ultimately requires a full write-down or equivalent markdown, the $30,000 hit is about 35% of base annual owner income. Smaller discounts still matter on slow-moving high-ticket items.
The broader NAMM 2025 report describes how prior channel overproduction created an inventory glut and profit-killing discounts before imbalances receded. Buy depth from verified sell-through, not vendor enthusiasm or one strong season.
Age inventory before it becomes a surprise
Use open-to-buy limits and aging bands so slow stock triggers a decision while there is still pricing flexibility and vendor leverage.
Inventory dollars by age bucket
Weeks of supply by category
Gross-margin return on inventory
Markdown dollars versus owner income
5. Labor productivity and owner coverage
Price the owner's job before calling the rest profit
Base paid labor is $19,000 a month, or $228,000 a year, equal to 15.2% of modeled revenue. That is close to the roughly 16.1% payroll-to-sales ratio implied by the 2023 Census AIES row for musical instrument and supplies stores. The owner then supplies the general-manager role, so the calculator does not include an owner wage inside labor.
If a manager adds $6,500 of loaded monthly cost, owner income in the unchanged base-sales case drops to about $32,640 a year after reserves. Passive ownership and working-owner income differ because replacing the owner's labor has a real cost.
Track payroll against gross-profit dollars
Sales per labor hour alone can reward low-margin volume. Compare staffing cost with gross profit, conversion, service capacity, and the owner's own hours.
Paid labor as a percent of revenue
Payroll dollars per gross-profit dollar
Owner hours by operating role
Manager replacement cost
6. Fixed overhead, acquisition spend, debt, and reserves
Set the distribution only after the cash floor is funded
The base case spends $16,000 a month on fixed overhead, $4,000 on marketing, and $3,000 on debt service, for $23,000 of monthly non-labor cash costs before reserves. After labor, total operating costs are $42,000. The model then holds back 22% of positive pre-reserve profit for taxes and 10% for reinvestment, leaving $7,140 of monthly owner cash.
Debt terms should be stress-tested because rates and maturity change the monthly floor; the SBA 7(a) program publishes maximum variable-rate spreads rather than a single universal rate. Likewise, owner distributions should not be treated as a fixed entitlement. Salary compensates work; distributions come from residual cash after obligations and reserves. For an active S-corporation owner, the IRS reasonable-compensation rule reinforces that distinction.
Use a monthly safe-to-distribute test
Before transferring owner cash, confirm that the next vendor cycle, payroll, debt payment, tax reserve, and planned inventory replenishment remain funded.
Fixed overhead as a percent of sales
Marketing spend and acquired-customer gross profit
Debt-service coverage
Tax and reinvestment reserve balances
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.