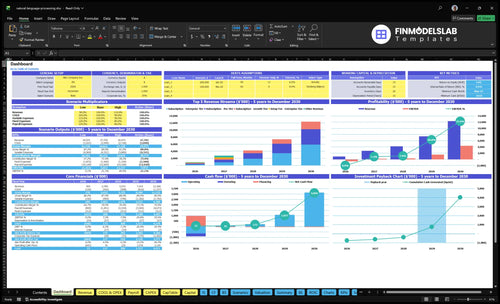
How Much Natural Language Processing Development Owners Make by Year 5
Natural Language Processing Development Bundle
You’re planning owner pay before the model has proved itself, so separate revenue from cash you can take out This page covers US natural language processing (NLP) development revenue, gross margin, payroll, cloud costs, reserves, and founder salary versus distributions using a five-year model Figures are planning estimates before personal taxes and are not compensation, tax, or investment advice
Owner income$0Net margin-69% to 36%Revenue for target pay$506kBusiness difficultyHard
What drives owner income in an NLP company?
1
Contract Value
$902K-$12.4M
Bigger enterprise and pro deals lift annual revenue fast and drive EBITDA from -$623K to $4.4M.
2
Recurring Mix
10%-25%
A heavier Enterprise mix raises recurring revenue, lifts lifetime value, and supports higher take-home.
3
Delivery Efficiency
86%-90%
Tighter model delivery and support protect gross margin before payroll, which is where profit starts.
4
Infra Cost
14%-10%
Cloud inference and data fees can eat scale gains, so lower spend drops straight into EBITDA.
5
Pipeline Quality
$1.2K-$900
Better trial and paid conversion lower CAC and make growth less cash-hungry.
6
Owner Leverage
18 mo
Keeping the owner on sales and product helps the business reach breakeven by month 18 without extra overhead.
What owner pay can your NLP business support?
Owner income calculator
Estimate owner take-home and the gap to target pay from revenue, margin, operating costs, reserves, and target pay.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
How much revenue does an NLP development business need to pay the owner?
If you want the owner paid from Natural Language Processing Development, work backward from salary first: $26k a month in fixed overhead sits on top of $775k payroll and $120k marketing in Year 1, so $902k revenue still does not cover the cost base or support owner distributions. Breakeven lands in Month 18. By Year 2, $2.784M revenue can support about $200k EBITDA before taxes, debt service, reserves, and distributions.
Year 1 cash gap
$26k monthly overhead
$775k payroll
$120k marketing
$902k revenue falls short
Owner pay path
Month 18 breakeven
$2.784M Year 2 revenue
$200k EBITDA support
Salary is separate from distributions
How much can an NLP development founder take home?
A Natural Language Processing Development founder can take home salary first, then approved distributions only after cash reserves and taxes are covered. In the base model, $775k Year 1 payroll and -$623k EBITDA mean no safe distributions; a lean solo or owner-led setup may support founder salary earlier.
Take-home range
Year 1: salary only, likely tight
Base EBITDA: -$623k
Year 2 boutique EBITDA: $200k
Year 5 scaled EBITDA: $4.403M
Watch before paying
Revenue is not founder income
Track engineer utilization weekly
Limit client concentration risk
Protect recurring contracts and reserves
What affects profit margins in an NLP development company?
Natural Language Processing Development margin is mostly a cost-control game: engineering labor, data prep, model tuning, and cloud runtime decide what’s left after sales. For Please Provide Your Business Idea Name?, cloud infrastructure and model inference run about 10% of revenue in Year 1 and 8% in Year 5, while data API fees fall from 4% to 2% and support tools from 3% to 1%. Sales commissions stay at 5%, so weak usage limits and loose change orders can wipe out margin fast.
Cost drivers
Engineering labor is the biggest drag.
Data prep and tuning take time.
Cloud and inference run 10% to 8%.
API fees drop from 4% to 2%.
Margin leaks
Sales commissions stay at 5%.
Support tools fall from 3% to 1%.
Security reviews and QA add hours.
Weak usage caps erase margin.
Key Takeaways
Price scope tightly or enterprise margin erodes fast.
Recurring retainers smooth cash, but service load stays real.
Better utilization lifts EBITDA, until burnout and rework hit.
Pass-through cloud costs and qualify leads to protect margin.
Compare lean, base, and scaled NLP owner-income scenarios
Owner income scenarios
Owner income changes fast here because gross margin before payroll stays high, but payroll, cloud/API costs, marketing, and overhead rise with scale. Cash is tight until the model clears Month 18 breakeven.
Low, base, and high cases show how much owner income the model can support.
Scenario
Low CaseLow Case
Base CaseBase Case
High CaseHigh Case
Launch model
This is the low-income path: sales are still ramping, EBITDA stays negative, and owner distributions are off the table.
This is the middle path: revenue reaches Year 2 to Year 3 scale, and owner income can start only after reserves are set aside.
This is the strong-scale path: Year 5 revenue and EBITDA support meaningful owner-income capacity before taxes, debt, and reinvestment.
Typical setup
Year 1 revenue is about $902k, gross margin before payroll is roughly 86%, and payroll, cloud/API costs, marketing, and fixed overhead push EBITDA to -$623k with a Month 17 cash trough.
Revenue rises from $2.784M to $4.233M, EBITDA reaches $200k to $333k, and the business has room for limited pre-tax distributions after payroll, cloud/API costs, marketing, and overhead.
Revenue reaches $12.368M, EBITDA climbs to $4.403M, and better conversion, lower CAC, and a larger enterprise mix help absorb payroll, cloud/API costs, marketing, and overhead.
Cost drivers
Cloud/API fees
payroll growth
marketing spend
fixed overhead
cash gap
Trial conversion
paid conversion
payroll growth
marketing budget
reserve needs
Enterprise mix
lower CAC
higher pricing
payroll scale
reinvestment needs
Owner income rangeBefore owner reserves
No distributionsLow Case
Limited distributionsBase Case
Meaningful distributionsHigh Case
Best fit
Use this to stress-test survival if trial conversion or paid conversion lands below plan.
Use this as the working plan for budgeting and owner pay once the model clears breakeven in Month 18.
Use this to test what owner pay could look like if enterprise sales land and cost ratios keep improving.
!
Planning note: Scenario ranges are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distributions.
Natural Language Processing Development Core Six Income Drivers
Contract Value and Pricing
Enterprise Contract Pricing
With a $4,500 enterprise monthly price in Year 1 and $5,500 in Year 5, plus one-time fees rising from $10k to $15k, owner income improves only when scope is priced correctly. The $1,500 Pro setup fee helps cash flow, but integrations, compliance, data complexity, and model customization can turn a good deal into thin margin if they are included for free.
Price the Work, Not Just the Logo
Track integration count, security review hours, and client-specific maintenance before you quote. Separate discovery, rework, and change requests from the base fee. If delivery expands faster than the $4,500 to $5,500 monthly step, gross margin falls and owner pay gets squeezed even as top-line revenue grows.
Quote custom scope separately
Bill discovery and rework
Track maintenance hours monthly
Cloud, API, and Model Operating Costs
Cloud, API, and Model Costs
This cost line includes cloud infrastructure, model inference, embeddings, storage, monitoring, security, and third-party model fees. In Year 1, cloud and inference are 10% of revenue and data API plus enrichment fees are 4%; by Year 5 they fall to 8% and 2%. That drop can protect owner pay if sales grow faster than usage.
Here’s the quick math: at $1.0M of revenue, this line is about $140k in Year 1 and $100k in Year 5. If usage rises but pricing does not, gross margin shrinks and cash available for payroll, debt, and owner draw gets tighter. The risk is surprise spend from heavy clients or long-running models.
Price for Usage, Not Hope
Set pass-through charges, usage caps, and overage fees before launch, then tie them to monthly usage reports. Track cost as a percent of revenue for inference, API calls, and enrichment separately, not as one blended bucket. One clean rule: if a client’s usage grows, the contract should grow too.
Forecast with the real inputs: conversations, API calls, embedding volume, storage, and monitoring load. If a deal needs custom security or third-party model access, price it into the contract or the owner eats the margin. Contract-level reporting makes the spend visible early, so you can fix pricing before it hits take-home income.
Owner Role Leverage
Owner Role Leverage
Owner role leverage is the shift from doing client work to building the system that sells, delivers, and protects margin. In an NLP development business, early time in coding, solution design, proposals, and delivery can lift near-term owner pay, but it also keeps profit tied to one person and caps scalable EBITDA.
As the owner moves into sales, hiring, QA, partnerships, security posture, and product strategy, the firm can grow without the founder doing every hour. The trade-off is real: management costs money before it pays back, so income improves only if pipeline quality and delivery control keep pace.
Track the shift, not just the hours
Measure billable owner hours, nonbillable leadership hours, utilization, rework, and EBITDA each month. If owner billability stays too high, take-home can look strong now, but sales follow-up, QA, and hiring get delayed and the founder stays the bottleneck.
Track revenue per owner hour against the added cost of management. Move the owner out of daily delivery once repeat work, support, and QA are documented, or the business keeps paying founder wages instead of building scalable profit.
Owner billable hours versus leadership hours
Utilization and rework rate
Pipeline conversion and close speed
QA defects and client escalations
Recurring Revenue Mix
Recurring Revenue Mix
Recurring revenue mix matters because monthly subscriptions smooth owner pay. In Year 1, pricing runs $499 Growth, $1,499 Pro, and $4,500 Enterprise; by Year 5, that rises to $599, $1,699, and $5,500. The mix affects monthly recurring revenue (MRR), so a heavier Enterprise share usually gives steadier cash flow, but only if support and model work stay in line.
This is not pure profit. Retainers can include support, model monitoring, tuning, hosting, API maintenance, and analytics, so service load and infrastructure costs keep coming. If those costs rise faster than subscription price, owner distributions shrink even when revenue looks stable. The key test is recurring gross margin, not just booked MRR.
Track Tier Mix and Load
Measure recurring revenue by tier, churn, and service hours per account. Track how many clients sit in Growth, Pro, and Enterprise, plus the cost of hosting, API use, and monitoring tied to each tier. Here’s the quick math: higher monthly price helps, but only when delivery cost per account stays below that tier’s monthly bill.
Price for load, not just features. Put support scope, tuning limits, and usage caps in the contract, and charge overages when monitoring or API traffic climbs. That protects cash flow and makes hiring cleaner, because you can see when recurring revenue can cover new delivery staff instead of guessing.
Sales Pipeline Quality
Sales Pipeline Quality
This driver is the mix of qualified visitors, trials, paid wins, and deal sources. For an NLP development company, it matters more than raw lead count because $120k of Year 1 marketing at $1,200 CAC only buys about 100 customers if the funnel holds; weak fit just burns sales time and delays cash. Here’s the quick math: 35% × 12% = 4.2%, while 55% × 18% = 9.9%.
Founder-led enterprise sales can close larger contracts, but it can also slow delivery when demos, security reviews, and custom scopes pile up. By Year 5, $1M of marketing at $900 CAC can buy about 1,111 customers, but only if niche positioning and partnerships keep close quality high. Better pipeline quality means steadier recurring revenue, fewer cash dips, and less pressure on owner pay.
Track Conversion, Not Traffic
Measure visitors, trials, paid customers, CAC, sales-cycle days, and source mix by channel. If one channel drives trials but weak trial-to-paid conversion, cut or fix it. A simple check: every 1,000 visitors is worth about 42 paid customers at 4.2% overall conversion now, or 99 at 9.9% later.
Use partnerships and a narrow use case to lift close quality. That cuts founder hours on custom pitches and protects delivery capacity. Tie sales goals to booked recurring revenue and setup fees, not raw meetings, and review the funnel monthly so cash forecasts stay realistic.
Delivery Labor Efficiency
Developer Utilization
NLP developer utilization is how much of the team’s paid time turns into billable work, shipped product, or paid support. With $775k of Year 1 payroll — one CTO at $180k, two AI/ML engineers at $150k each, one account executive at $90k, one customer success manager at $85k, and one full stack developer at $120k — small idle gaps hit EBITDA fast. Higher utilization lifts gross margin and owner distributions.
The catch is quality. Burnout, rework, hiring gaps, and senior review bottlenecks can turn “busy” into “expensive,” so the owner’s take-home only rises when paid hours also produce clean output. If review queues grow or fixes pile up, labor cost stays high while cash left for salary or profit draw falls.
Keep the Team Billable
Track billable utilization, rework hours, and review queue time every week. Use those inputs to forecast how much of the $775k payroll actually converts into margin. If senior review becomes the bottleneck, the CTO stops scaling output, and owner income gets stuck even when headcount is rising.
Measure billable hours by role.
Flag rework and handoff delays.
Watch open roles and coverage gaps.
Set QA checks before senior review.
Keep work moving with clear scopes, fixed review windows, and simple escalation rules. That protects quality while pushing more labor cost into revenue-producing work, which is what actually lifts EBITDA and the owner’s distribution capacity.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.