How Much Owner Income Can an Outdoor Adventure Park Generate?
A stabilized, owner-operated Outdoor Adventure Park in the United States can realistically produce about $150,000-$220,000 of annual owner income around $1.8 million of annual revenue; the base model below produces $189,000 after a 25% tax reserve and 12% reinvestment reserve. It assumes a single-site zipline and ropes-course park with group events and ancillary sales, $660,000 of annual non-owner payroll, $216,000 of fixed overhead, $120,000 of marketing, and $216,000 of debt service. Revenue, EBITDA, accounting profit, owner salary, and safe distributions are not interchangeable. The modeled low and high cases produce about $53,000 and $384,000, respectively, and actual distributable cash can be lower after personal taxes, emergency repairs, or additional working-capital needs.
Owner income$189KNet margin11%Revenue for target pay$1.7MBusiness difficultyHard
How much revenue does an Outdoor Adventure Park need to pay the owner?
Operating cash break-even is about $120,238 per month before owner take-home and reserves; supporting a $12,000 monthly owner target after reserves requires about $142,914 per month. The base case averages $150,000 monthly, or $1.8 million annually, from roughly 28,000 participants, about $55 blended admission yield, and group and ancillary revenue. Current U.S. pricing supports that ticket anchor: Go Ape's Arlington, Texas location lists adult aerial adventure at $54.95, youth at $49.95, and last-call at $41.95, while Sugar Land lists $49.95-$69.95 activity options. See Arlington adventure pricing and Sugar Land adventure pricing.
Base revenue build
About 28,000 annual participants in the stabilized case.
Approximately $55 blended admission yield after youth, group, and off-peak discounts.
Group events and ancillary purchases lift total annual revenue to about $1.8 million.
Average monthly revenue is a modeling convention; actual outdoor sales will be heavily seasonal.
What the sales target means
$120,238 per month covers modeled operating costs at an 84% non-labor gross margin.
$142,914 per month adds enough profit to fund a $12,000 owner target after reserves.
Revenue above the target is not automatically distributable; maintenance and working capital still matter.
Averages hide the fact that peak weekends may subsidize weak shoulder-season weekdays.
Owner income calculator
Adjust annualized park economics through monthly inputs to estimate residual owner cash after modeled reserves.
i
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
What does the owner-income calculator count as take-home?
The calculator treats owner income as residual cash after non-labor direct costs, employee payroll, fixed overhead, marketing, debt service, and modeled reserves, so it is closer to owner-discretionary cash after modeled reserves than to EBITDA or accounting net income. In the base case, $150,000 of monthly revenue at 84% gross margin creates $126,000 of gross profit. After $101,000 of operating costs, $25,000 remains; $9,250 is reserved and $15,750 remains for the owner.
That $15,750 is not automatically a tax-free draw. For an S corporation, the IRS says shareholder-employees must receive reasonable compensation for services before non-wage distributions; see the IRS reasonable-compensation guidance. Owner pay is excluded from employee labor here so the model shows total economic cash available before a tax professional determines wages, distributions, and retained cash.
1
Attendance and utilization
28K visits/year
The base model needs enough paid participants to spread fixed staffing, insurance, site, and debt costs across peak and shoulder days.
2
Ticket yield and mix
About $55
A $5 change in blended admission yield across 28,000 visits moves annual revenue by about $140,000 before demand or mix effects.
3
Labor productivity
$660K/year
Guides, supervisors, guest service, and maintenance are the largest controllable cash cost in the base model, excluding the owner's own manager role.
4
Season and weather
180 day-equivalents
The model assumes a full-year equivalent of about 180 productive operating days, so lost peak days can erase far more cash than lost winter weekdays.
5
Safety and reinvestment
12% reserve
Course inspections, harnesses, cables, platforms, trees, and rescue readiness need funded maintenance before distributions are treated as safe.
6
Debt and capital structure
$216K/year
The base debt-service assumption removes $18,000 every month before reserves, making financing structure a direct owner-income lever.
Want to test attendance, ticket mix, staffing, and debt in a full forecast?
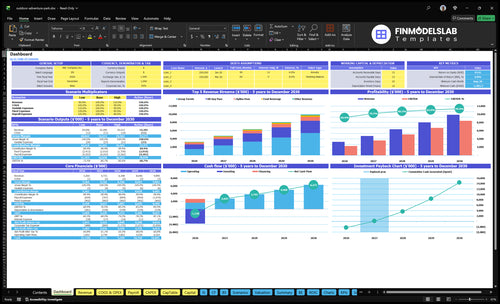
The Outdoor Adventure Park Startup Financial Model Template includes a park-specific dashboard for testing revenue, expenses, cash runway, and scenario assumptions. The dashboard preview is useful for checking whether participant counts, ticket yield, payroll, capital spending, and financing assumptions tell the same story before an owner treats projected profit as spendable cash.
How do seasonality and weather change safe owner draws?
Outdoor parks should not distribute a strong July as though it repeats twelve times. The base model averages $150,000 per month, but actual sales may concentrate in summer and fall, with closures from lightning, wind, ice, or severe heat. The National Weather Service's outdoor-venue lightning guidance calls for written plans, warning information, and shelter decisions; financially, that means weather can remove sellable capacity with little notice.
Cash discipline for peak months
Build owner draws from trailing cash flow and forward weather-adjusted bookings, not one weekend's sales.
Keep debt service, insurance, software, inspections, and core management costs funded through low season.
Pre-sell groups, schools, and corporate events to shift some demand into weekdays and shoulder periods.
Separate refundable booking liabilities from earned revenue so deposits are not mistaken for profit.
Ten-day sensitivity
At $1.8 million annual sales over 180 productive day-equivalents, the arithmetic averages about $10,000 per productive day.
Ten lost peak-equivalent days can therefore remove roughly $100,000 of revenue.
At an 84% gross margin, that is about $84,000 of lost gross profit before any labor or marketing savings.
If only $15,000 of costs flex away, post-reserve owner cash can fall by roughly $43,000.
The demand backdrop is large but does not remove local execution risk. The Bureau of Economic Analysis reported that U.S. outdoor recreation generated about $1.3 trillion of gross output and supported 5.2 million jobs in 2024; see the BEA outdoor recreation release. That evidence supports the category's scale, not a guarantee that one zipline park can fill its course. Local tourism, school calendars, drive time, competing attractions, weather, and repeat-visit behavior determine the actual attendance curve.
Can the park run without the owner on site?
Yes, but distributions usually fall unless sales rise enough to fund a replacement manager. The base calculator is owner-operated: $55,000 of monthly employee labor excludes the owner's general-manager work. BLS reports a May 2024 median wage of $77,180 for entertainment and recreation managers and notes nights, weekends, holidays, and peak-season work; see BLS manager wage data. With payroll burden, roughly $85,000-$95,000 of annual employer cost is a reasonable planning range.
Owner-operated economics
Base owner-income output: $189,000 after modeled reserves.
The owner covers general management, vendor oversight, scheduling, financial review, and escalation decisions.
That output combines compensation for real work with return on invested capital.
Legal payroll treatment depends on entity structure and should not be decided from the calculator alone.
Manager-run economics
A loaded replacement manager near $90,000 per year adds about $7,500 per month to labor.
At the base reserve settings, that can reduce annual owner cash by roughly $57,000.
Passive-owner economics therefore look closer to about $130,000 than $189,000 unless revenue or margin improves.
The owner should compare passive cash return with the capital invested, not with a manager salary.
Staffing depth matters below management too. BLS shows that Other Amusement and Recreation Industries employed 187,500 amusement and recreation attendants in May 2024 and also relied heavily on grounds, protective-service, customer-service, and management occupations; the BLS industry employment data underscores how labor-intensive recreation operations can be. For an adventure park, the financially useful KPI is not simply headcount. Track paid labor hours per participant, payroll dollars per open hour, and labor dollars per $1,000 of net ticket revenue while preserving the staffing and rescue coverage required by the course design.
Key Takeaways
The base model produces $189,000 of annual owner income on $1.8 million of sales after modeled tax and reinvestment reserves.
Operating break-even is about $120,238 per month, but a $12,000 monthly owner target requires about $142,914 of monthly revenue.
Owner-operated cash is not passive profit; hiring a replacement manager can reduce base owner cash toward roughly $130,000.
Peak-day attendance, ticket yield, labor productivity, weather downtime, maintenance discipline, and debt structure are the six largest owner-income levers.
What do low, base, and high owner-income scenarios look like?
The same park concept can produce very different owner cash depending on attendance, yield, payroll intensity, fixed overhead, marketing, financing, and reserves. The low case below assumes $1.32 million annual revenue and thinner 80% non-labor gross margin, producing $53,040 after reserves. The base case produces $189,000 on $1.8 million. The high case adds capacity and staffing rather than pretending extra revenue is free: revenue reaches $2.64 million, labor rises to $72,000 per month, fixed overhead to $23,000, marketing to $14,000, debt service to $24,000, and reinvestment reserve to 15%, leaving $384,408 of annual owner income.
Owner income scenarios
Compare coherent low, base, and high operating cases using the same calculator logic.
Outdoor Adventure Park low, base, and high planning cases
Scenario factor
Low CaseConservative
Base CaseStabilized
High CaseStrong demand
Launch modelOperating posture
Smaller single-course park
Slower weekday demand
Owner-led single site
Balanced groups and public admissions
Expanded capacity
Stronger group and premium mix
Typical setupRevenue and margin
$1.32M annual revenue
80% gross margin
$1.80M annual revenue
84% gross margin
About 28K participants
$2.64M annual revenue
86% gross margin
Larger premium mix
Cost driversMonthly cash load
$44K labor
$16K fixed overhead
$14K debt service
$55K labor
$18K fixed overhead
$18K debt service
$72K labor
$23K fixed overhead
$24K debt service
Owner income rangeAfter modeled tax + reinvestment reserves
$53,040
$189,000
$384,408
Best fitWho this case resembles
Demand still ramping
Limited weekday groups
Stabilized owner-operator
Recurring group sales
Established destination
Strong utilization
i
Planning note: Scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
Which cash-flow rules keep profit from becoming an unsafe distribution?
Safe owner cash must survive the off-season, debt schedule, maintenance calendar, taxes, and customer-booking liabilities. Accounting profit can coexist with cash already committed to winter work, annual insurance, spring hiring, or loan payments. SBA 7(a) loans can support real estate, working capital, refinancing, and equipment, with maximum loans of $5 million; the SBA 7(a) guidance illustrates why capital structure directly affects owner income.
The base case holds back 12% of positive profit for reinvestment plus a 25% tax reserve. The 12% is a planning assumption, not an industry rule, but an aerial course depends on engineered systems, PPE, platforms, cables, trees, and rescue equipment. OSHA's zip-line worker safety guidance calls for maintenance and regular platform and line checks. Pennsylvania guidance also lists harnesses, ropes, trolleys, cables, lifelines, weather, and rescue equipment; see the Pennsylvania inspection material. State rules differ, but inspection cash is not excess owner draw.
Pay these before distributions
Employee payroll, payroll taxes, and vendor bills.
Debt principal and interest due before the next peak cycle.
Tax reserve based on entity and owner circumstances.
Course maintenance, PPE replacement, inspection, tree work, and emergency repairs.
Use a distribution test
Confirm the next 90 days of fixed cash obligations are funded.
Stress bookings for weather cancellations and weaker weekdays.
Preserve any lender-required minimum liquidity or debt-service coverage.
Do not distribute deposits for future group events before the service is delivered.
What are the six biggest Outdoor Adventure Park income drivers?
The owner-income model is most sensitive to six operating levers: attendance and utilization, ticket yield and sales mix, labor productivity, season and weather, safety-driven maintenance and reinvestment, and debt structure. These drivers interact. Higher attendance can improve fixed-cost absorption, but only if the park has enough guide capacity and course throughput. Higher prices can add owner cash, but only if conversion and group demand hold. Lower maintenance spending can appear profitable for one season while creating safety, downtime, insurance, or capital problems later.
1. Attendance and course utilization
Fill the course before adding more fixed capacity
The base case assumes about 28,000 paid participants across 180 productive day-equivalents, or roughly 156 participants per productive day. Here's the quick math: 10 extra participants per day at a $55 blended yield add about $99,000 of annual revenue and $83,000 of gross profit at an 84% margin. If existing staffing absorbs most of that volume, post-reserve owner cash can increase by roughly $50,000.
Model capacity as safe, staffed participant slots by course and session rather than as a vague annual sales goal.
Track utilization by sellable session
Measure the percentage of safe, staffed participant slots sold, not merely total daily attendance.
Paid participants per open hour
Peak versus shoulder utilization
Booking conversion by session
Revenue per course-hour
If weekends are full but weekdays are empty, the next dollar should usually go to group sales and local partnerships before new physical capacity.
2. Ticket yield, groups, and ancillary mix
Protect realized yield, not just posted price
Go Ape's adult, youth, off-peak, and bundled prices show why realized yield matters more than one rack rate. The base model uses about $55 blended admission yield. A $5 yield increase across 28,000 participants adds about $140,000 of annual revenue; at 84% gross margin and the base 37% combined reserve rate, that can add roughly $74,000 of owner cash if demand and labor needs stay stable.
Groups can fill weak dayparts. Go Ape markets customizable corporate packages and discounts for groups of five or more; see its corporate-event program. Schools, scouts, birthdays, and companies can occupy otherwise unsold blocks while add-ons raise spend per booking.
Track realized revenue per participant
Separate price, discount, and ancillary effects so a busy park does not hide declining yield.
Net admission revenue per participant
Group discount percentage
Ancillary spend per participant
Revenue by public, school, and corporate segment
Test every promotion on contribution dollars, not gross ticket sales.
3. Labor productivity and owner coverage
Schedule to booked throughput without under-staffing safety
The base model carries $55,000 of monthly non-owner labor, or $660,000 annually, excluding the owner-manager. If 28,000 participants require 0.15 fewer labor hour each through better session staggering, cross-training, and check-in, the park saves 4,200 hours. At a planning loaded cost of $20 per hour, that is about $84,000 before reserves or $53,000 after the base reserve percentages.
Productivity cannot remove required rescue competence, checks, briefing, or monitoring. Savings should come from matching start times, reservations, and maintenance windows to booked demand.
Track labor against participants and sessions
Use a small operating scorecard that shows whether each paid hour is supporting safe throughput.
Labor hours per participant
Payroll dollars per $1,000 of revenue
Participants per guide-hour
Overtime and call-in hours
Keep the owner's own hours visible too; otherwise apparent profit may simply be unpaid management labor.
4. Season length and weather downtime
Model closures as lost capacity, not a footnote
Lightning, wind, ice, and storms can cancel sessions after marketing is spent and staff are scheduled. With $1.8 million of annual revenue across 180 productive day-equivalents, each equivalent day averages about $10,000 of sales. Ten lost peak-equivalent days therefore expose roughly $100,000 of revenue before any rescheduling or labor savings.
Some hourly labor may flex away, but management, debt, insurance, software, and much maintenance remain. Carry a weather reserve and measure how much canceled demand is successfully rescheduled.
Track sellable days and reschedule recovery
The strongest parks measure how much weather-disrupted demand is recovered rather than only counting cancellations.
Weather-closed hours
Reschedule conversion rate
Lost revenue per closed hour
Peak-day booking concentration
A park with too much revenue concentrated in a few Saturdays carries higher owner-income volatility than the same annual sales spread across groups and weekdays.
5. Safety maintenance and reinvestment reserve
Reserve before the repair becomes an emergency
The base calculator withholds 12% of positive profit for reinvestment: $3,000 per month, or $36,000 annualized, on base profit-before-reserves of $25,000. The high case raises the reserve to 15% for greater wear and equipment needs. These percentages are planning assumptions, not published industry standards.
OSHA requires maintenance and regular platform and line checks, while state rules may add inspections. If summer profit is distributed and $40,000 of off-season cable, platform, tree, or PPE work arrives, the owner must inject cash, borrow, or delay work. Reserve first.
Track maintenance as a funded liability
Build a rolling twelve-month maintenance plan with due dates and expected cash needs.
Inspection findings open versus closed
PPE replacement schedule
Maintenance dollars per participant
Reserve balance versus planned work
Owner distributions should fall before maintenance standards do.
6. Debt service and capital structure
Finance long-lived assets without starving seasonal cash
The base model assumes $18,000 of monthly principal-and-interest debt service, or $216,000 annually. It is a planning assumption, not a loan quote. If that payment eventually disappears and operations stay unchanged, profit before reserves rises by $216,000; after the base 37% combined reserve rate, theoretical owner cash rises by about $136,000 annually before other changes.
Match financing term to asset life and seasonality. A loan affordable on annual EBITDA can still create winter liquidity stress when payments are level but revenue is seasonal.
Track debt coverage before owner draw
Put debt service on the same weekly and monthly cash forecast as payroll and maintenance.
Annual debt service
Cash available before debt service
Debt-service coverage ratio
Lowest projected off-season cash balance
When debt coverage tightens, distributions should become more conservative before marketing, safety, or maintenance is cut blindly.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Outdoor Adventure Park Bundle
Choosing a selection results in a full page refresh.