How Much Perovskite Solar Cell Owners Make at $111M Year 1 Revenue
Perovskite Solar Cell Development Bundle
A perovskite solar cell business owner can’t treat revenue as take-home pay Based on the researched assumptions, the company produces $111M in Year 1 revenue with about $831M of contribution after listed unit costs, revenue-based production costs, shipping, and commissions Known fixed overhead is at least $705k/month, before technical payroll, unlisted marketing, debt, taxes, and reinvestment reserves Founder pay should be modeled as approved compensation first distributions only make sense after R&D runway and pilot production reserves are funded
Owner income$220k baseNet margin52%–71%Revenue for target pay$1.5MBusiness difficultyHard
Want to test your founder pay?
Owner income calculator
Estimate owner take-home and the target-pay gap from revenue, margin, costs, reserves, and target pay.
!
Planning note: Research-based planning estimate only. Not guaranteed salary, tax advice, or owner distribution advice.
Want the six main income drivers?
1
Commercial Scale
$11.1M-$298.7M
Year 1 revenue is $11.1M and Year 5 reaches $298.7M, so scale is the main path to founder take-home as margin holds near 74%.
2
R&D Runway
-$8.98M
Cash trough hits -$8.98M in Month 11, so runway decides whether funded R and D reaches scale without extra dilution.
3
License Revenue
High
Licensing and joint-development fees can add income before full volume production, which lifts take-home without more plant load.
4
Pilot Yield
74%
Pilot yield protects the near 74% contribution margin, so small process gains turn into real profit fast.
5
Payroll Load
$705K/mo
Later fixed overhead runs near $705K per month, so payroll and lab spend need tight control to keep cash in the business.
6
Reserve Policy
24 mo
A 24-month payback means reserve rules decide how much profit is kept for scale versus paid out to the founder.
Want to see the Perovskite Solar Cell Development model?
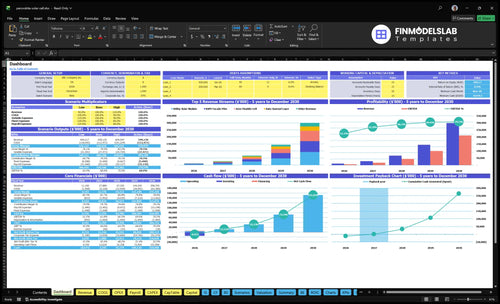
This dashboard maps a $111M to $2987M revenue ramp, ~74% contribution margin, and $705k monthly fixed overhead in the Perovskite Solar Cell Development Financial Model Template. It also shows product mix, R&D, staffing, pilot costs, runway, scenarios, and owner pay after reserves—use it as a planning tool, not tax-ready income or a guaranteed salary.
Owner-income model highlights
Reserve-based owner pay
Revenue and margin view
Scenario and runway output
How much revenue does a perovskite solar company need to pay the owner?
There’s no universal revenue threshold for owner pay in Perovskite Solar Cell Development; it depends on gross margin, R&D payroll, fixed overhead, reserves, and pilot yield. The model shows $111M in Year 1 revenue and about $831M in contribution before known fixed costs and unlisted R&D payroll, with known fixed overhead of at least $846k/year. So owner pay should be tested after reserve policy, lab staffing, debt service, and commercialization costs.
What drives owner pay
Gross margin sets cash left.
R&D payroll can move fast.
Fixed overhead starts at $846k.
Reserves come before owner draws.
What to test first
Model pay after debt service.
Check pilot yield assumptions.
Set a reserve policy first.
Then size commercialization spend.
What affects perovskite solar cell business profit margins?
Perovskite Solar Cell Development margins are driven by material cost, production yield, quality control, encapsulation, stability testing, shipping, commissions, defects, and pilot throughput. At unit costs from $170 for Aero Flexible Cell to $1,050 for Portable Power Patch, revenue-based production costs already run about 15% to 30% by product, and year 1 shipping plus commissions can add another 75% of revenue. For the quick math, see How Increase Perovskite Solar Cell Development Profits?—owner income starts only after reserves, not just gross profit.
Main margin drivers
Material cost sets base unit margin.
Yield loss lifts cost per good cell.
QC and encapsulation add rework cost.
Pilot throughput spreads fixed costs.
Cash drains to watch
Year 1 shipping can reach 75%.
Commissions cut cash after the sale.
Defects eat margin and delay cash.
Reserves come before owner pay.
How does scaling a perovskite solar business affect owner income?
Perovskite Solar Cell Development can lift owner value fast, but short-term take-home often stays tight because cash gets pushed into production, testing, hiring, and reserves. Revenue in the model rises from $111M in Year 1 to $2,987M in Year 5, yet that does not mean the founder can pull more cash right away. For a scientist-founder, pay often stays salary-based in lab and pilot stages; for a CEO-founder, income depends on board-approved budgets and runway until contracts, licensing, and repeat production stabilize cash.
Early-stage pay
Salary often comes first
Lab and pilot spend uses cash
Testing delays owner draws
Reserves protect runway
Scale-stage pay
Value can rise faster than pay
Contracts can steady income
Licensing can improve cash flow
Repeat production supports higher pay
Key Takeaways
Stage drives whether founder pay exists at all.
Cash timing matters more than headline revenue.
Pilot yield and overhead decide real take-home.
Reserves should come before distributions.
Compare lean, base, and high owner-income planning scenarios
Owner income scenarios
Owner pay shifts fast here because revenue, payroll, and reserves all move as production scales. Higher sales do not automatically mean higher take-home.
Low, base, and high cases show how funding and scale change owner pay.
Scenario
Low CaseLow Case
Base CaseBase Case
High CaseHigh Case
Launch model
This is the lean R&D case, where owner pay starts only if funding covers payroll and reserves.
This is the funded pilot case, where owner pay depends on how much cash is kept in the business.
This is the stronger commercial-partnership case, where owner pay improves only after full operating costs are covered.
Typical setup
Year 1 revenue is $11.1M and EBITDA is $5.7M, but about $1.1M of annual fixed overhead and early-stage staffing keep cash tight.
Year 3 revenue is $67.25M and EBITDA is $44.7M, with scale across all five product lines, so owner pay still depends on payroll, reserves, and debt.
Year 5 revenue is $298.7M and EBITDA is $210.6M, with large output across utility, facade, aero, auto, and portable lines, so owner pay can rise only after full costs and reserves.
Cost drivers
R&D payroll
fixed facility lease
testing and compliance
reserve funding
launch cash burn
Product mix
staffing scale
shipping and commissions
quality control
overhead retention
High volume mix
lower unit prices
automation
partnership sales
reserve policy
Owner income rangeBefore owner reserves
No owner draw yetCash tight
Moderate owner draw possiblePilot funded
Strongest owner draw potentialScale upside
Best fit
Use this if you want a cautious view of year one before sales and funding are stable.
Use this for a funded pilot plan with real production, but with cash still held back for growth.
Use this to test upside when partnerships, scale, and cash retention all work together.
!
Planning note: Scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distributions.
Perovskite Solar Cell Development Core Six Income Drivers
Commercialization Stage
Commercialization Stage
The first filter is stage. A research-only or grant-funded company may pay a salary, but it may not have a real profit draw yet. In a pilot-line stage, owner income depends on yield, signed contracts, and cash timing more than headline revenue.
Do not compare lab-stage pay to $2,987M in Year 5 manufacturing revenue. As the business moves into licensing or commercial partnerships, cash flow can improve fast, but reinvestment needs also rise, so take-home pay only grows when margin and cash reserves are stable.
Track stage before pay
Estimate owner income from the current stage, then build up from there. Use revenue type, gross margin, yield, and fixed costs to decide whether pay should be salary-only, capped, or partly distributed. One-time milestones help cash flow, but they do not equal steady owner income.
Track signed contracts and milestones.
Track pilot yield and rework.
Track payroll limits from funding.
Track reserve needs before draws.
If the company is still pre-scale, keep owner pay conservative until contracts and cash collections are repeatable. That keeps the business from paying the founder out of money needed for lab work, testing, and the next production run.
Technical Payroll And Lab Overhead
Technical Payroll And Lab Overhead
For perovskite solar cell development, scientists, engineers, lab space, equipment maintenance, testing, certification, patent work, software, and compliance all hit before the owner sees a draw. The known recurring fixed costs are $45k/month facility lease, $12k/month lab equipment maintenance, $55k/month software, and $8k/month IP legal fees, or $120k/month before payroll.
That means owner take-home cannot be finalized from revenue alone. If payroll, test spend, or certification work rises, cash gets used up before distributions, so even a good sales month may not turn into profit you can pay out. One line says it plainly: recurring lab overhead sets the floor, not the upside.
Track Overhead Before Pay
Start with a monthly model that separates revenue, direct project costs, and recurring lab overhead. Here’s the quick math: $120k/month fixed overhead equals $1.44M/year before any payroll or variable testing cost. If cash in is below that floor plus staff pay, founder distributions should stay at zero.
Track these inputs every month: headcount, facility lease, equipment maintenance, software, IP/legal, and certification spend. Then tie owner pay to cash left after those bills, not to booked revenue. If onboarding a new test line adds more compliance or software seats, update the forecast right away.
Watch monthly burn versus cash.
Price in test and compliance load.
Delay draws until overhead is covered.
Funding And Runway
Cash Runway Sets Pay
Grants, non-dilutive funding, customer-paid development, and investor budgets can cover founder salary, but they do not create owner distributions. Runway is the cash left after lab work, payroll, testing, IP/legal, and pilot failures. With fixed overhead at $705k/month before full staffing, that is $8.46M a year before more hiring.
Even with $111M in Year 1 revenue, founder pay should stay conservative if reserves are thin. Cash timing controls pay timing: if grants, milestones, or customer receipts land late, the business can show sales and still lack safe money for distributions.
Track Burn Before Raising Pay
Measure runway in months, not just revenue. Build a 13-week cash forecast and map each funding source against the $705k/month burn. The key test is simple: can the company fund the next payroll, testing cycle, and pilot loss without a new check?
For founder pay, set a conservative base salary until committed cash covers the next hiring wave and expected failures. Track cash in bank, committed funding, and monthly burn; those three numbers decide whether pay is safe or a runway risk.
Pilot Production Yield
Pilot Production Yield
Yield is the share of pilot units that pass spec the first time. In this business, weak yield turns booked sales into scrap, rework, extra testing, disposal, and warranty cost, so owner cash drops fast. With revenue-based production costs already adding 15% to 30%, pilot loss hurts hardest on high-cost lines like the $6,750 utility module and $1,050 portable power patch.
Here’s the quick math: every bad unit adds cost without adding revenue. A $79 facade film or $45 auto sunroof layer can absorb defects, but a slip in yield on higher-value parts can erase margin and delay profit draws. What this hides: the cash hit is bigger if failures also raise warranty claims and lab retest time.
Tighten First-Pass Pass Rate
Track first-pass yield (units that pass without rework), scrap %, rework hours, test failure rate, and warranty returns by product line. Use those inputs to forecast how many sellable units you get from each pilot batch, then compare that to the cost base before paying owner draws.
Measure yield by line weekly.
Separate scrap from rework.
Tag failures by process step.
Price in 15% to 30% loss.
Pause scale-up below target.
If yield improves, more of each sales dollar becomes usable cash. If process tuning drags past one pilot cycle, keep distributions conservative and use the savings to fund repeat tests and defect fixes.
Reinvestment Reserves
Reinvestment Reserves
Reinvestment reserves are cash the company keeps before any founder distribution. In perovskite solar cell development, that matters because R&D cycles, certification delays, pilot failures, hiring, equipment access, and fundraising gaps can use cash fast, even when contribution margin is near 74%. Profit on paper does not mean owner pay is safe.
With fixed overhead at $705k/month before full staffing, the reserve rule has to come first. If the company is still in research or pilot scale-up, retained earnings should stay inside the business until cash timing is stable; otherwise founder take-home can break runway fast.
Set the reserve floor first
Build the reserve into monthly forecasting with three inputs: expected overhead, timing of R&D and certification cash needs, and the size of the next pilot or hiring wave. Treat retained earnings as a required line item before any distribution. Don’t count month-end cash as spendable until the reserve floor is covered.
Track cash by milestone.
Hold back failed-pilot cash.
Delay founder pay when tight.
If revenue grows from $111M toward $2,987M, reserve needs can still rise faster than profit if scale-up needs labs, testing, and certification. The right move is to cap distributions until cash covers the next operating gap, not just the next payroll.
Licensing And Joint-Development Revenue
Licensing Revenue
Licensing and joint-development deals can pay payroll before product volume scales. Milestone payments and paid pilots bring in cash now, but they are one-time; only royalties can act like steadier income, and even then only if contracts renew and performance stays on spec.
The key inputs are pilot count, milestone size, royalty rate, renewal term, and payment timing. That matters because product revenue is expected to ramp from $111M to $2,987M, but scale-up still needs cash, and fixed overhead is about $705k/month.
Track Contract Cash
Measure booked cash, not headline deal value. Split one-time milestones from recurring royalties, then forecast founder pay only on cash that is billed or highly likely to land this month. If a pilot slips 90 days, payroll still clears on time, so keep a monthly cash bridge tied to contract events.
Milestone cash and timing
Royalty receipts by quarter
Paid pilot conversion rate
Renewal terms and triggers
Push for clear acceptance tests, renewal clauses, and payment dates. A few strong contracts can support owner pay, but weak terms leave you exposed when manufacturing scale needs working capital and the lab still burns cash before product sales mature.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.