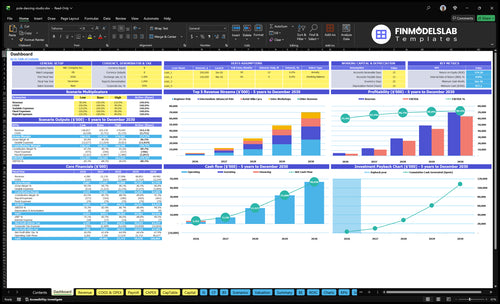
How Much Does A Pole Dancing Studio Owner Make? $3223M Year 1 EBITDA
Pole Dancing Studio Bundle
You’re not just asking about class sales you’re asking what cash can reach the owner after payroll, rent, fees, marketing, reserves, and reinvestment This US pole dancing studio model shows $5781M in Year 1 activity-based revenue and $3223M in Year 1 EBITDA, but owner take-home is not the same as gross sales or instructor wages
Estimate owner take-home and target-pay gap from revenue, margin, costs, reserves, and target pay.
!
Planning note: This is a researched planning estimate, not guaranteed salary, tax advice, or owner distribution advice. It shows pre-tax owner income and excludes personal taxes, financing guarantees, and distributions not approved by cash flow.
Want the six income drivers?
1
Class Utilization
45%-82%
More filled classes lift revenue fast, and the model assumes occupancy rises from 45% in year 1 to 82% by year 5.
2
Pricing Power
$150-$190
Core monthly pricing moves from $150 to $190, so small price gains flow straight into take-home if fill stays solid.
3
Instructor Mix
$235K-$355K
Payroll swings hard as pole and front-desk staffing scales, and the model ranges from about $235K to $355K a year.
4
Rent Capacity
25-28d
The studio only earns if schedules are full, and 25 to 28 billable days a month against $4,500 rent decides how fast overhead gets covered.
5
Private Events
$2.5K-$10K
Private lessons and parties add higher-margin cash, growing from $2,500 to $10,000 a month and lifting average order value.
6
Retention Spend
10%-4%
Holding clients longer and trimming ad spend from 10% to 4% protects margin and lowers the cost to refill classes.
Want to see the Pole Dancing Studio model dashboard?
How much revenue does a pole dancing studio need to pay the owner?
For a Pole Dancing Studio, the owner pay target sits on top of a simple planning formula: (payroll + fixed costs + owner pay + taxes + debt + reserves) ÷ gross contribution rate. With Year 1 costs at 165%, each $1.00 of revenue leaves about $0.835 before fixed payroll, rent, and overhead, and the known base load is $235,000 payroll plus $79,200 fixed operating costs, or about $376,317 in revenue before owner pay.
Quick math
$235,000 payroll
$79,200 fixed costs
$314,200 base total
$376,317 revenue needed before owner pay
Revenue drivers
Fill more class slots
Raise member count and pricing
Add private lessons and parties
Keep occupancy high
How much can a pole dancing studio owner take home?
A Pole Dancing Studio owner can take home profit only after expenses, reserves, debt, taxes, and reinvestment—not gross sales or instructor pay. In the Year 1 model, activity revenue is $5.781M and EBITDA is $3.223M before owner draw, so the pre-draw EBITDA margin is 55.8%; connect that to What Is The Most Important Indicator Of Success For Your Pole Dancing Studio?.
Owner take-home
Start with $3.223M EBITDA
Subtract taxes and debt payments
Hold cash for repairs
Distribute only safe surplus
What changes pay
Owner teaching adds labor pay
Reserves reduce current distributions
Reinvestment delays take-home cash
Later EBITDA needs review
Does a pole dancing studio owner make more by teaching classes?
A Pole Dancing Studio owner can make more by teaching only if it replaces paid instructor labor or keeps classes open that would otherwise be canceled. Here’s the quick math: the model already includes a $55,000 lead instructor plus two Year 1 pole and aerial instructor FTE at $45,000 each, or $145,000 total. So owner teaching lifts short-term margin, but it also brings burnout risk, schedule limits, and dependence if beginners need the owner to keep moving.
When it helps
Replaces a $45,000 FTE cost
Keeps profitable classes open
Raises short-term margin
Fills weak time slots
When it hurts
Creates burnout and schedule strain
Limits the owner’s growth time
Builds dependency for beginners
Slows scale if classes need coverage
Key Takeaways
Fill class slots before adding more space.
Raise prices gradually and protect beginner conversion.
Control payroll hours; utilization must cover instructor wages.
Keep students longer to cut ad spend.
Compare lean, base, and high pole studio owner income scenarios
Owner income scenarios
Occupancy, billable days, class mix, and payroll drive owner income here. Lean, base, and high cases show how fast a studio can move from starter-year cash to a much stronger run rate.
Three planning cases for owner income.
Scenario
Lean CaseLean case
Base CaseBase case
High CaseHigh case
Launch model
This is the opening-year, lower-income path.
This is the modeled mid-case path.
This is the stronger earnings path with the highest modeled fill and add-on sales.
Typical setup
The studio runs at 45% occupancy across 25 billable days, with $481,750 monthly revenue, $235,000 payroll, $2,500 ancillary revenue, and $79,200 annual fixed overhead.
The studio reaches 70% occupancy across 27 billable days, with $1.537M monthly revenue, $310,000 payroll, $6,000 ancillary revenue, and $79,200 annual fixed overhead.
The studio runs near full capacity at 82% occupancy across 28 billable days, with $2.582M monthly revenue, $355,000 payroll, $10,000 ancillary revenue, and $79,200 annual fixed overhead.
Cost drivers
45% occupancy
25 billable days
$2,500 ancillary revenue
$235,000 payroll
$79,200 fixed overhead
70% occupancy
27 billable days
$6,000 ancillary revenue
$310,000 payroll
$79,200 fixed overhead
82% occupancy
28 billable days
$10,000 ancillary revenue
$355,000 payroll
$79,200 fixed overhead
Owner income rangeBefore owner reserves
$3.2M EBITDA proxyLean proxy
$24.2M EBITDA proxyBase proxy
$63.4M EBITDA proxyHigh proxy
Best fit
Use this to test a softer launch, slower fill, or a heavier ad spend start.
Use this as the middle-year plan and review EBITDA margin before turning it into owner pay.
Use this only to test upside, and review the margin math before treating EBITDA as owner pay.
!
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distributions; EBITDA means operating profit before interest, taxes, depreciation, and amortization.
Pole Dancing Studio Core Six Income Drivers
Class utilization
Class Utilization
When paid students fill more class spots, revenue rises without rent rising dollar for dollar. In this model, occupancy moves from 45% in Year 1 to 82% in Year 5, and billable days rise from 25 to 28 per month. That raises owner take-home because every empty pole leaves room capacity, instructor time, and peak-hour rent unpaid.
Track paid attendance, not just inquiries or social media interest. More filled slots spread fixed costs across more students, so the same studio can produce more profit before you add another room or another lease.
Measure Fill Rate, Not Buzz
Use a simple fill-rate check: paid spots ÷ available spots. Watch it by class type, day, and hour, because a full prime-time class helps more than a full off-peak class. If one slot underperforms, test schedule changes, class caps, or beginner-to-next-level paths before adding more sessions.
What this hides is no-shows and churn. Forecast from booked and paid seats, then compare results against the studio’s $4,500 monthly rent and $6,600 fixed overhead so you can see when higher utilization actually lifts profit and owner draw.
Rent and capacity
Fixed rent only pays when seats sell
The studio’s rent is fixed at $4,500 a month, and total fixed overhead is $6,600, so rent is about 68% of the fixed base. That means profit depends on how many paid students fit into the same lease. If poles, spacing, ceiling height, rigging, or peak-hour slots limit class size, empty room time still costs the owner money.
Track paid attendance by class, room, and peak hour. Here’s the quick math: the overhead stays flat, so every extra filled spot helps cover the $6,600 before owner pay. The risk is simple: if the schedule is full of low-fill classes, the studio pays for space it cannot sell.
Measure seat fill, not just interest
Set a hard capacity per room based on poles, safe spacing, and ceiling height, then compare it to paid attendance every week. Use booked spots, peak-hour fill rate, and revenue per class hour to see which slots actually pay their share of rent. If a class does not cover its slice of the fixed lease, move it, merge it, or cut it.
Count paid students, not inquiries.
Review fill by hour and room.
Protect prime slots first.
What this hides: a packed off-peak class may still underperform if peak slots stay half empty. So forecast owner income from paid seats per hour, not from total bookings alone.
Private lessons and parties
Private Lessons and Parties
Private lessons and bachelorette parties add higher-value sales on top of core classes. Modeled revenue rises from $2,500 per month in Year 1 to $10,000 per month in Year 5, so this driver can lift owner income without adding equal rent.
Here’s the quick math: track booked hours, price per session, and labor time. These offers improve revenue per available hour by using off-peak or premium weekend slots. The risk is real, though: if staff time shifts away from recurring members, class retention and cash flow can slip.
Fill Idle Hours First
Measure private bookings, party size, average ticket, and the share of sales placed in empty hours. Off-peak fills should come before prime class time, because that is where margin usually improves most. Also track instructor hours per booking so these sales do not quietly eat profit.
Price for the hour, not just the event. A private lesson, choreography session, workshop, or showcase event should cover prep, teach time, and cleanup. If demand grows from $2,500 to $10,000 monthly, protect recurring members by limiting how many premium blocks staff can sell each week.
Retention and marketing efficiency
Retention and marketing efficiency
When students stay longer, the studio spends less to keep classes full. Marketing advertising starts at 10% of revenue in Year 1 and falls to 4% in Year 5, so better retention directly lifts net owner income by cutting replacement spend. Customer acquisition cost, or CAC, only matters after a student converts and keeps attending.
The key inputs are beginner progression, repeat workshop sign-ups, referrals, and churn. Better onboarding and community keep more seats paid for, so fewer ad dollars go to refill empty spots. Lower churn means steadier cash flow and less pressure on the owner’s draw when class volume dips.
Track churn before you raise ad spend
Measure how many beginners reach their next class level, how often students book repeat workshops, and how many referrals turn into paying members. If retention slips, ad spend rises to replace lost students, and that eats margin fast. Year 1 at 10% of revenue is a heavy load; Year 5 at 4% only works if students keep coming back.
Track beginner-to-next-level conversion.
Count repeat workshop bookings monthly.
Record referral-to-paid-student rate.
Watch churn after first three visits.
Compare ad spend to retained revenue.
Instructor payroll mix
Instructor Payroll Mix
Instructor payroll is the main controllable labor cost in a pole studio. Year 1 payroll is $235,000: a $60,000 studio manager, a $55,000 lead instructor, two $45,000 instructors, and $30,000 front desk staff. By Year 5, payroll reaches $355,000, up $120,000 or about 51%, so labor control directly changes profit and owner pay.
Owner teaching only saves money when it replaces hired hours. If it adds classes without cutting paid shifts, cash outflow stays high. Hired instructors help cover more slots, but they need enough paid attendance to protect margin; empty classes still carry the same wage cost.
Trim Unfilled Teaching Hours
Track payroll by role, teaching hour, and class block. The key inputs are booked classes, instructor hours, front desk coverage, and utilization (filled class slots). Here’s the quick math: if a class does not cover the extra labor it creates, it lowers owner take-home even if the studio looks busy.
Use owner teaching for peak gaps, beginner classes, or private lessons that would otherwise need hired coverage. Keep a monthly labor plan tied to expected paid attendance. If a role is underused, shorten the shift or cut coverage before payroll drifts toward $355,000.
Pricing and memberships
Pricing and memberships
Pricing sets revenue per student and how predictable monthly cash is. In Year 1, beginner pole is $150, intermediate advanced pole $170, aerial silks lyra $160, and intro workshops $35. By Year 5, those rise to $170, $190, $180, and $45, or about 11.8% to 28.6% higher, so small price moves can lift owner pay without adding class hours.
Memberships and class packs turn one-off visits into repeat cash. The key inputs are active members, class mix, pack redemption, and discount use. Intro offers should push students into beginner classes, not train them to wait for deals. If discounts become the norm, cash flow gets less steady and profit drops even when attendance looks busy.
Track mix, not just sales
Track average revenue per student, intro-to-beginner conversion, repeat purchase rate, and the share of sales from memberships versus drop-ins. Here’s the quick math: a $35 intro that converts into a $150 monthly beginner plan is a good funnel; a cheap intro that stalls is not. Price should rise only when retention holds, so higher rates feed owner income instead of shrinking bookings.
Watch discount depth and expiry dates on class packs. If packs linger unused, cash looks strong but revenue is delayed; if they are too short, churn rises and refill costs go up.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.