How Much Prefab Home Construction Owners Make At 30 Homes/Year
Prefabricated Home Construction Bundle
A prefab home builder owner income estimate can reach about $98M in Year 1 operating income before taxes, debt service, reserves, and reinvestment if the company delivers 30 homes at the provided mix and prices Here’s the quick math: $1352M revenue minus $164M unit-level direct costs, $5408k revenue-based factory costs, $7436k sales and marketing, and $782k listed fixed overhead and payroll These are researched assumptions, not a guaranteed salary or automatic owner distribution Owner take-home depends most on delivered homes, average contract value, gross margin, install variance, factory overhead, and cash reserves
Owner income$9.4MNet margin69.8%Revenue for target pay$13.5MBusiness difficultyHard
Want to test your owner take-home?
Owner income calculator
Estimate owner take-home and target-pay gap from completed-home revenue, gross margin, costs, reserves, and target pay. Use monthly operating numbers, not leads, deposits, or backlog.
!
Planning note: This is a researched planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
Want the six main income drivers?
1
Homes Delivered
30-150
Completed homes drive the whole model: 30 in Year 1 and 150 in Year 5 lift revenue from $13.52M to $76.084M.
2
Contract Value
$450.7K
Average revenue per home is about $450.7K in Year 1, so mix shifts toward larger units raise owner income fast.
3
Factory Margin
60%
Factory costs run about 40% of revenue, so the remaining 60% is the pool that funds overhead and owner profit.
4
Install Control
$3K-$27K
Logistics and on-site install cost from $3K to $27K per home across the mix, so tighter crew and transport control protects take-home.
5
Pipeline Timing
55%
Year 1 sales and marketing is heavy at 55%, and permit delays slow completed-home billing, so pipeline speed changes cash timing.
6
Cash Reserves
$1.1M
Minimum cash is about $1.141M in Month 1, so thin reserves can delay owner draws even when profit is strong.
Want to check owner income in the Prefabricated Home Construction model?
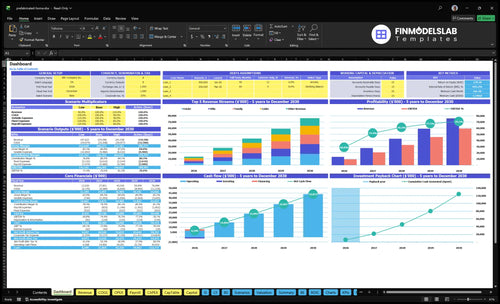
Screenshot shows the full Prefabricated Home Construction model: dashboard, home-type revenue, unit pricing, manufacturing and installation costs, revenue-based COGS, sales and marketing, fixed overhead, payroll, debt service, reserves, and owner pay scenarios in the Prefabricated Home Construction Financial Model Template. Homes delivered range from 30 to 150, revenue from $1,352M to $7,608M, and operating profit before excluded items from about $98M to $610M. Open it to compare cases.
Owner-income model highlights
Owner pay scenarios
Homes delivered: 30-150
Revenue: $1,352M-$7,608M
Profit: $98M-$610M
What affects prefab home construction gross margin the most?
Prefab home construction gross margin is driven most by install overruns and the factory cost stack, because the build is funded before the final site work is done. The cost range runs from $22k per Studio to $197k per Estate, while sale prices run from $180k to $16M; for a quick cost benchmark, see How Much To Start Prefabricated Home Construction Business? In Year 1, revenue-based factory costs add 40% and sales plus digital marketing add 55%, so margin depends on tight site readiness, transport distance, crane timing, rework, and warranty control.
Biggest margin leaks
Install overruns hit after funding.
Year 1 factory costs add 40%.
Sales and digital marketing add 55%.
Unit direct costs range from $22k to $197k.
Best controls
Standardize designs to cut variance.
Control material buying and pricing.
Keep sites ready before delivery.
Reduce punch-list trips and warranty claims.
How much can a prefab home builder make per year?
Under the provided Year 1 assumptions, a Prefabricated Home Construction owner could generate about $9.8M in operating profit before taxes, debt service, warranty reserves, and reinvestment; for startup cost context, see How Much To Start Prefabricated Home Construction Business?. Here’s the quick math: 30 completed homes produce $13.52M revenue, with operating profit landing near $9.82M after listed costs.
Year 1 math
$13.52M revenue from 30 homes
$1.64M unit direct costs
4.0% revenue-based factory costs
$11.34M estimated gross profit
Owner draw limits
5.5% sales and marketing load
$782k overhead and payroll
$9.82M operating profit capacity
Cash depends on deposits and progress payments
How many prefab homes to build to make six figures?
To make six figures in Prefabricated Home Construction, count completed and installed homes, not leads, deposits, or backlog. With Year 1 average revenue per delivered home of about $4,507k and gross profit per home of about $3,781k after listed direct and revenue-based factory costs, the business still has to clear $782k in annual fixed overhead plus sales and marketing, reserves, debt service, and reinvestment before owner pay is real. So owner pay is a planning output, not a promise.
Count the right units
Completed homes drive cash
Deposits are not full revenue
Backlog is not the same
Installed homes fund payroll
Pay the full stack first
Cover $782k fixed overhead first
Then sales and marketing
Keep reserves and debt service
Reinvest before owner pay
Key Takeaways
More finished homes spread fixed costs and lift income.
Factory margin protects take-home more than top-line growth.
Delays in permits and installs can trap cash.
Reserves matter because overhead stays due every month.
Scenario objective: Compare low, base, and high owner-income cases from operating assumptions
Owner income scenarios
Owner income moves with homes delivered, unit mix, and how much factory and field overhead each unit absorbs. These cases show profit before tax, debt, land, reserves, and reinvestment.
Low, base, and high cases for owner income planning.
Scenario
Low CaseLow case
Base CaseBase case
High CaseHigh case
Launch model
This is a lower-earnings path built on Year 1 volume and a narrower unit mix.
This is the modeled middle path built on Year 3 scale and steadier throughput.
This is the stronger earnings path built on Year 5 scale and fuller plant utilization.
Typical setup
About 30 homes, $13.52M revenue, and roughly $451k average contract value, with light owner pay and no tax, debt, land, or reserve load modeled.
About 90 homes, $43.03M revenue, and roughly $478k average contract value, with the core plant, sales team, and project flow running closer to plan.
About 150 homes, $76.084M revenue, and roughly $507k average contract value, with lower overhead per unit and tighter install variance.
Cost drivers
Homes delivered
average contract value
installation variance
factory overhead
owner pay policy
Homes delivered
average contract value
gross margin
overhead load
debt service
Homes delivered
premium unit mix
gross margin
overhead dilution
reinvestment pace
Owner income rangeBefore owner reserves
$9.4M - $10.0MConservative
$32.8M - $33.7MModeled base
$59.4M - $61.0MUpside case
Best fit
Use this to test the floor if sales ramp slowly or installs slip.
Use this as the main planning case for budgets and hiring.
Use this to test upside if volume, pricing, and production all stay on track.
!
Planning note: Scenario ranges are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distributions; this model also excludes tax, debt, land, full staffing, and warranty reserve assumptions.
Prefabricated Home Construction Core Six Income Drivers
Homes Delivered Per Year
Homes Delivered Per Year
This driver is the count of homes that are fully built, set, installed, and collected. Going from 30 homes in Year 1 to 150 homes in Year 5 spreads factory and management costs across more units, so owner income rises only if the homes actually close and cash comes in.
Here’s the quick math: $522k of fixed expenses and $260k of listed payroll keep running even when crews are idle. So downtime hurts fast. Poor quality, permit delays, install bottlenecks, and cash gaps can turn higher volume into thin or negative profit.
Track Finished Homes, Not Starts
Measure the flow from sold to started to finished to installed to collected. The key input is completed homes, not just units in the pipeline. If the gap between starts and paid installs grows, cash gets stuck and owner draw gets squeezed. No handoff, no revenue.
Track homes by stage weekly
Watch permit clearance dates
Log install crew idle days
Review collection timing fast
Use a weekly schedule that checks permits, foundation readiness, utility hookup, and crew dates before each set. If a home sits waiting, the $522k fixed load still burns, so every lost week cuts margin and slows the cash available for owner pay.
Installation And Logistics Control
Install and Transport Margin
After the factory build, transport and onsite set costs can still drain profit. The disclosed unit range is $2k to $15k for modular logistics and $1k to $12k for onsite installation, so site-to-set cost can run $3k to $27k before rework. If crane time, weather, or crew idle time slips, owner take-home falls fast.
Track delivery distance, foundation readiness, utility timing, and punch-list visits. A profitable build can turn into a cash drag if the home is done in the factory but not ready on site.
Control the Set-Day Schedule
Build a site checklist before fabrication starts: driveway access, crane booking, foundation sign-off, utility coordination, and weather backup. That keeps install hours from drifting and protects gross margin. One delayed set day can add labor, equipment standby, and a second trip.
Measure planned vs. actual install cost on every job. If rework or punch-list visits show up often, raise the installed price or tighten handoff rules. The goal is simple: finish on one visit, collect faster, and keep more of the contract as owner profit.
Factory Gross Margin
Factory Gross Margin
Factory gross margin is the money left after direct materials, direct factory labor, and the 40% factory load for overhead, indirect labor, maintenance, quality control, and waste. With a $180k Studio and $22k direct cost, that burden is $72k, leaving $86k before install, sales, and admin. If this margin slips, owner pay falls fast because the factory is where most value is made or lost.
The risk sits in lumber and steel, insulation and glass, labor hours, scrap, and rework. A small hit in yield can erase a lot of take-home, because overhead keeps running whether the unit ships cleanly or not. Cleaner builds, tighter specs, and shorter cycles protect gross profit before the rest of the business takes its cut.
Protect the Build Margin
Measure this as revenue minus direct build cost minus the 40% factory load. Track it by model, because a Studio at $180k with $22k direct cost behaves very differently from a higher-price home with a larger material bill. If margin by model is weak, the owner is paying for waste, not growth.
Track material yield by model.
Watch rework hours weekly.
Lock purchase prices early.
Standardize option packages.
Cut build cycle time.
Use labor-hours-per-unit and scrap rate as your early warning signs. When those move the wrong way, gross margin drops before cash does, and that shows up later as thinner payroll room, tighter reserves, and less owner draw.
Average Contract Value
Average Contract Value
Average contract value is the price per home after model mix and add-ons. In this business, Year 1 sale prices run from $180k for a Studio to $16M for an Estate, with blended Year 1 revenue per modular home near $4.507M. Higher contract values raise gross profit only when the extra price covers design time, factory hours, transport, site coordination, and punch-list work.
Here’s the catch: bigger scope helps owner income only if pricing moves with complexity. If finishes, design changes, delivery distance, or installation scope rise without a matching price bump, revenue turns into rework and margin slips. That can push out cash collection and make owner pay less reliable, even when top-line sales look strong.
Price the Full Scope
Track base price, change orders, delivery miles, install scope, and punch-list hours on every job. That tells you whether the contract is actually paying for factory time, transport, and site coordination. A higher average ticket is good; a higher ticket with hidden labor is not.
Model mix and finish level
Delivery distance and site access
Install scope and crew hours
Change orders and punch-list time
Use one pricing rule for upgrades and one for exceptions. If the model starts at $180k and climbs toward $16M, every step up in finish level or site complexity should trigger a price review before the contract is signed. That protects gross margin and gives the owner cleaner profit to draw from.
Sales Pipeline And Permitting Timing
Pipeline and Permit Timing
This driver is the gap between leads and homes that are financed, permitted, and build-ready. The model assumes delivered homes rise from 30 in Year 1 to 60 in Year 2 and 150 in Year 5, so backlog quality matters more than raw lead count. If permits slip, crews wait and factory overhead still runs.
Sales commissions stay at 25%, while digital marketing falls from 30% to 15% later, so better conversion should lift margin. Weak backlog creates idle labor, rushed starts, deposit gaps, and missed install windows, which hurts cash timing and the owner’s take-home pay.
Track Build-Ready Backlog Weekly
Measure leads, financed approvals, permits issued, and install-ready jobs separately. A lead is not revenue; only a funded, permitted, build-ready project can turn into delivered-home cash. Keep a weekly backlog view so factory starts match the install calendar and labor stays busy instead of waiting on paperwork.
Use a simple control sheet for starts, deposits, and install windows. Shift marketing toward sources that produce permitted jobs, not just inquiries, and watch the tradeoff between 25% commissions and digital marketing moving from 30% to 15%. Better sequencing protects utilization and collections.
Overhead, Debt, Reserves, And Cash Timing
Overhead, Debt, and Cash Timing
This driver is the cash cushion between job profit and owner pay. The fixed load is high: $435k per month in source fixed expenses, plus $260k annual payroll, with $25k monthly factory lease, $45k insurance, $38k utilities and security, and $5k R&D materials. If jobs are profitable but cash comes late, the owner still has to fund payroll, rent, and insurance.
Reserve planning turns accounting profit into pay you can actually draw. The key inputs are deposit size, progress billing, equipment financing, warranty reserves, and reinvestment timing. If deposits lag or final collections slip, a strong gross margin still won’t protect owner income, because the business must keep paying overhead before cash lands.
Track cash by job, not just profit
Build a 13-week cash forecast around each home’s deposit date, milestone billings, and final payment. Hold a separate warranty reserve and capex reserve before owner draws. If a job needs outside cash after the deposit, the billing schedule is too loose or the contract price is not covering the timing gap.
Track deposit timing and amount
Track progress billings by milestone
Track debt payments by due date
Track warranty reserve balances
Track owner draw approval timing
Pay overhead from operating cash, debt from scheduled inflows, and owner pay only after reserve targets are met. That matters here because the source cost stack is already heavy, and even one delayed site payment can force the owner to skip a draw. Cash timing, not just profit, decides take-home pay.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.