How Much Does an RC Boat Shop Owner Make? 5-Year Income View
Radio-Controlled Boat Shop Bundle
You’re sizing owner pay for a United States RC boat shop before the cash curve gets real This estimate covers $93,000 to $6821 million in annual revenue, gross margin, operating costs, inventory reserves, and owner take-home before personal taxes across the first five years Results depend on location, inventory mix, supplier terms, ecommerce reach, and how much work the owner personally handles
Owner income$0Net margin-172% to 74%Revenue for target pay$475kBusiness difficultyHard
Want the six drivers that move owner pay?
1
Sales Volume
$93K-$6.8M
More visitors turning into buyers moves revenue from Year 1's $93K to Year 5's $6.8M, and it sets the ceiling for every other profit lever.
2
Margin Mix
14%-12%
Shifting mix toward performance parts and keeping wholesale cost near 12%-14% protects gross profit on each order.
3
Overhead Load
$158K
The yearly fixed overhead plus the $75K manager role create the breakeven load, so slow sales burn cash fast until Month 19.
4
Channel Mix
1.8%-3.0%
Owning more traffic and tightening conversion lifts visitor-to-buyer rate from 1.8% in Year 1 to 3.0% in Year 5.
5
Turnover
5.5%-4.5%
Cutting shipping and fulfillment from 5.5% to 4.5% and keeping stock moving faster frees cash and protects margin.
6
Service Add-Ons
15%-25%
As repeat customers rise from 15% to 25% of new buyers, repair, tuning, and setup work gets more chances to add high-margin revenue.
Want to test your owner draw?
Owner income calculator
Estimate owner take-home and the target-pay gap from revenue, margin, costs, reserves, and target pay.
!
Planning note: Research-based planning estimate only. Actual owner income is not guaranteed and this is not tax advice or owner distribution advice.
How do you check owner income in the Radio-Controlled Boat Shop model?
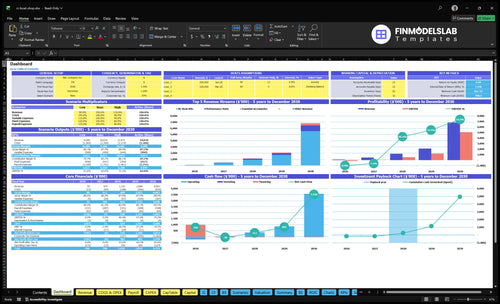
The dashboard tab in the Radio-Controlled Boat Shop Financial Model Template shows revenue, gross profit, EBITDA, cash need, breakeven, payback, and owner draw assumptions. Open it to review the full model.
Owner-income model highlights
Owner draw scenarios
Revenue and gross profit
Pricing, mix, and costs
How do RC boat shop margins affect owner income?
Yes—owner income rises when the Radio-Controlled Boat Shop shifts toward higher-margin repeat sales, not just more kits. The margin mix moves from 400% kits, 350% performance parts, and 250% accessories in Year 1 to 200% kits, 550% parts, and 250% accessories in Year 5, so the best money comes from parts, upgrades, batteries, chargers, and add-ons that lift basket value without tying up slow inventory. For a plain-English breakdown, see How Increase Profitability Radio-Controlled Boat Shop? and note prices move from $450 to $500 for kits, $85 to $95 for parts, and $45 to $52 for accessories.
Margin drivers
Supplier terms shape gross margin.
Discounting cuts owner income fast.
Sales channel changes take-home cash.
Kits need tight stock control.
Income levers
Repeat parts orders lift basket value.
Upgrades bring higher-margin dollars.
Batteries and chargers sell with boats.
Accessories help without slow inventory.
How much can an RC boat shop owner take home?
A Radio-Controlled Boat Shop owner may take home $0 in Year 1 because EBITDA is -$160,000; see How To Write Radio-Controlled Boat Shop Business Plan? before planning withdrawals. Year 2 take-home is still tight at $16,000 EBITDA, while Year 3 can support stronger draws at $528,000 EBITDA if the required $708,000 cash reserve by Month 24 is funded.
Owner Pay Reality
Year 1: likely $0 owner take-home
Year 2: limited by $16,000 EBITDA
Year 3: stronger at $528,000 EBITDA
Month 24: needs $708,000 cash
Cash Drains
Fund product costs and shipping first
Pay warehouse lease: $3,500/month
Cover ecommerce subscription: $299/month
Budget marketing, utilities, insurance, and payroll
How much revenue does an RC boat shop need to break even?
For a Radio-Controlled Boat Shop, breakeven is late: the source model hits it at Month 19, and Year 1 revenue of $93,000 still does not cover costs. Even at $475,000 in Year 2 revenue, EBITDA is only $16,000, so owner pay has to wait until fixed overhead, payroll, shipping, wholesale inventory, and reserves are covered. Here’s the quick math: Year 1 variable cost runs at 195% of sales, so cash gets tight fast even if gross margin looks fine.
Why breakeven runs late
Month 19 reaches breakeven
$93,000 Year 1 revenue falls short
195% variable cost crushes cash
Inventory buys delay owner draws
What drives the gap
$475,000 Year 2 revenue, only $16,000 EBITDA
Payroll absorbs early profit
Fixed overhead sits above owner pay
Shipping and reserves eat margin
Key Takeaways
Sales grow fastest when conversion and order size rise.
Margins depend on mix, not just more volume.
Breakeven arrives at Month 19, but cash lags.
Underpriced labor and shipping can erase gross profit.
Compare low, base, and high owner-income cases
Owner income scenarios
Revenue, payroll, and inventory reserve needs move owner pay fast here, so these scenarios show when take-home is likely zero, modest, or strong.
Compare owner take-home across low, base, and high operating cases.
Scenario
Low CaseCash tight
Base CaseReserve first
High CaseScale up
Launch model
Revenue stays near the first-year buildout, so owner take-home is likely zero.
Owner pay starts after the shop clears reserves and the middle years turn profitable.
The shop reaches a stronger earnings path once traffic, conversion, and repeat buying all rise together.
Typical setup
Year 1 revenue is $93,000 with -$160,000 EBITDA, while fixed costs, payroll, and inventory reserves absorb cash.
Year 2 to Year 3 revenue runs from $475,000 to $1,137,000, EBITDA ranges from $16,000 to $528,000, and draws stay secondary to working capital.
Year 4 to Year 5 revenue reaches $2,084,000 to $6,821,000, EBITDA rises to $1,195,000 to $5,065,000, and owner distributions can follow a larger cash buffer.
Cost drivers
Low conversion
fixed lease and payroll
marketing spend
shipping fees
inventory reserve
Visitor conversion
product mix
gross margin
staffing ramp
working capital reserve
Higher traffic
better conversion
mix shift to parts
higher staffing
larger inventory reserve
Owner income rangeBefore owner reserves
$0No draw
Modest draw after reservesLimited draw
Strong draw capacityUpside with reserves
Best fit
Use this to stress-test the first operating year and a slow traffic start.
Use this as the core planning case for a growing but still cash-managed shop.
Use this to test the upside case where volume and margin both hold up.
!
Planning note: Scenario ranges are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distributions.
Radio-Controlled Boat Shop Core Six Income Drivers
Sales Volume And Average Order Value
Sales Volume and Average Order Value
More orders help only when you can fill them. In this shop, sales volume and average order value depend on complete boats, parts, batteries, chargers, electronics, and accessories, so one out-of-stock part can kill a cart. The source model starts at $93,000 in Year 1 as conversion improves from 18% to 30% and units per order rise from 1 to 3.
Here’s the quick math: higher traffic and bigger baskets raise gross profit, but shipping work, payroll, and stockouts can eat the cash first. If orders grow faster than inventory turns, owner pay gets squeezed even when top-line sales look good. One clean rule: sell what you can ship fast.
Track Conversion, Basket Size, and Fill Rate
Measure conversion rate, units per order, and in-stock rate by SKU group. AOV goes up when carts include boats plus add-ons, but only if batteries, ESCs, props, and chargers are on hand. Watch which products lift basket size without creating dead stock.
Use a simple weekly check: traffic, orders, AOV, gross margin, and shipping labor hours. If conversion hits 30% but pick-pack time or backorders rise, profit can fall. Keep fast movers stocked first, then test bundles that add one accessory per order.
Track orders per SKU group
Watch average order value weekly
Protect in-stock fast movers
Bundle add-ons, not slow stock
Limit shipping and payroll creep
Repair And Tuning Service Revenue
Repair And Tuning Service Revenue
Repair and tuning revenue only helps if each job is priced for owner time, technician labor, parts use, and warranty risk. That covers electronics installs, hull repair, motor and ESC troubleshooting, custom setup, and race tuning. The real metric is contribution per bench hour: price minus labor, parts, and rework.
Inputs are job count, average ticket, parts used, warranty allowance, and bench capacity. If you underprice labor, service looks busy but acts like a hidden payroll cost. One clean rule: more jobs help income only when the bench stays profitable, not just full.
Price the bench, not just the part
Track hours per job, gross margin per repair, and repeat parts sales from each service ticket. Set a floor price that covers labor plus a warranty reserve, then compare it to actual time. If a repair takes longer than quoted, raise the rate or tighten the scope. Here’s the quick math: service price minus labor, parts, and redo risk.
Measure bench hours by job type.
Separate parts margin from labor.
Quote warranty work as a reserve.
Limit low-margin rush jobs.
Link service to add-on parts sales.
If scheduling gets tight, raise prices before hiring. Repair benches do not scale like ecommerce orders, so capacity is the ceiling on owner pay. What this hides: one bad pricing model can fill the calendar and still leave less cash for the owner.
Sales Channel Strategy
Sales Channel Mix
Online reach helps, but it does not guarantee better profit. In the source model, shipping and fulfillment run 55% of revenue in Year 1 and still 45% in Year 5, so every online order must carry enough margin to cover packing, postage, and service work. Local sales can cut shipping friction, but they need traffic, display stock, events, and staff. One clean test: channel choice should raise cash, not just orders.
Measure Margin by Channel
Track online orders, in-store sales, average order value, return rate, and shipping cost as a share of sales. Club events and race-day sales can lift conversion and repeat buys, but only if event labor and demo inventory stay in line. Watch for platform fees, damaged shipments, customer support load, and price matching, because those costs can erase the benefit of more reach.
Product Mix And Gross Margin
Product Mix And Gross Margin
Product mix changes profit because kits, performance parts, and accessories do not earn the same. In the source model, kit pricing moves from 400% in Year 1 to 200% in Year 5, while performance parts move from 350% to 550%; accessories stay at 250%. That mix shift can raise or cut owner draw even if sales stay flat.
Gross margin is the cash left after product cost, discounts, returns, and online fees. Track it by SKU family, not just total sales. A shop can make more from repeat add-on parts than from one large kit sale, especially when kits need heavier discounting or create higher shipping and fee drag.
Track Margin By Product Family
Measure sales mix, unit margin, returns, and fee rate for kits, parts, and accessories each week. The inputs that matter are order count, average order value, supplier cost, discount rate, return rate, and online fees. If parts and add-ons produce better margin, shift email, bundles, and repeat offers there.
Use a simple SKU report to spot which items fund payroll and owner pay. If a high-margin part keeps stocking out, you lose more profit than from missing one kit sale. If discounting pushes kit margin down, cut price cuts before they erode cash flow.
Fixed Overhead And Owner Labor
Fixed Overhead And Owner Labor
Fixed overhead and owner labor decide how much gross profit reaches the owner. Fixed overhead here means the warehouse lease, ecommerce subscription, marketing, utilities, insurance, and licensing, or $6,949/month before payroll. Then comes a $75,000 general manager, a $42,000 warehouse associate, and partial support.
Here’s the quick math: the shop is already carrying $83,388/year in fixed overhead alone, before variable labor grows with volume. Owner self-work can help early cash, but sustainable income means pricing the labor needed to replace the owner, especially with payroll discipline needed before Month 19 breakeven.
Track the break-even labor load
Keep overhead and payroll separate from product margin. Watch fixed costs, headcount, and owner hours each month, then compare them with gross profit so you know when the business can pay a market-rate replacement and still support owner pay.
Monthly fixed expenses
GM and warehouse wages
Support role time
Owner salary or draw target
Gross profit after fees
If overhead jumps before sales density does, cash gets tight fast. The clean test is whether gross profit can cover $6,949/month plus payroll and still leave room for draw; if not, delay hires or shorten owner pay until breakeven holds.
Inventory Turnover And Cash Tied Up
Inventory Turnover And Cash Tied Up
RC boat inventory can trap cash fast because hulls, motors, ESCs, props, and batteries sell in uneven bursts. If slow SKUs sit on shelves, the owner’s cash drops even when gross margin looks fine. The model still shows $708,000 minimum cash at Month 24, while breakeven arrives at Month 19, so growth inventory still needs funding after profit turns positive.
That matters for owner pay. Inventory reserves are not spendable profit, so every extra dollar tied up in dead stock cuts owner draw capacity until the item sells. The main risk is overbuying niche parts and missing fast movers, which hurts cash twice: money gets stuck on shelves and in-demand parts go out of stock.
Buy to Velocity, Not Hope
Track sell-through rate, days on hand, and reorder lead time by SKU. Here’s the quick math: cash tied up equals units on hand × landed cost. If a part is slow for 60 days, cut the next buy before it becomes shelf clutter. Fast parts should get first claim on cash.
Review top and slow SKUs weekly
Set min/max by sell-through
Protect fast parts first
Test niche buys with small orders
Watch stockout rate on high-demand parts, because lost sales are expensive. But don’t let carry levels outrun demand. Treat inventory reserves as working capital, not profit, and keep draws modest until replenishment needs and ramp costs stay covered.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.