What Is a Realistic Pay Range for Real Estate Brokerage Owners?
For an independent, single-office U.S. residential real estate brokerage with an owner who actively manages the firm and still closes business, a realistic planning range is roughly $16,000 to $184,000 a year of owner income after modeled tax and reinvestment reserves, with a base case near $93,000. This article models about $840,000 of annual gross commission and fee revenue, roughly 80 transaction sides, a 43% brokerage gross margin after agent payouts and other direct deal costs, and $18,200 of monthly payroll, overhead, marketing, and debt service. The estimate is not a guaranteed salary or passive return: it assumes the owner is the managing broker, personally contributes production, and leaves cash aside for taxes and reinvestment. July 2026 U.S. existing-home data showed a $431,400 median existing-home sale price, but local prices, transaction volume, negotiated compensation, agent splits, licensing rules, and closing cadence can move the result materially.
Owner income$93KNet margin11%Revenue for target pay$851KBusiness difficultyHard
Owner income calculator
Estimate owner cash from gross commission revenue, retained margin, operating costs, reserves, and a target monthly pay level.
i
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
1
Closed transaction sides
~80/year base
Commission revenue is episodic, so a handful of delayed or lost closings can move annual owner cash by tens of thousands of dollars.
2
Fee per represented side
~$10.4K base
At a $431,000 home value, even a 0.25-point change in negotiated side compensation changes gross commission by about $1,080 per closing.
3
Company dollar retained
43% blended margin
Agent splits, caps, team structures, referral fees, and owner-produced deals determine how much gross commission remains before payroll and overhead.
4
Owner production vs. management
~25% of sides
The base case needs the owner to keep selling while supervising the office; replacing that production or management labor usually raises payroll or lowers margin.
5
Staff and fixed overhead
$14K/month
Base payroll plus fixed overhead equals $14,000 a month before marketing and debt, so the brokerage must cover a meaningful floor even in a slow closing month.
6
Lead cost and repeat business
$3K/month base
Paid lead generation matters, but a larger repeat-and-referral share lowers acquisition pressure and makes closing volume less expensive to maintain.
Want to test the brokerage assumptions in a full forecast?
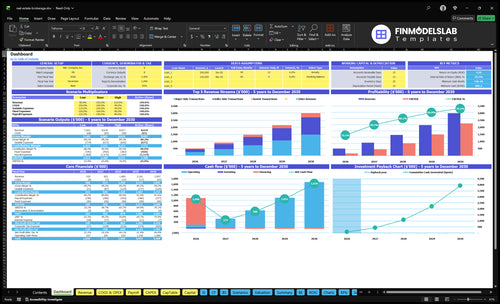
The Real Estate Brokerage Financial Projections Template in Excel includes a dashboard and editable revenue, cost, payroll, scenario, and financial-statement views. The dashboard preview is useful for checking whether transaction volume, commission revenue, agent payouts, staffing, cash flow, and scenario changes still reconcile once they are carried beyond a one-month owner-income estimate.
How does a residential brokerage turn home sales into owner income?
The cleanest revenue unit is a represented transaction side, not the full property sale. The July 2026 national median existing-home price was $431,400, according to NAR's latest existing-home sales data. This model uses about $431,000 as a price anchor and a 2.4% planning assumption for compensation on one represented side, or roughly $10,350 of gross commission income per side. That percentage is not a national standard: compensation must be negotiated, and NAR's post-settlement disclosure states that broker compensation is fully negotiable and not set by law.
At roughly 80 sides a year, the side math supports about $828,000 of gross commission; the model adds about $12,000 of referral, transaction, and other brokerage fee revenue to reach $840,000 annually. Agent payouts and direct deal costs come out first. The 43% base gross margin is a planning assumption for an owner-producing boutique, with a 38% to 47% range for different splits, caps, referrals, and owner production.
Base revenue bridge
About 80 represented sides a year.
About $10,400 to $10,600 gross commission per modeled side.
About $840,000 annual gross commission and fee revenue.
43% remains after agent payouts and direct deal costs.
What this estimate hides
A higher local home price can raise dollars per closing without raising transaction count.
Lower negotiated compensation can offset that benefit.
High agent splits can grow headcount while shrinking company dollar.
Closings arrive unevenly, so monthly revenue is never as smooth as this planning average.
How much revenue does the brokerage need to pay the owner $8,000 a month?
With the base cost structure, the calculator needs about $70,948 of monthly revenue, or $851,376 annualized, to support $8,000 of monthly owner cash after the 25% tax reserve and 10% reinvestment reserve. Base revenue of $70,000 a month falls short by only $265 of owner cash, which is why one or two extra closings can make a noticeable difference. The model's operating break-even before owner pay and reserves is lower: $18,200 of monthly operating costs divided by a 43% gross margin equals about $42,326 of monthly revenue, or about $508,000 annualized.
This is above the scale of a tiny one-person office. NAR's 2025 Profile of Real Estate Firms reported that one-office firms had a median 12 transaction sides and $4.6 million of brokerage sales volume in 2024. The NAR firm profile therefore makes clear that this nine-producer base case is a growth-oriented boutique, not a typical new office.
Target-pay math
Gross profit at $70,000 revenue: $30,100.
Payroll, overhead, marketing, debt: $18,200.
Profit before reserves: $11,900.
Owner cash after $4,165 of reserves: $7,735.
Break-even warning
Breaking even is not the same as paying the owner.
Revenue can cover overhead while owner cash remains thin.
Debt service consumes cash even when accounting profit is positive.
A tax reserve and working-capital buffer should be funded before discretionary distributions.
Key Takeaways
Base owner income is about $93,000 after modeled reserves, not $840,000 of brokerage revenue.
The brokerage needs about $851,000 of annualized revenue to support an $8,000 monthly owner-pay target under base costs.
Company dollar after agent payouts matters more than headline sales volume.
Safe distributions come after payroll, overhead, marketing, debt service, taxes, and reinvestment cash are protected.
Can the brokerage run without the owner closing deals?
Not at the same income level in this base case. The owner is doing two jobs: licensed supervision and roughly one-quarter of production. BLS notes that brokers often manage their own offices and supervise sales agents, and it also warns that commission earnings can be irregular, with professionals sometimes going weeks or months without a sale; see the BLS occupational profile. If the owner stops producing, the brokerage must either replace those sides with recruited agent production, accept a lower retained margin, or pay someone else to handle management while the owner sells.
The $7,500 monthly staffing line excludes owner pay and covers a coordinator or office administrator plus part-time bookkeeping and compliance help. In 2025, BLS listed median real-estate-industry wages of $43,970 for office clerks and $53,470 for bookkeeping clerks. The BLS real-estate wage table helps frame what it costs to replace work the owner cannot keep absorbing.
Owner-operated model
Owner supervises agents and compliance.
Owner still closes meaningful personal business.
Owner pay stays outside the labor-cost field in this calculator.
Residual owner cash therefore combines pay for work and return on ownership.
Manager-run alternative
Add a market-rate broker-manager or operations salary.
Replace owner-produced transactions with agent volume.
Track whether the business still earns a return after paying all labor at market rates.
How should owner salary and owner distributions be separated?
The $92,820 base owner-income output is an economic cash bucket after modeled reserves, not a tax classification. A sole proprietor, partnership owner, LLC member, or corporation can have different legal payment mechanics. If the brokerage elects S-corporation tax treatment and the shareholder-owner performs substantial services, the IRS says the company must pay reasonable compensation before non-wage distributions. That means an active owner should not call the whole $92,820 a tax-free or payroll-free distribution.
Salary pays for broker, sales, recruiting, and management work; distributions come from residual profit. This widget keeps owner salary outside labor cost so the same owner cash is not counted twice. In bookkeeping, classify the required salary or guaranteed-payment portion out of the owner-cash bucket. Keep tax cash separate too: IRS guidance on withholding and estimated tax explains the pay-as-you-go system. The 25% reserve here is liquidity planning, not a promised tax rate.
Salary or service compensation
Pays for the owner's actual labor.
Should reflect entity structure and tax rules.
Can be benchmarked against comparable broker and manager work.
Is different from a return on invested ownership capital.
Distribution or draw
Comes from residual cash, not top-line commission revenue.
Should flex down when closings, margins, or cash reserves weaken.
Must not drain money needed for taxes, payroll, debt, or compliance.
Is not guaranteed just because the income statement shows a profit.
What do low, base, and high owner-income cases look like?
The scenario range is intentionally wide because closings and company dollar move together. NAR's 2026 Member Profile reported a typical individual REALTOR® at nine transaction sides in 2025, while team-based brokerage specialists reported much higher volume; it also reported a $59,200 median gross income and $9,530 of median business expenses for members. Those figures describe practitioners rather than brokerage owners, but the 2026 NAR Member Profile release is useful context for why a brokerage's high case requires more than simply adding licensees. Productivity, retained split, support cost, and owner production all have to move coherently.
Owner income scenarios
The same low, base, and high presets used by the calculator, with costs rising as the brokerage scales.
Low, base, and high planning cases for an owner-operated residential real estate brokerage.
Planning factor
Low CaseSlow ramp
Base CaseOwner-operated
High CaseScaled support
Launch modelRevenue and margin
$42,000 monthly revenue
38% gross margin
$70,000 monthly revenue
43% gross margin
$110,000 monthly revenue
47% gross margin
Typical setupTeam and owner role
About 48 sides
Owner-heavy production
Lean support
About 80 sides
Owner plus eight agents
Coordinator support
About 120 sides
Stronger agent productivity
Expanded support
Cost driversMonthly operating load
$14,000 operating costs
Lower marketing and staffing
$18,200 operating costs
Balanced staffing and marketing
$26,200 operating costs
Higher staffing and lead spend
Owner income rangeAfter modeled tax and reinvestment reserves
$16,464annual after reserves
$92,820annual after reserves
$183,600annual after reserves
Best fitOperating condition
New or rebuilding office with inconsistent closings and heavy owner involvement.
Established boutique with steady local referrals, disciplined splits, and active owner production.
Productive local team with stronger lead flow, better conversion, and support capacity that rises with volume.
i
Planning note: Scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
What must be paid before owner cash is safe to distribute?
Commission deposits are not the same as spendable owner cash. In the base month, $70,000 of revenue first becomes $30,100 of gross profit after agent payouts and direct deal costs. Then the brokerage pays $7,500 of employee payroll, $6,500 of fixed overhead, $3,000 of marketing, and $1,200 of debt service. Only $11,900 remains before reserves. After $2,975 is reserved for taxes and $1,190 for reinvestment, the model leaves $7,735 for owner compensation and distribution.
Debt deserves its own line because principal payments consume cash even when they do not reduce accounting profit the same way an expense does. SBA guidance notes that 7(a) interest rates are negotiated but subject to program maximums and that many non-real-estate 7(a) uses have terms of ten years or less; see the SBA lender terms. This model does not assume a specific SBA loan. It simply holds $1,200 a month aside for principal and interest so financing is not hidden inside overhead.
Commission timing can make a profitable quarter feel cash-poor. Keep one to two months of core payroll and overhead outside the distribution account, with more cushion when a few large closings dominate the pipeline or recruiting costs arrive before agent production.
Pay in this order
Agent splits and direct closing costs.
Employee payroll and fixed office obligations.
Marketing commitments and debt service.
Tax reserve, reinvestment reserve, then owner cash.
Cash-flow pressure points
Closings slip across month-end.
Agents are recruited before their pipeline converts.
Listing marketing is spent before a commission is earned.
Legal, E&O, technology, or compliance costs hit before distributions are reduced.
Which six drivers move Real Estate Brokerage owner income most?
The six drivers below are the same levers used in the compact cards, expanded into operating decisions. They matter because the brokerage earns only after a transaction closes, the agreed compensation is collected, the agent and referral economics are settled, and the remaining company dollar covers the office. A founder should track all six monthly, but transaction sides and company dollar deserve weekly attention because they can change the annual owner-income forecast fastest.
1. Closed transaction sides
Manage sides as a production pipeline, not an annual wish
The base case needs about 80 represented sides a year, roughly 6 to 7 monthly. NAR's 2026 Member Profile reported a typical individual REALTOR® at nine sides in 2025, so nine producers can theoretically reach 81 sides only if productivity is broadly consistent. NAR's member data show why a new recruit should not be budgeted like a mature producer.
One modeled side produces about $10,350 of GCI and roughly $4,450 of gross profit at a 43% retained margin. Five lost or delayed sides can remove more than $22,000 of annual gross profit. Track signed clients, under-contract sides, expected close dates, fallout, and closed sides by producer.
Track pipeline coverage every week
Do not manage the business from closed transactions alone. Use a forward pipeline that shows whether next month's commission is already under contract.
Closed sides per producer.
Under-contract sides and expected close date.
Fall-through and delayed-closing rate.
90-day pipeline divided by target sides.
2. Fee per represented side
Price the service in dollars per side, not by habit
Compensation is negotiable, so the 2.4% side fee used here is only a planning rate. NAR's required compensation disclosure explicitly says broker compensation is fully negotiable and not set by law. At a $431,400 home value, a 2.4% fee equals about $10,354. At 2.15%, it is about $9,275; at 2.65%, about $11,432. That half-point spread changes GCI by about $2,157 per side.
Across 80 sides, a 0.25 percentage-point change is about $86,000 of GCI before splits and direct costs. The decision is whether service scope, local competition, conversion, and agent economics support the agreed fee. Track fee dollars per side separately for listings, buyers, referrals, and flat-fee work.
Track realized fee, not advertised fee
The only useful number is the compensation actually collected at closing after concessions and referral obligations.
Average GCI dollars per closed side.
Fee rate by listing and buyer side.
Referral fee leakage.
Conversion rate by fee and service package.
3. Company dollar retained after agent payouts
Recruit for retained gross profit, not headcount
NAR reported that 86% of REALTORS® were independent contractors at their firms in 2026. That is why this model treats agent payouts as direct revenue share inside gross margin and reserves the labor field for employees.
At a 43% margin, $70,000 of monthly revenue leaves $30,100 before payroll and overhead. If the retained margin falls to 38% with no revenue gain, gross profit drops by $3,500 a month. Track company dollar per agent and per side after caps, referrals, transaction charges, and owner-produced deals.
Measure company dollar by producer
A high-split agent can still be attractive if volume is strong, while a low-split agent can be unprofitable if support demands are high and closings are rare.
Retained GCI by agent.
Retained gross profit per side.
Support cost per productive agent.
Gross margin after caps and referrals.
4. Owner production versus management labor
Price the owner's time before calling the brokerage profitable
The owner is not passive. BLS says every state requires brokers and agents to be licensed and notes that brokers often operate offices and oversee agents. The BLS broker profile lists a 2024 median employee-broker wage of $72,280, a useful proxy for labor that should not be treated as free.
The owner produces around 20 of 80 sides. If those sides disappear, revenue could fall roughly $207,000. If management is hired out instead, payroll can rise by $70,000 or more annually before benefits. Either way, owner income must reflect the labor being replaced.
Separate owner hours by role
Track sales, supervision, recruiting, compliance, and administration separately so you know which role must be replaced first as the brokerage grows.
Owner-produced sides and GCI.
Owner hours in management vs. selling.
Cost to replace owner-covered roles.
Owner cash after market-rate labor adjustment.
5. Staff and fixed overhead
Keep support cost tied to transaction throughput
The base case carries $7,500 of employee labor and $6,500 of fixed overhead monthly. BLS 2025 real-estate data list median wages of $43,970 for office clerks and $53,470 for bookkeeping clerks, supporting a lean coordinator plus fractional accounting or compliance structure. See the 2025 real-estate wage table.
Payroll plus fixed overhead consumes $168,000 a year before marketing and debt. Adding $4,000 of monthly support before production arrives can reduce annual owner cash by nearly $48,000 before reserve effects. Hire against files, listings, pending contracts, and compliance workload rather than agent headcount alone.
Track support cost per closed side
As volume grows, support dollars should rise more slowly than retained gross profit. If both move one-for-one, scale is not creating owner leverage.
Employee labor per closed side.
Fixed overhead as a percent of GCI.
Files per transaction coordinator.
Technology spend per productive licensee.
6. Lead cost, repeat business, and referral mix
Use paid acquisition to fill gaps, not replace the database
Marketing is $3,000 a month in the base case and $5,000 in the high case. NAR's 2025 firm research says past clients and referrals are major sources of sales; see the firm profitability and referral summary. Database quality is therefore a margin lever, not just a marketing tactic.
If $36,000 of annual marketing creates 12 incremental sides, acquisition spend is $3,000 per side against roughly $4,500 of retained gross profit. At only six sides, acquisition cost doubles to $6,000 and can exceed contribution. Track every source through signed client, closing, GCI, and company dollar.
Track acquisition through company dollar
Lead cost is only meaningful when it is connected to closed revenue and the amount the brokerage actually retains.
Cost per signed client and closed side.
Repeat-and-referral share of closed sides.
Company dollar by lead source.
12-month client database reactivation rate.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Real Estate Brokerage Bundle
Choosing a selection results in a full page refresh.