How Much Does a Seamstress Business Owner Make? $21k-$271k EBITDA
Seamstress and Alterations Service Bundle
You’re planning owner pay around visits, tickets, labor, rent, and reserves, not just sewing skill In this five-year model, seamstress business revenue rises from $281k in Year 1 to $805k in Year 5, with EBITDA from $21k to $271k before taxes, financing, and owner reserve choices
Owner income$21k / $132k / $271kNet margin7.5% to 33.7%Revenue for target pay$23.4k/mo to $67.1k/moBusiness difficultyHard
Want the six main income drivers?
1
Service Mix
$84/ticket
Year 1 mix of 70% standard alterations at $45, 20% repairs at $35, and 10% custom work at $450 drives the biggest swing in take-home.
2
Job Volume
3.6K-6.6K
With 12 to 22 visits a day and 300 operating days, each extra slot fills fixed capacity and lifts revenue fast.
3
Owner Capacity
1.0 FTE
Keeping the owner billable on fittings and alterations adds output without adding more payroll.
4
Price Lift
22%
Core prices rise from $45/$35/$450 to $55/$42/$550, and rush fees move from $15 to $20, so the same work brings in more cash.
5
Labor Leverage
181K-324K
Payroll grows from about $181K in Year 1 to $324K by Year 4, so utilization has to stay high or margin gets squeezed.
6
Overhead Control
$4.4K/mo
Fixed shop costs are about $4,440 a month, so breakeven lands in Month 6 and extra overhead cuts straight into take-home.
Want to test your own owner pay?
Owner income calculator
Estimate owner take-home and the target-pay gap from revenue, margin, costs, reserves, and target owner pay.
!
Planning note: This is a researched planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
Want to see the owner income model behind the numbers?
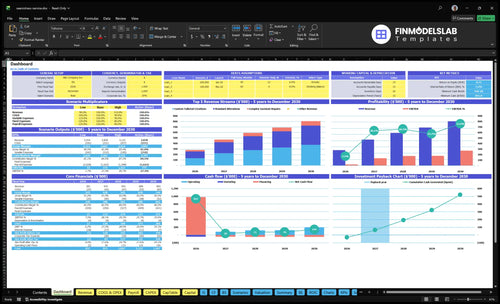
Open the Seamstress and Alterations Service Financial Model Template to check the dashboard, pricing, volume, mix, costs, cash flow, and owner income. It maps $281k-$805k revenue, $21k-$271k EBITDA, $852k cash need, Month 6 breakeven, and 19-month payback, so you're testing assumptions, not a forecast.
Owner-income model highlights
Owner take-home output
Revenue and EBITDA range
Scenario testing matters
How much revenue does an alterations business need to pay the owner?
Owner pay in a Seamstress and Alterations Service should come from gross margin after direct costs, payroll, rent, marketing, and reserves, not from revenue alone. In this model, $281k of Year 1 revenue leaves only $21k EBITDA after $181k payroll and $533k in annual fixed overhead, while $470k in Year 2 supports $132k EBITDA as visits reach 15 per day.
Revenue reality
$281k revenue, $21k EBITDA
$181k payroll already used
$533k fixed overhead is heavy
Pay owner from leftover contribution
Planning rule
$470k revenue, $132k EBITDA
15 visits/day supports better pay
Each $10k owner profit needs margin
Convert sales goals into weekly orders
Can a seamstress business make a full-time income?
Yes, a Seamstress and Alterations Service can make a full-time income, but only when daily volume, pricing, and labor are tight; see How To Launch Seamstress And Alterations Service Business? for the operating setup. Here’s the quick math: the model moves from $21k EBITDA in Year 1 to $132k in Year 2 and $271k in Year 5 as visits rise from 12 to 22 per day across 300 operating days.
Income Drivers
Grow visits from 12/day to 22/day
Operate 300 days per year
Protect prices on custom work
Use repairs to fill capacity
Owner Pay Risks
Replacing the $68k tailor role creates salary room
Taxes reduce cash kept
Reserves come before owner draws
Custom jobs must carry premiums
What profit margin can an alterations business earn?
For a Seamstress and Alterations Service, profit margin can be strong because fixed overhead is only $4,440 per month before payroll; here’s the quick math in plain English, and you can see the cost base in What Are Operating Costs For Seamstress And Alterations Service?. In this model, EBITDA margin improves from about 75% in Year 1 to 337% in Year 5, while direct cost load drops from 18% of revenue to 14%.
Margin leaks
Rework cuts finished-job profit
Complex garments can be underquoted
Rush jobs need rush fees
Machine downtime raises job cost
Watch this daily
Track cost per finished job
Watch payment fees by order
Low-ticket work can crowd out custom orders
Protect margin with clear rush pricing
Key Takeaways
Custom creations drive revenue more than low-ticket repairs.
Volume only works when capacity stays on time.
Billable sewing hours, not busy hours, set output.
Overhead and wages set the break-even floor.
Compare low, base, and high owner income scenarios
Owner income scenarios
Higher visits, pricing, and staffing swing income fast in this alterations shop. The three cases show how volume and payroll shape pre-tax owner returns.
Low, base, and high cases for pre-tax owner income.
Scenario
Low CaseDownside case
Base CaseBase case
High CaseUpside case
Launch model
This is the lower earnings path with Year 1 activity and tight capacity.
This is the modeled middle path with steadier volume and staffing.
This is the stronger earnings path with fuller capacity and higher ticket value.
Typical setup
It models 12 visits per day, $281k revenue, about $21k EBITDA, $181k payroll, and $4,440 in monthly fixed overhead.
It models 18 visits per day, $593k revenue, $174k EBITDA, and about $267k payroll in Year 3.
It models 22 visits per day, $805k revenue, $271k EBITDA, and about $324k payroll in Year 5.
Cost drivers
12 visits/day
payroll load
fixed overhead
service mix
rush fees
18 visits/day
pricing mix
payroll scale
overhead base
referral flow
22 visits/day
fuller capacity
higher prices
payroll scale
rush fees
Owner income rangeBefore owner reserves
$21k EBITDALow earnings
$174k EBITDAModeled earnings
$271k EBITDATop-end earnings
Best fit
Use this to test a slow start, tighter labor use, or softer demand.
Use this as the planning case for normal trading conditions.
Use this to test what happens if demand stays strong and the shop stays busy.
!
Planning note: These scenario ranges are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distributions.
Seamstress and Alterations Service Core Six Income Drivers
Service Mix and Average Ticket
Service Mix and Average Ticket
This driver is the mix of standard alterations at $45, complex repairs at $35, and custom creations at $450. The owner’s income swings most when the mix shifts toward higher-ticket work: a 10% custom creation share moves revenue far more than a full book of low-ticket hems and repairs.
Using the disclosed assumptions, the Year 1 weighted ticket is $8,350 before rush work, and it rises to $10,190 in Year 5 as prices increase. The risk is simple: if the calendar fills with low-value jobs, higher-value fittings get blocked, cash flow softens, and owner pay gets squeezed even when the studio looks busy.
Price Complexity First
Track the share of each job type, the average ticket by service, and the booked hours they consume. Here’s the quick math: more custom work, clear quotes, and complexity pricing lift revenue quality without adding the same labor load as small repairs.
Protect margin by charging for fit risk, extra fittings, and rush turnaround. Keep minimum charges tight, document quote rules, and watch whether low-ticket jobs are crowding out higher-margin appointments. If they are, owner profit drops even before rent, payroll, and other fixed costs move.
Overhead Control and Operating Model
Overhead Sets the Break-Even Floor
Fixed costs hit income before the first garment is sewn. This model carries $3,200 studio lease, $450 utilities and internet, $220 insurance, $150 maintenance, $120 software, and $300 cleaning, or $4,440 per month. That amount comes straight out of gross profit, so it sets the floor for owner pay.
Here’s the quick math: at a $45 standard alteration price, overhead alone needs about 99 jobs a month to clear. That is only the floor, not full break-even, because labor, fabric, and rework still need coverage. If order density stays light, take-home income gets squeezed fast.
Tie Rent to Required Daily Visits
Measure lease cost against booked visits, not just square footage. A storefront can help with walk-ins and referrals, but a low-visibility setup can cut traffic, so cheaper rent is not always cheaper in practice. The lease only works when daily visits and average ticket can cover the fixed base.
Track daily booked visits
Watch average ticket by job type
Check fixed cost per month
Compare rent to walk-in traffic
Use the lease test before signing: if bookings do not cover $4,440 plus labor, keep the setup lean or move to a lower-cost space. A small rent cut helps, but a quiet location can reduce repeat visits and referrals, which hurts owner draw more than the savings help.
Pricing Power, Rush Fees, and Turnaround
Pricing, Rush Fees, and Turnaround
Pricing protects income when jobs vary by fabric, fit risk, and deadline. In Year 1, the model prices standard alterations at $45, complex repairs at $35, custom creations at $450, and rush fees at $15. By Year 5, those rise to $55, $42, $550, and $20. The key inputs are garment type, number of fittings, and turnaround time. If quotes ignore complexity, owner pay gets squeezed fast.
Here’s the quick math: a $10 price lift on a $45 alteration is a 22.2% increase in revenue per job. That matters because low-ticket work can fill the schedule but still miss profit if fittings run long or rush requests go uncharged. The risk is simple: too many fittings, not enough fee discipline, and cash inflow lags the labor.
Use minimums, rush premiums, and quote rules
Track job type, fittings per order, rush count, and average ticket by service line. Set a minimum charge for small fixes, then add a clear rush fee when turnaround is compressed. Keep quote rules consistent so a complex repair does not get priced like a simple hem. That protects gross margin and keeps paid work aligned with labor time.
Build a quote sheet with the Year 1 and Year 5 price points, then test how often customers accept each price. If a job needs extra fittings, charge for the added time or tighten scope before work starts. One clean rule: no free extras on low-ticket jobs. That keeps revenue per hour high enough to cover wages, rent, and owner pay.
Weekly Job Volume and Appointment Flow
Weekly Appointment Flow
Revenue stays steady when booked visits match the shop’s real capacity. With 12 visits per day in Year 1 and 22 visits per day in Year 5, over 300 operating days that equals 3,600 to 6,600 annual visits. If fittings, pickups, and sewing run late, volume turns into rework, churn, and slower cash coming in.
What this estimate hides: not every visit becomes paid work at the same margin. A full calendar helps only if repeat customers, referrals, and reviews keep demand local and even. One clean rule: fill the book, but don’t outrun your turnaround time.
Track Booked Visits, Not Just Foot Traffic
Measure booked visits per day, on-time completion rate, repeat share, and referral share. Also watch no-shows, late pickups, and rework. Those inputs tell you if volume is producing profit or just more labor. Dry cleaner and bridal referral channels can smooth demand, but overbooking raises touch time and cuts owner pay.
Track visits by service type.
Set capacity by due date.
Limit rush work during peaks.
Fix late pickup bottlenecks fast.
Here’s the quick math: if the shop books more visits but misses deadlines, the extra revenue can get eaten by rework and customer loss. The better target is steady, completed work at the same pace your team can stitch, fit, and hand back without quality slips.
Owner Capacity and Billable Sewing Hours
Billable Sewing Hours
Busy time is not the same as paid time. Fittings, measurements, customer messages, pickups, ordering notions, machine maintenance, and admin all cut sewing output, so owner pay depends on completed paid jobs per production hour, not just visits. With 12 to 22 daily visits, quality control can become the bottleneck before demand does.
The Year 1 labor base is $68k for a Lead Master Tailor, $52k for a Senior Seamstress, and $42k for a Junior Tailor. If non-billable work keeps crowding the bench, take-home income gets capped because more customers do not automatically create more sewn jobs.
Track Billable Output Per Hour
Measure billable sewing hours, not door traffic. Track paid jobs per production hour, non-billable tasks, and rework by garment type. Here’s the quick math: if visits rise but output per hour falls, payroll and quality control squeeze margin first.
Log paid jobs by hour
Separate sewing from admin
Track rework by garment type
Block time for pickups
Use these counts to set daily capacity, staff schedules, and owner draw targets. If the calendar is full but sewing hours are not, the shop is busy, but not more profitable.
Labor Leverage and Staffing Decisions
Hiring That Pays
If payroll rises from $181k in Year 1 to $324k in Year 5, hiring only helps when the extra labor creates more finished, billable work than it costs. In a tailoring shop, owner replacement labor covers work the owner used to do, while growth labor adds new capacity. If the new work is just more fittings or rework, owner pay gets squeezed.
The key test is contribution per employee after wages, training, scheduling, and rework. Track turnaround time, rework rate, and customer wait time before you add headcount. One good hire can lift cash flow; one bad hire can raise payroll without raising profit.
Hire on Finished Jobs
Measure each role by completed paid jobs per production hour, not by hours on the clock. A part-time assistant in Year 2 should free sewing time only if pickup, prep, and customer messages really move off the tailor's plate. Here’s the quick test: if output stays flat, the new payroll is just overhead.
Track finished jobs per week.
Watch rework before hiring again.
Compare wait time to payback.
If wait time rises or quality slips, fix the process first. That keeps labor tied to owner income, not just a busier schedule.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.