Section 508 Compliance Owner Income: $145K Pay Plus Profit
Section 508 Accessibility Compliance Bundle
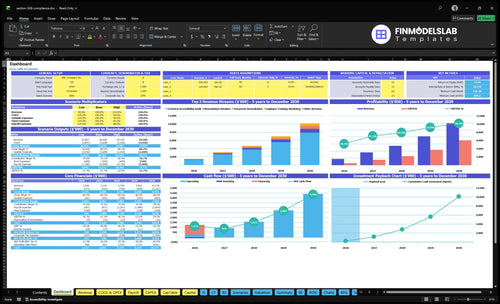
A Section 508 compliance business owner can plan around a $145K principal consultant salary plus possible profit distributions, if the firm earns enough after labor, tools, marketing, and overhead In the first-year base case, revenue is about $806K, variable costs are 27%, and operating profit before owner tax is about $38K If the owner keeps a 20% reserve from that profit, reserve-adjusted owner income is about $175K before taxes These are researched planning assumptions, not guaranteed salary, tax advice, or automatic distributions
Owner income≈$175KNet margin30%Revenue for target pay≈$806KBusiness difficultyHard
Want the six Section 508 income drivers?
1
Utilization
125-185h
More billable hours per active client lift revenue fast without needing more sales.
2
Retainers
30%-75%
A bigger retainer mix gives steadier monthly income and smoother cash flow.
3
Pricing
$150-$310
Higher service rates on audits, training, and remediation raise margin on every hour.
4
Labor Mix
18%-12%
Keeping COGS down by using fewer subcontractors leaves more gross profit.
5
Pipeline
$1.8K-$1.35K
Lower CAC means each new client costs less, so marketing spend works harder.
6
Overhead
$9K/mo
Holding fixed overhead near $9K a month protects EBITDA when growth slows.
Want to test your Section 508 owner income?
Owner income calculator
Estimate owner take-home and the target-pay gap from revenue, margin, costs, reserves, and target pay.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
How does the Section 508 income model connect owner pay to planning?
Can a solo Section 508 consultant earn meaningful owner income?
Yes, Section 508 Accessibility Compliance can pay meaningful owner income: the first-year model already includes $145K principal pay, but solo capacity caps income before demand does; see How Increase Profits In [Your Business Name]? for the profit levers. Here’s the quick math: 25 customers × 125 billable hours equals 3,125 hours/month if all are active, so the owner must price well, protect billable time, and add help carefully.
Owner income math
$145K planned principal pay
25 acquired customers modeled
125 hours per active customer monthly
3,125 monthly hours if all active
What caps income
Proposals cut billable delivery time
QA reviews reduce paid capacity
Client calls crowd audit work
Subcontractors add capacity at 10% revenue cost
How does scaling a Section 508 consulting business change owner income?
Scaling Section 508 Accessibility Compliance can raise owner income, but only if utilization and quality stay high. Here’s the quick math: Year 2 adds 2 senior auditors, 15 remediation specialists, 1 business development manager, and 1 document accessibility coordinator, with planning based on 36 acquired customers, 14 monthly billable hours, and a $221 blended hourly rate. That points to about $111K a month in revenue, about $1.34M a year, and about $162K operating profit before owner tax, but payroll, proposal cycles, QA, and management time all rise too.
Income lift
36 customers drive scale
14 hours keeps billing dense
$221 holds pricing power
$162K supports owner pay
Pressure points
Payroll rises with added staff
Proposal cycles slow cash
QA load grows with volume
Management time cuts owner focus
How much revenue is needed for Section 508 consultant owner pay?
For Section 508 Accessibility Compliance, don’t start with revenue; start with the owner pay you want. In the base first-year model, $806K of revenue supports about $145K in principal pay and roughly $38K in operating profit before owner tax.
Salary coverage first
73% contribution after costs
27% variable costs stay variable
Revenue must cover pay first
Top-line sales do not equal take-home
Profit reserve second
Subtract $397K payroll
Include $108K fixed overhead
Include $45K marketing
Build 20% profit reserve
Key Takeaways
Billable hours drive revenue, but quality must hold.
Retainers improve cash flow and owner pay stability.
Tight scope protects margin from unpaid rework.
Staffing, pipeline, and reserves shape distributable profit.
Compare lean, base, and scaled Section 508 owner-income cases
Owner income scenarios
Owner income moves with payroll, QA, and how much work shifts from audits into retainers. These cases show the spread from a tight launch to a scaled model.
Compare low, base, and high owner income cases.
Scenario
Low CaseLow Case
Base CaseBase Case
High CaseHigh Case
Launch model
This is the lower earnings path, where the owner keeps salary in place and cash stays guarded.
This is the modeled path, where owner income rises with steadier delivery and a fuller pipeline.
This is the stronger earnings path, where scale and repeat work lift owner income sharply.
Typical setup
A first-year style mix with about 82% gross margin after COGS, a heavy audit share, and light support staffing.
A Year 2 style mix with about 83.5% gross margin after COGS, more retainer work, and higher payroll and QA load.
A Year 3 style mix with about 85% gross margin after COGS, more recurring remediation, and rising management complexity.
Cost drivers
Principal salary
subcontracted SMEs
testing software
sales commissions
fixed overhead
Senior auditor payroll
remediation staff
sales commissions
fixed overhead
reserve holdback
Multi-FTE payroll
retainer mix
QA oversight
pipeline depth
management time
Owner income rangeBefore owner reserves
$170K - $180KLow Case income
$260K - $290KBase Case income
$700K - $750KHigh Case income
Best fit
Use this to stress-test a slower ramp and tighter reserve needs.
Use this as the core plan for a growing service mix and steadier close rates.
Use this to test upside from stronger volume and a deeper recurring book.
!
Planning note: Scenario ranges are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distributions.
Section 508 Accessibility Compliance Core Six Income Drivers
Billable Utilization
Billable Utilization
Billable utilization is the share of expert time you can turn into paid work. In this model, it starts at 125 billable hours per month per active customer and can grow to 185. The rest of the week gets eaten by proposals, discovery, QA, client management, training, and sales calls, so revenue rises only if quality and close rate hold. One clean rule: more billed hours should not mean more rework.
For owner pay, this driver is strong until overload hits. If delivery crowds out sales and review work, you can push up near-term take-home and still hurt future revenue. Track active customers, billable hours, and non-billable hours each month, then watch whether higher utilization is lifting cash or just stretching the owner thinner.
Raise Utilization Without Breaking Delivery
Use a weekly utilization report. Separate paid hours from unpaid work, then cap the time spent on proposals, discovery, QA, and client management before they crowd out delivery. Here’s the quick math: if billable hours rise from 125 toward 185 per active customer, revenue should rise too, but only if the team still protects sales and review time.
Test for overload early. If close rate slips, QA errors rise, or the owner stops selling, the extra hours are not helping income. Keep one clear threshold for paid work, one for non-billable work, and one for owner review, so utilization improves cash flow without breaking margin or future bookings.
Delivery Labor Mix
Labor Mix and Owner Pay
Owner take-home rises when delivery shifts from founder labor to paid staff and subcontractors, but the tradeoff is fixed payroll versus flexible margin. In Year 1, the staffing plan includes $145K principal pay, $115K senior auditor pay, $95K remediation specialist pay, and $425K for half-time business development, plus subject matter experts at 10% of revenue.
That mix adds capacity fast, but it also creates payroll risk if booked work slows. By Year 5, subcontracted expert cost falls to 6% of revenue, so gross margin improves only if employee hours stay filled and QA keeps rework low. If labor grows ahead of billable work, owner pay gets squeezed before profit can flow through.
Keep Labor Flexible
Track labor by role, not just total headcount. Watch payroll as a share of revenue, subcontractor cost as a share of revenue, billable utilization, and QA rework hours. The key question is simple: does each added payroll dollar create more billed work than it adds fixed cost?
Track billable hours by role.
Cap subcontractor spend by revenue.
Document QA before handoff.
Use employees for steady demand.
Use subcontractors for peaks and specialty work.
Use employees to build capacity and subcontractors to stay flexible. Put clear review steps in writing so outside work does not leak margin. If demand is lumpy, keep the fixed payroll tight and push overflow to subject matter experts until volume is stable.
Sales Pipeline Quality
Pipeline Quality
Pipeline quality is what turns outreach into paid Section 508 work. With $45K in year-one marketing and $1,800 CAC, the model buys about 25 customers ($45,000 / $1,800), so weak fit or slow closes can leave the team busy but underbooked.
The best-fit buyers are public-sector teams, contractors, education, and enterprise groups with real accessibility deadlines. Better fit raises utilization and protects pricing; long procurement, unpaid proposal work, and slow close cycles push cash out and delay owner pay.
Tighten Lead Fit and Close Speed
Track lead source, proposal-to-close rate, sales cycle days, and CAC by segment. If a segment needs heavy pre-sales work and still closes slowly, it is hurting margin even when pipeline volume looks fine.
Prioritize deadline-driven buyers.
Cap unpaid proposal hours.
Drop low-fit procurement cycles.
By Year 5, $140K in marketing at $1,350 CAC implies about 104 customers if the math holds. That only helps income if those customers turn into billable hours fast enough to keep utilization high without discounting.
Project Pricing And Scope
Pricing and Scope Discipline
Pricing and scope drive margin more than volume here. Year 1 hourly rates are $225 for technical audits, $195 for remediation retainers, $250 for employee training, and $150 for document remediation; by Year 5 they rise to $270, $240, $310, and $190. That is a 20% to 26.7% lift, so weak pricing leaves real money on the table.
This driver includes fixed-fee audits, Accessibility Conformance Report (ACR) support, retainers, and training. Price for risk, documentation depth, technical complexity, and deadlines. The key inputs are hours, service mix, and rework. If scope is loose, unpaid revisions and extra testing cut cash fast, and owner pay drops even when revenue looks busy.
Scope first, then set the fee
Track estimated hours versus actual hours by service line. If audit work needs extra code review, more document cleanup, or another client round, bill a change order fast. That protects gross margin and keeps support time from turning into free labor.
Use a scope sheet that names deliverables, review rounds, deadline dates, and client response timing. Fixed-fee work should have a clear cap on revisions. Otherwise, the firm can sell more revenue and still earn less profit and less cash for the owner.
Recurring Compliance Retainers
Recurring Compliance Retainers
If your work is mostly one-off audits, cash comes in waves and owner pay swings with it. A retainer mix moving from 30% in Year 1 to 75% in Year 5 shifts more revenue into recurring work, so forecasting gets cleaner and you spend less time chasing the next project.
Average retainer load also rises from 10 hours to 15 hours, so margin depends on scope. The retainer should cover monitoring, retesting, advisory calls, training refreshers, and remediation guidance. The main risk is vague service levels or “unlimited support”, which turns steady revenue into unpaid labor.
Tighten Retainer Scope
Track retainer share, hours per client, and response limits. Here’s the quick math: more recurring work means less feast-or-famine owner pay, but only if the hours stay within plan. If a client starts asking for open-ended help, the retainer stops behaving like predictable revenue.
Set included tasks in writing.
Cap advisory calls and revisions.
Log retainer hours monthly.
Reprice when scope expands.
Use the same scope on every renewal so you can forecast cash and staff time. What this estimate hides: if monitoring and retesting intensity rises faster than price, the owner still feels the squeeze even with more recurring revenue.
Overhead, Reserves, And Reinvestment
Overhead and Reserves
$9K in monthly fixed overhead—shared office, insurance, legal and regulatory monitoring, cloud infrastructure, CRM, bookkeeping, and memberships—has to be covered before owner pay feels real. Add $45K of first-year marketing, and the business needs enough operating profit to absorb it before distributions. A 20% reserve on $38K operating profit leaves about $30K distributable, so profit on paper is not the same as cash for the owner.
Reserve Before Draws
Track fixed overhead, marketing spend, operating profit, and the reserve rate each month. If cash after overhead and marketing can’t fund a 20% reserve, pause owner draws. That protects delivery quality and continuity, because short-term draws can pull cash away from client work, follow-up, and compliance support when the team is already stretched.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.