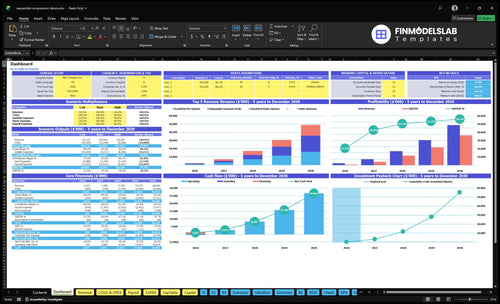
Sequential Compression Device Sales Owner Income: $632K Year 1 EBITDA
Sequential Compression Device Sales Bundle
You’re separating revenue from spendable owner pay in a medical equipment sales business This estimate uses a five-year model with $2323M Year 1 revenue, $632K Year 1 EBITDA, payroll, overhead, working capital, and reinvestment reserves before personal taxes
Owner income$185K+Net margin27%-75%Revenue for target pay$680KBusiness difficultyHard
Want to test your owner pay?
Owner income calculator
Estimate owner take-home and the target-pay gap from revenue, margin, costs, reserves, and target pay.
!
Planning note: Research-based planning estimate only. Actual owner income depends on revenue, margin, payroll, reserves, timing, and financing. It is not guaranteed salary, tax advice, or owner distribution advice.
What drives owner take-home?
1
Sales Volume
$2.3M-$48.8M
Year 1 revenue is $2.323M and Year 5 reaches $48.830M, so more units sold is the biggest path to owner take-home.
2
Price Mix
$45-$2,600
Prices range from $45 for packs to $2,600 for premium systems, so a better mix raises revenue per sale.
3
Margin Terms
89%-91%
Gross margin before variable costs starts at 89% and improves to 91%, so supplier terms lift profit fast.
4
Repeat Revenue
$0.5M-$19.8M
Disposable packs rise from 12,000 units in Year 1 to 380,000 in Year 5, adding repeat cash after each device sale.
5
Overhead Load
$29K/mo
$29K a month in fixed overhead has to be covered first, so lean staffing and lease control protect founder pay.
6
Cash Reserve
$805K
$805K minimum cash in Month 2 means working capital matters as much as profit, because cash gaps can block owner draws.
Want to see how Sequential Compression Device Sales turns into owner income?
This Sequential Compression Device Sales Financial Model Template ties dashboard, revenue build, unit economics, inventory, payroll, operating expenses, cash flow, capex, and scenarios to owner take-home. It also shows charts from $2,323M to $48,830M revenue and $632K to $36,459M EBITDA; open the model.
Owner-income model highlights
Owner take-home first
Units, prices, COGS
Fixed costs, payroll
Scenario and assumption control
Which customers make a sequential compression device sales business more profitable?
Sequential Compression Device Sales is usually most profitable when the mix leans toward customers that pay fast, buy again, and need less service. Hospitals, surgery centers, and clinics can place larger orders, but they often mean slower collections and more contract pressure; home health providers can lift unit count and replacement garment volume, while direct-pay buyers can shorten cash timing but may need more marketing spend. The right model comes from tracking average selling price, payment days, bad debt, repeat sales, and support cost against a market serving hundreds of thousands of Americans after surgery or during immobility.
Institutional buyers
Hospitals can drive bigger orders.
Surgery centers often buy in volume.
Clinics can add steady demand.
Payment days are usually slower.
Direct-pay and home care
Home health can raise replacement volume.
Direct-pay can improve cash timing.
Bad debt risk can stay lower.
Marketing spend can rise fast.
What costs reduce sequential compression device sales owner income?
In Sequential Compression Device Sales, owner income gets squeezed by the link What Are Operating Costs For Sequential Compression Device Sales? because device purchase cost, components, packaging, sterilization, freight, storage, demo units, warranty replacements, commissions, insurance, fees, software, payroll, and bad debt all hit cash. With 110% Year 1 COGS, 60% sales commissions and logistics, 30% marketing, and $29K/month fixed expenses, there’s very little left for owner pay or reinvestment.
Direct cash drains
Device purchase cost cuts margin fast.
Freight and storage add cash burn.
Warranty swaps reduce collected cash.
Bad debt delays or erases cash.
Fixed pressure
Payroll is $760K in Year 1.
Payroll rises to $2,675M in Year 5.
Insurance and regulatory fees keep stacking.
Each cost cuts owner salary and distributions.
Can a sequential compression device sales business scale owner income?
Sequential Compression Device Sales can scale owner income, but it is not a clean solo-model forever. The path shown grows from 2 sales reps in Year 1 to 15 sales reps in Year 5, so coverage expands fast, but payroll, commissions, support, engineering, compliance, and inventory cash all rise too. Year 1 shows $2323M revenue and $632K EBITDA, while Year 5 shows $48830M revenue and $36459M EBITDA.
Owner income can grow
Founder-led sales can protect margin early.
2 reps keeps the team tight in Year 1.
15 reps widens territory coverage in Year 5.
Revenue scales with more device sales.
Cash pressure rises
Payroll and commissions grow with reps.
Inventory cash rises with more devices and garment packs.
Receivables tie up more working capital.
Warranty exposure adds another cash drag.
Key Takeaways
Qualified accounts drive income more than raw leads.
Repeat garment packs smooth revenue and cash flow.
Supplier terms decide how much margin survives.
Cash reserves must fund inventory and receivables.
Compare lean, base, and growth owner-income scenarios
Owner income scenarios
Owner income rises fast as device volume and recurring garment pack sales scale faster than fixed payroll. Higher revenue helps, but stretched receivables or faster payroll growth can still cut take-home.
Lean, base, and growth cases show how volume and margin change owner income.
Scenario
LeanLean case
BaseBase case
GrowthGrowth case
Launch model
Lower owner income comes from Year 1 volume with a still-heavy fixed cost base.
Modeled owner income tracks Year 2 volume, with much better spread over fixed costs.
Stronger owner income comes from Year 5 scale, where recurring packs and device volume do the heavy lifting.
Typical setup
Year 1 uses $2.323M revenue, 450 professional systems, 800 home systems, 12,000 garment packs, 27.2% EBITDA margin, and $760K payroll.
Year 2 uses $7.090M revenue, 1,200 professional systems, 2,500 home systems, 45,000 garment packs, 56.9% EBITDA margin, and $1.095M payroll.
Year 5 uses $48.830M revenue, 4,500 professional systems, 9,000 home systems, 380,000 garment packs, 74.7% EBITDA margin, and $2.675M payroll.
Cost drivers
450 pro systems
800 home systems
12,000 garment packs
27.2% EBITDA margin
$760K payroll
1,200 pro systems
2,500 home systems
45,000 garment packs
56.9% EBITDA margin
$1.095M payroll
4,500 pro systems
9,000 home systems
380,000 garment packs
74.7% EBITDA margin
$2.675M payroll
Owner income rangeBefore owner reserves
$632KLean income
$4.0MBase income
$36.5MGrowth income
Best fit
Use this if you want the first-year stress case with tight cash and early-stage scale.
Use this for the core operating case and normal funding discussions.
Use this to test upside, but watch working capital and payroll discipline.
!
Planning note: These scenario ranges are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distributions.
Sequential Compression Device Sales Core Six Income Drivers
Qualified account sales volume
Qualified Account Volume
Qualified account sales volume is the count of accounts that buy enough systems and disposable garment packs to cover fixed overhead and carrying costs. At 1,250 systems and 12,000 packs in Year 1, owner income is still tight; by Year 5, 20,200 systems and 380,000 packs can support stronger take-home pay if repeat orders hold.
The key is repeat business, not raw leads. Repeat accounts cut sales friction and refill packs, while a pipeline full of trials that never becomes purchase orders burns time and leaves cash tied up before profit reaches the owner.
Measure Repeat Conversion
Track trial-to-order rate, repeat order rate, and packs per active account. Here’s the quick math: more qualified accounts means more units sold, more recurring pack revenue, and more margin to cover overhead before any owner draw. If trials do not convert, revenue quality stays weak even when pipeline activity looks busy.
Track trial-to-order conversion.
Flag accounts that reorder packs.
Watch time from trial to PO.
Separate one-time from repeat buyers.
Sales commissions, payroll, and overhead
Commissions, Payroll, Overhead
This driver is the cost of selling and running the business: sales commissions, wages, benefits, support staff, and fixed overhead. In Year 1, payroll is $760K, including a $185K CEO salary, 2 sales reps, and support teams. Fixed overhead is $29K/month, or $348K/year. If commissions and logistics run 60% to 65% of revenue, only 35% to 40% is left before owner pay and other costs.
Year 5 payroll rises to $2.675M with 15 sales reps and more support. That can grow revenue, but it also raises the break-even bar fast. The owner’s take-home income improves only when added staff create more margin than they cost. More headcount without tighter conversion, pricing, or service efficiency can turn growth into thin cash flow.
Track Cost Before You Hire
Track cost per booked account, commission rate, payroll per rep, and monthly overhead against revenue. Here’s the quick math: at a 60% to 65% selling-and-logistics load, every $100 of revenue leaves $35 to $40 before payroll and overhead. That means the real test is not sales volume alone; it’s margin after staffing and fulfillment.
Keep the assumptions editable in the model. Test commission tiers, rep productivity, and support coverage by channel, because the right mix should raise repeat orders without bloating fixed cost. If staffing grows faster than revenue per rep, owner draws get squeezed even when top-line sales look healthy.
Inventory, receivables, and reserves
Inventory, receivables, and reserves
This driver is the cash tied up after a sale: inventory on the shelf, receivables waiting to be paid, and reserves for warranty, returns, and compliance. The business can show profit and still miss owner pay if cash is needed to fund stock and claims. Minimum cash is $805K in Month 2, so distributions should wait until those needs are covered.
The setup also needs $375K of startup capex across molds, lab equipment, racking, software, furniture, and hardware. That spend does not raise profit by itself, but it raises the cash hurdle before take-home starts. The key inputs are unit volume, payment timing, denial and return rates, and replacement demand. When sales rise faster than collections, owner income gets trapped in working capital.
Protect owner cash before distributions
Build a weekly cash bridge that starts with units sold and ends with cash on hand. Track inventory turns, aged receivables, denied claims, return rate, and warranty replacements. One clean rule: do not take distributions unless cash stays above $805K and the next replenishment order plus expected claim costs are funded.
Age receivables every week.
Reserve for warranty claims.
Track returns by product type.
Match stock buys to demand.
If receivables slow or claims spike, slow owner pay first, not purchasing discipline. The owner’s take-home improves when cash turns fast enough to support growth without borrowing. That is the real test of this driver: not just selling more units, but converting those sales into usable cash.
Gross margin and supplier terms
Gross Margin
Gross margin is the cash left after product costs, before overhead and owner pay. In Year 1, COGS is 110% of revenue, made up of 85% manufacturing and components plus 25% packaging and sterilization, so gross margin is -10%. That means each $1 sold loses $0.10 before payroll, rent, or the owner draw.
By Year 5, COGS improves to 90%, so gross margin rises to 10%. The inputs that drive this are unit price, product mix, supplier pricing, freight, minimum orders, and warranty allowances. Do not treat gross margin as net income; it still has to cover overhead, sales pay, and cash tied up in inventory.
Control Supplier Terms
Track landed cost per unit, not just invoice price. Landed cost means the full cost to get a sellable device ready, including freight, packaging, sterilization, and warranty reserves. Here’s the quick math: if supplier terms push COGS from 110% to 90%, the business swings by 20 points of revenue before overhead.
Negotiate volume discounts, freight caps, and lower minimum orders early. Also test how warranty claims change true margin, because supplier credits can protect cash flow only if they are documented and collected. If pricing stays flat but COGS stays above 100%, owner pay has to wait for mix, volume, or terms to improve.
Repeat accessories and service revenue
Repeat Accessories and Service Revenue
This driver is the repeat sale of garment packs, replacement parts, renewals, and service after the first device sale. Here’s the quick math: 12,000 × $45 = $540K in Year 1, and 380,000 × $52 = $19.76M in Year 5. That kind of follow-on revenue can lift owner pay because it comes in after the initial sale and helps cover payroll and fixed overhead.
The catch is real: recurring revenue only counts if customers actually use and reorder. Replacement cuffs, sleeves, tubing, rental renewals, service, and maintenance can smooth cash flow, but only when usage, replacement cycles, and support capacity are documented. If those inputs are weak, the forecast can overstate profit and the owner may pay themselves too early.
Track Reorders, Not Hope
Build the forecast from confirmed usage by account. Measure pack reorders, service attach rate, and replacement cycle timing so you can see which customers truly create repeat cash. One clean rule: revenue from follow-on sales should be tied to shipped units and known reorder behavior, not just installed base size.
Track packs sold by customer.
Track renewals by month.
Track service tickets versus staff.
Track tubing and cuff replacements.
Track cash collected, not billed.
If the team cannot support the service load, the repeat stream weakens fast. Keep the forecast tied to capacity, because the owner’s income depends on repeat revenue that arrives on time and gets collected.
Average selling price and product mix
Average selling price and mix
Owner income moves when average selling price and product mix change. In Year 1, prices are $2,450 for pro systems, $850 for home systems, and $45 for garment packs; by Year 5 they rise to $2,600, $925, and $52. A heavier mix of devices, cuffs, sleeves, tubing, accessories, rentals, and service lifts gross dollars per order.
Here’s the quick math: a quote built mostly on low-price garment packs brings less cash than one that pairs a system with follow-on items. The risk is chasing hardware sales without recurring add-ons, which can leave revenue looking busy but owner pay thin. One clean rule: higher mix quality beats raw unit count when fixed overhead and payroll are in play.
Track mix by order value
Measure order mix, not just total orders. Track how many orders include a system, plus cuffs, sleeves, tubing, accessories, rentals, and service. Watch the split between $2,450 pro systems, $850 home systems, and $45 garment packs, then test whether bundled offers raise average order value and repeat revenue.
Build the forecast from units × price × mix. If the mix drifts toward low-margin hardware, cash for owner pay gets weaker even when sales volume holds. Also track attach rate for replenishment items, because that tells you whether the first sale is creating follow-on income or just one-time revenue.
Track average dollars per order.
Separate hardware and recurring items.
Test bundles by customer type.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.