How Much Can A Shelf Talker Design Service Owner Make By Year 5?
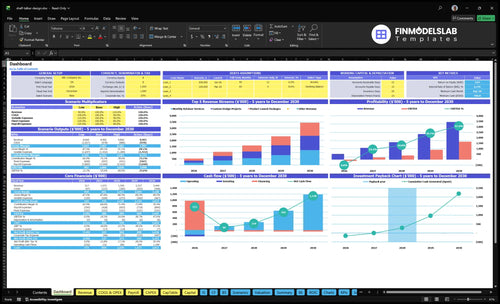
A shelf talker design business owner can make a planned $115k salary in this model, but first-year business profit is still negative at -$126k EBITDA on $517k revenue By Year 2, the model reaches $1072M revenue and $206k EBITDA, which creates room for owner distributions before taxes and reserves By Year 5, revenue reaches $3444M and EBITDA reaches $1641M, helped by higher retainer mix, stronger pricing, and lower direct cost percentages Revenue, profit, reserves, and owner take-home are different numbers
Owner income$9.6kNet margin-24% to 48%Revenue for target pay$1.07MBusiness difficultyHard
Want the six income levers?
1
Retainer Mix
20%-42%
As retainers grow from 20% to 42% of mix, cash gets steadier and owner pay is less tied to one-off jobs.
2
Price Power
$110-$170/hr
Higher hourly rates lift revenue on the same hours, so more of each project turns into owner income.
3
Client Load
18.5-25.5h
Each active customer grows from 18.5 to 25.5 billable hours a month, so account density drives more revenue.
4
Margin Control
73.5%-80.5%
Gross margin, the cash left after direct costs, rises from 73.5% to 80.5%, which leaves more profit for the owner.
5
Overhead Discipline
$8.45K/mo
Keeping fixed overhead near $8.45K a month protects cash and makes breakeven easier to hold.
6
Sales Capacity
$55K
The $55K Year 1 marketing budget only pays off if customer acquisition cost (CAC) stays near $1.8K and turns into qualified work fast.
Want to test your owner pay?
Owner income calculator
Estimate owner take-home and target-pay gap from revenue, margin, costs, reserves, and target pay.
!
Planning note: Research-based planning estimate only. Actual owner income depends on revenue, margins, payroll, taxes, reserves, and timing. It is not guaranteed salary, tax advice, or owner distribution advice.
Yes—Shelf Talker Design Service can scale from owner-led work to a small studio, but take-home only improves if systems grow faster than payroll. Year 1 payroll is about $303k from a $115k Creative Director, $82k Senior Designer, $34k half-time Copywriter, and $72k Account Manager, so recurring accounts and a steady sales pipeline matter right away. By year 5, the team grows to 3 designers, 15 copywriters, 2 account managers, and 1 operations manager, which cuts owner bottlenecks but raises break-even.
Year 1 cost load
$303k total payroll
$115k Creative Director
$82k Senior Designer
$72k Account Manager
What drives scale
Recurring accounts keep revenue steadier
Quality control protects margins
Sales pipeline fills the calendar
More staff lowers owner bottlenecks
How should a shelf talker design service price projects?
Shelf Talker Design Service should price projects by hours, revisions, and retail-ready deliverables. Here’s the quick math: a Year 1 custom design project at 12 hours x $145 = $1,740, a product launch package at 28 hours x $125 = $3,500, and a monthly retainer at 45 hours x $110 = $4,950. By Year 5, those rise to $2,380, $4,800, and $6,750, so retainers help planning, but only if scope and approval rules stay tight.
Price by hours
Quote custom work at 12 hours x $145.
Use launch packages at 28 hours x $125.
Use retainers at 45 hours x $110.
Price extra revisions as added hours.
Protect margin
Year 5 pricing reaches $2,380.
Year 5 launch packages reach $4,800.
Year 5 retainers reach $6,750.
Set tight scope and approval rules.
What affects profit margin in a shelf talker design service?
For a Shelf Talker Design Service, profit margin gets squeezed by revisions, outsourced design time, proofing, analytics access, referral fees, and software royalties, and you can see the startup side here: How Much To Start Shelf Talker Design Service Business? Uncontrolled file prep and print coordination can erase pricing gains, so gross revenue is not owner income. By Year 1, direct and variable costs total 265% of revenue, leaving 735% before fixed overhead and payroll; by Year 5, those costs fall to 195%, lifting gross margin to 805%.
Margin drags
Revisions raise labor fast.
Outsourced design time adds cost.
Proofing and file prep eat margin.
Print coordination can wipe gains.
Margin improves
Year 1 costs hit 265%.
Year 5 costs drop to 195%.
Gross margin rises to 805%.
Keep referral fees and royalties low.
Key Takeaways
More active clients raise monthly design demand.
Retainers smooth cash flow and improve staffing.
Pricing must cover compliance, revisions, and rush work.
Tight overhead and owner sales discipline decide profit.
Compare lean, base, and high owner-income scenarios
Owner income scenarios
Revenue mix, staffing, and repeat work shift owner income fast here, so the low, base, and high cases help set cash and hiring plans.
Modeled owner-income cases for launch, stabilization, and mature growth.
Scenario
Low CaseCash risk
Base CaseStaffing load
High CaseRepeat revenue
Launch model
This is the early ramp case, with Year 1 revenue at $517k and EBITDA at -$126k.
This is the stabilized case, with Year 2 revenue at $1.072M and EBITDA at $206k.
This is the mature upside case, with Year 5 revenue at $3.444M and EBITDA at $1.641M.
Typical setup
Most work is custom design, repeat retainers are light, and overhead stays high while the team carries full payroll.
Product launch packages and retainers carry more of the mix, so the team can cover fixed costs and some owner pay.
Retainers reach 42% of mix, repeat work dominates, and the heavier team supports higher throughput and owner upside.
Cost drivers
Custom project mix
low retainer mix
studio rent
sales commissions
full staff load
Balanced mix
higher retainer share
fixed payroll
commission fees
steady utilization
Repeat revenue
higher retainer mix
larger design team
lower supply load
sales efficiency
Owner income rangeBefore owner reserves
No reliable owner drawCash tight
Moderate owner paySteady cash path
Strong owner upsideUpside with risk
Best fit
Use this to stress-test launch cash needs and a slow sales ramp.
Use this as the main planning case for hiring, pricing, and cash timing.
Use this to test the ceiling if repeat accounts and retainers scale faster than hiring.
!
Planning note: These scenario ranges are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distributions.
Shelf Talker Design Service Core Six Income Drivers
Active Retail Client Count
Active Retail Client Count
Active retail client count is the clearest demand driver because each active retailer, brand, or broker creates monthly billable work. In Year 1, the model assumes 185 billable hours per active customer per month, so one low-fit account can eat revision time and account management instead of paid design hours.
Here’s the quick math: when a client leaves early, the $18k CAC has fewer months to pay back; by Year 5, CAC falls to $13k, so retention spreads that cost over more revenue and helps protect owner pay.
Keep the right clients longer
Track active clients, monthly billable hours per client, revision rounds, and retention months. The best-fit accounts create repeat work without heavy hand-holding, while weak-fit clients raise labor and delay cash collection.
Watch billable hours per client.
Cap revision loops early.
Reprice high-touch accounts fast.
Keep retention above churn.
Use those inputs to forecast how much of each month’s revenue reaches gross profit and then owner draw. If account management starts crowding out new sales work, client count stops growing income and starts building drag.
Retainer Revenue Mix
Retainer Revenue Mix
This driver is the share of shelf-talker work billed as monthly retainers instead of one-off projects. Here’s the quick math: a retainer at 45 hours × $110 is about $4,950/month in Year 1; by Year 5 it is 50 hours × $135, or $6,750/month. Retainer mix rises from 20% to 42%, so more revenue lands on a steadier schedule.
That steadier mix helps cash flow and makes staffing easier, because monthly support is simpler to plan than rush promo work. The tradeoff is fit: not every retail client will sign a retainer, so the owner should expect the mix to come from repeat launches, seasonal promotions, and recurring merchandising updates.
Grow the Monthly Share
Track three inputs: retainer hours, hourly rate, and retainer share of revenue. If the mix stalls below the 20% to 42% path, owner pay stays choppy and more time gets spent chasing one-off jobs. Price monthly support around clear deliverables, revision limits, and response times so the fee matches the staffing load.
Use retainers only where demand repeats. Build a simple rule: one launch, one seasonal reset, or one ongoing merch update can justify monthly support, but custom work outside scope should be billed separately. That keeps gross margin cleaner and protects the owner from unpaid extra hours that quietly eat take-home income.
Operating Expense Discipline
Operating Expense Discipline
Operating expense discipline decides how much gross profit reaches the owner. In this model, fixed overhead is $845k per month for rent, utilities, software, insurance, tools, and admin/legal fees, while marketing rises from $55k in Year 1 to $140k in Year 5. With Year 1 EBITDA at -$126k, the business is still funding growth before owner pay.
The key inputs are fixed overhead, marketing spend, and capex such as $185k workstations and a $62k proofing printer. If those costs run ahead of gross profit, cash stays tight and owner draws get delayed. One clean rule: do not add spend unless it either saves billable time or protects margin.
Cut Cost Drag
Track overhead as a share of gross profit each month, not just as a budget line. Separate true fixed costs from spend that scales with projects, then challenge every renewal, license, and admin fee. If a cost does not protect output, speed, or quality, it should be cut or renegotiated.
Use capex only when it lowers revision time or prevents rework. The $185k workstation set and $62k printer should be judged by fewer bottlenecks, faster proofs, and less contractor waste. If marketing climbs toward $140k by Year 5, tie it to booked work and keep the owner draw based on cash, not hope.
Revision And Contractor Efficiency
Revision And Contractor Efficiency
Revision rounds and contractor hours hit gross margin first. In Year 1, disclosed direct and variable costs total 265% of revenue, including 85% prototyping, 45% analytics, 100% referral fees, and 35% software royalties. That means each $1 of sales can carry $2.65 of cost, so unplanned fixes can wipe out cash for owner pay.
Protect Margin with Hard Limits
Track revision count, contractor rate, rush hours, and approval delays on every job. Use scope rules, proof templates, approval cutoffs, and file-prep checklists so rework stays inside the quote. By Year 5, total direct and variable cost drops to 195%, but only if rush work is priced, not absorbed.
Cap revision rounds per project.
Bill contractor overruns weekly.
Charge extra for rush files.
Average Package Price
Average Package Price
The owner’s income goes up when shelf talker work is priced for commercial value, not just design time. In Year 1, custom projects imply $1,740, launch packages$3,500, and retainers$4,950 per month; by Year 5, those rise to $2,380, $4,800, and $6,750. That pricing gap matters because more dollars per job can cover revision time, faster turnaround, and retail compliance work without squeezing owner pay.
Here’s the quick math: if the same client work is sold at a higher package price, revenue rises without needing more accounts. But if the package is underpriced, extra copy changes, approval rounds, and rush files eat margin and tie up the owner. The key inputs are project mix, price per package, and revision limits.
Price for the work, not the art
Track average price by offer: custom, launch, and retainer. Raise the fee when the job includes fast turnaround, copy direction, or retail compliance, since those raise delivery cost and owner time. A higher average package price should improve gross margin and free time for selling, not just add more design hours.
Use scope rules to protect the price. Set revision caps, define who approves copy, and quote rush work separately. If a $1,740 project keeps turning into a $2,380 job’s workload, the business is paying for the difference through lost capacity and lower take-home income.
Owner Sales Capacity
Owner Sales Capacity
Owner sales capacity is the pace at which the owner can sell, brief clients, and keep retail deadlines moving. In this service, that matters because the owner is the bottleneck: if sales slow, revenue stalls and pay gets pushed back. With CAC dropping from $18k to $13k as the sales engine improves, each new client takes less cash to win, and breakeven in Month 9 depends on early pipeline speed.
What this estimate hides is time. The owner still has to handle pitch work, client briefing, and quality control, so income is not passive. If the owner stays buried in production, close rates and turnaround slip, and that hurts cash flow and take-home pay even when demand is there.
Improve Sales Capacity
Track qualified leads, close rate, time from first call to signed work, and how much owner time goes to sales versus production. The inputs that matter are active clients, project mix, and the speed of each brief-to-launch handoff. Faster sales cycles spread fixed effort over more billable work, which protects gross profit and makes owner draws more stable.
Move the owner toward pipeline, pricing, and quality control, then delegate account follow-up where possible. That frees the owner from rework and lets them protect deadlines, which is key when a late brief can delay cash and push breakeven out. Early sales speed is the main lever here.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Shelf Talker Design Service Bundle
Choosing a selection results in a full page refresh.