What Is the Earning Potential for Supermarket Owners?
Supermarket Bundle
A hands-on owner of a mid-sized, single-store independent supermarket can see about $90,000 to $577,000 a year across a stressed-to-strong range, with this article's base case at about $301,000 a year. The base assumes roughly $15.24 million in annual sales, a 28% gross margin, owner-operated general management, payroll before owner pay, store overhead, marketing, and $10,000 a month of debt service. The $301,000 is cash after modeled tax and reinvestment reserves; it is not revenue, EBITDA, a guaranteed salary, or a passive distribution, and excludes personal spending and debt outside the modeled payment.
Owner income$301KNet margin2%Revenue for target pay$14.8MBusiness difficultyHard
How much can a supermarket owner make from one store?
For a single independent store, owner income is usually a low-percentage outcome on a large sales base, not a high-markup story. FMI reports that food retailers averaged a 2.1% net profit in 2025, while the FMS/NGA independent-grocer study for fiscal 2024 reported a 27.4% gross margin, 25.8% total expenses, and 1.9% net profit. That is why this base case puts owner cash near $301,000 on $15.24 million of annual revenue rather than assuming a double-digit take-home margin.
The model is a privately owned, single-location community supermarket selling packaged grocery, produce, meat, dairy, frozen food, bakery or deli, and household essentials. Fiscal-2024 independent-store evidence shows 8,609 weekly transactions and a $34 in-store basket, implying roughly $293,000 of weekly sales or $15.2 million annually, close to the base. FMI reports 2025 average weekly supermarket sales of $668,377 across the broader sector, so do not transplant a national chain-format average into a smaller independent-store forecast.
Owner income calculator
Estimate owner take-home from supermarket sales, margin, payroll, overhead, financing, reserves, and a monthly pay target.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
What drives supermarket owner income most?
Supermarket income is decided by small percentage movements across a very large sales base. The latest independent-grocer reporting shows the pressure clearly: fiscal-2025 gross margin reached 27.9%, shrink rose to 3.9% of sales, inventory turns fell to 16.1, and out-of-stocks were 6.6%. Those percentages are not side metrics; they determine whether gross profit survives long enough to pay labor, utilities, occupancy, debt, reserves, and the owner.
1
Gross margin and shrink
27.9% / 3.9%
Merchandise margin creates the pool that pays everything else; shrink can erase a meaningful part of that pool before the owner sees cash.
2
Transactions and basket
8,609 / $34
Independent-store transaction count multiplied by basket value sets the sales engine; a small basket lift compounds across thousands of weekly trips.
3
Labor efficiency
16.3% of sales
Labor and benefits are the biggest controllable expense; scheduling and whether the owner covers management directly change distributions.
4
Inventory turns
16.1x
Slower turns trap cash in stock and raise markdown and spoilage risk; better in-stock discipline protects both revenue and working capital.
5
Refrigeration and overhead
Up to 40%
Refrigeration can consume up to 40% of grocery-store energy, making maintenance and utility control material to owner cash.
6
Fresh and digital mix
3x online basket
Fresh departments differentiate stronger operators, while independent online baskets run roughly three times the typical in-store basket.
Want to test the store economics in a full forecast?
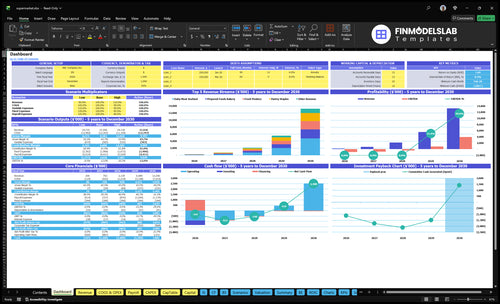
The Supermarket Five-Year Financial Model Template includes a business-specific dashboard for revenue, margins, cash flow, scenarios, and operating KPIs. The dashboard is useful for testing how basket size, traffic, category mix, COGS, payroll, inventory, capex, and financing interact before you decide what owner cash is truly distributable.
What sales level supports a $20,000 monthly owner target?
In the base model, the store needs about $1.24 million of monthly revenue, or $14.84 million annualized, to support a $20,000 monthly owner target after reserves while covering the modeled cost base. That scale is plausible for an established independent supermarket: the 2025 FMS/NGA study reported 8,609 weekly transactions per store, with a $34 in-store basket and $105 online basket in fiscal 2024.
Revenue math
$1.27M base monthly sales
$15.24M annual base sales
$14.84M annualized target-pay threshold
At $34 per trip, volume matters as much as price
What this estimate hides
Promotions can lift trips while reducing margin
Fresh mix changes basket and spoilage together
Seasonal peaks need inventory before cash arrives
Out-of-stocks can cap sales even with strong traffic
Do not confuse a $15 million store with a $15 million owner. Food retail works on high throughput and thin retained margin. In the base case, $1.27 million of monthly sales creates $355,600 of gross profit at a rounded 28% planning margin. Payroll, fixed overhead, marketing, and debt service use $310,000, leaving $45,600 before reserves. After the 25% tax and 20% reinvestment reserves, $25,080 remains for the owner.
How much margin does a supermarket need before owner cash appears?
The practical answer is that gross margin must clear the store's full operating burden by several percentage points, because a one-point miss can be expensive. Fiscal-2025 independent-grocer data put gross margin at 27.9%, while shrink reached 3.9% and turns fell to 16.1; the same reporting says profit leaders separated themselves through lower shrink, stronger inventory management, disciplined expenses, and fresh departments. See the 2026 independent-grocer findings.
One margin point
1% of $15.24M sales equals $152,400 a year
A 28% model margin creates about $4.27M annual gross profit
A 1-point margin loss exceeds half the base owner income
Shrink, markdowns, mix, and buying terms all matter
Gross profit is not owner pay
Payroll comes after merchandise margin
Occupancy and utilities still need cash
Debt service is a cash claim even when EBITDA looks healthy
Tax and reinvestment reserves reduce distributable cash further
Keep the labels separate. Revenue is the checkout total; gross profit is revenue less direct merchandise cost and shrink. Operating profit or EBITDA reflects operating costs under its stated definition, while accounting net profit may include depreciation, interest, and taxes. Owner salary pays for labor performed; a draw or distribution transfers residual equity or cash. Safe distributable cash exists only after payroll, vendors, overhead, debt, taxes, inventory, repairs, and required reserves are funded.
Can a supermarket run without the owner?
Yes, but a manager-run store should usually show lower owner distributions unless added scale covers the replacement management layer. The base calculator is explicitly owner-operated. The fiscal-2024 independent-grocer report put labor and benefits at 16.3% of net sales, and U.S. retail wage data show 2025 mean annual pay of $52,830 for first-line retail supervisors. The BLS retail wage data are useful for building a local management ladder.
Owner-operated base
$200,000 monthly staff payroll in the model
Owner covers general management
Owner income therefore includes pay for labor and residual return
It is not passive investment income
Manager-run test
Add a fully loaded store-manager budget
Keep department supervision and hourly coverage intact
Do not call owner labor free profit
Require added sales or margin before claiming passive distributions
The base labor line starts from the industry labor burden, then reclassifies a planning owner-manager amount because the owner performs that work; this avoids double counting. If the owner becomes absentee, add replacement management to labor cost before judging distributions. Entity structure matters too: for an S corporation, income and employment-tax treatment are distinct issues, so use current IRS S corporation guidance and professional tax advice rather than treating every distribution as salary.
What cash must stay in the store before distributions?
A supermarket should retain enough cash for inventory replenishment, payroll timing, refrigeration failures, seasonal buys, vendor terms, insurance, taxes, and debt service before the owner takes a draw. The fiscal-2025 independent-grocer results put inventory turns at 16.1 and capital expenditures just over 2% of sales, while refrigeration can consume up to 40% of a grocery property's energy according to ENERGY STAR grocery-store guidance. Those facts make cash reserves operational, not cosmetic.
Cash claims before a draw
Vendor invoices and fresh replenishment
Payroll and payroll taxes
Utilities, rent, insurance, repairs, and security
Loan principal and interest
Reserve discipline
Base tax reserve: 25% of positive profit
Base reinvestment reserve: 20%
Base monthly reserve: $20,520
Distribute only after the next operating cycle is funded
Debt deserves its own line because loan payments are cash outflows even if accounting profit looks acceptable. SBA notes that most 7(a) term loans are repaid through monthly principal-and-interest payments from business cash flow; the program can support up to $5 million depending on the product and eligibility. Review current SBA 7(a) loan terms and lender underwriting rather than assuming financing is cheap or automatically available. In this base case, $10,000 of monthly debt service reduces annual pre-reserve cash by $120,000.
Food-safety and licensing obligations also create real operating cost. The FDA maintains a state-by-state map of retail food codes because requirements are implemented through state and local jurisdictions. Before fixing an overhead budget, confirm the actual state retail food rules, inspection program, permit fees, prepared-food requirements, and local building or fire obligations for the chosen site.
Key Takeaways
A realistic supermarket owner-income range can run from roughly $90K in a weak but positive case to about $577K in a strong case; the base model is $301K after reserves.
At supermarket scale, one percentage point of gross margin is worth six figures, so shrink, buying terms, markdowns, and fresh mix matter more than headline sales alone.
The base case is owner-operated. A manager-run version must add replacement management payroll before claiming the same distribution.
Safe owner cash comes after inventory, payroll, overhead, debt service, tax reserves, and reinvestment; accounting profit and distributable cash are not the same number.
Compare low, base, and high supermarket owner-income scenarios
The three presets keep sales, margin, staffing, overhead, marketing, debt, and reserves economically linked. The low case assumes softer volume and a 27% margin; the base case uses $1.27 million monthly sales and a rounded 28% planning margin; the high case adds payroll, overhead, marketing, and debt while lifting sales to $1.65 million and margin to 29%. These are planning cases, not promised outcomes.
Owner income scenarios
Low, base, and high cases show how supermarket sales, margin, staffing, overhead, financing, and reserves change owner cash.
Supermarket low, base, and high owner-income planning cases.
Scenario
Low CaseLow income
Base CaseBase income
High CaseHigh income
Launch model
Downside operating case with $1.05M monthly sales and softer margin.
Established owner-operated independent store at $1.27M monthly sales.
Strong-volume case at $1.65M monthly sales with added staffing and overhead.
Typical setup
$12.6M annual revenue, 27% gross margin, and $175K monthly labor.
$15.24M annual revenue, 28% gross margin, and $200K monthly labor.
$19.8M annual revenue, 29% gross margin, and $250K monthly labor.
Cost drivers
Labor $175K/mo
Overhead $80K
Marketing $7K
Debt $10K
Labor $200K/mo
Overhead $92K
Marketing $8K
Debt $10K
Labor $250K/mo
Overhead $112K
Marketing $12K
Debt $12K
Owner income rangeAfter modeled tax and reinvestment reserves
$89,700
After modeled reserves
$300,960
After modeled reserves
$577,200
After modeled reserves
Best fit
Stress test for weak traffic, promotions, and thinner merchandise margin.
Normal planning case for an established owner-operated independent supermarket.
Upside case for stronger volume, cleaner shrink, and better fresh or mix margin with added cost capacity.
!
Planning note: Scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
What are the six supermarket income drivers to track every week?
The best weekly dashboard does not start with owner draw. It starts with the six operating variables that create or destroy the draw: gross margin and shrink, transactions and basket, labor efficiency, inventory turns and availability, refrigeration and fixed overhead, and fresh plus digital mix. Track them in that order because each one affects the cash waterfall before the owner reaches the bottom.
1. Gross margin and shrink
Protect margin dollars, not just margin percentage
The fiscal-2025 independent-grocer results put total-store gross margin at 27.9% and shrink at 3.9% of sales. On the base store's $15.24 million revenue, every one percentage point equals about $152,400 a year. If the model margin slides from 28% to 27% with costs unchanged, the lost gross profit is about $152,400, just over half of the modeled $300,960 annual owner income. That is why a modest pricing win can be canceled by theft, spoilage, receiving errors, markdowns, or poor fresh ordering.
The quick math is simple: sales × gross-margin percentage produces gross profit. The owner never distributes the sales number; the owner distributes what survives after merchandise cost, payroll, overhead, financing, and reserves.
Track a margin bridge weekly
Separate causes so the team can act before month-end.
Booked gross margin by department
Shrink and markdown dollars
Fresh spoilage and yield
Vendor allowances and invoice cost
Price changes versus unit movement
Investigate a one-point margin miss immediately because supermarket profits are too thin to absorb it quietly.
2. Transactions and basket size
Build revenue from trips times spend per trip
The 2025 FMS/NGA study reported 8,609 weekly transactions per independent store in fiscal 2024 and a $34 in-store basket. Multiplying those gives about $292,700 of weekly sales before channel mix, close to the model's $15.24 million annual base. Broader 2025 supermarket data show a $49.06 in-store transaction and $106 online transaction, which illustrates why store format and channel must be identified before using a basket benchmark.
A $1 basket lift across 8,609 weekly trips adds about $447,700 of annual revenue. At a 28% planning gross margin, that is roughly $125,000 of extra annual gross profit before additional labor, promotions, fulfillment, and other costs. The right question is not “Can we raise basket?” but “Can we raise profitable basket without losing trips?”
Track traffic and quality of basket
Monitor volume and mix together, not one dashboard tile at a time.
Transactions by day and daypart
Average basket by channel
Units per basket
Promotion redemption and gross-margin dollars
Loyalty household frequency
Flag cases where promotions grow traffic but reduce total gross-profit dollars after discounting.
3. Labor efficiency and the owner's role
Price owner labor before calling the rest profit
Labor and benefits reached 16.3% of net sales in fiscal 2024. On $15.24 million of revenue, 16.3% equals about $2.48 million a year. The calculator uses $2.40 million of annual staff payroll in the base case because the owner covers general management and a planning owner-manager amount is reclassified out of payroll. That makes the output a blend of compensation for owner work and residual entrepreneurial return.
If the owner steps away, put replacement management back into labor cost before taking a distribution. Also watch throughput: FMI reports 2025 supermarket sales per labor hour of $217.83. Your own target should reflect service model, fresh departments, union status, local wages, and operating hours rather than copying a national figure blindly.
Schedule to sales, not habit
Labor control should preserve food safety and service while eliminating avoidable hours.
Sales per labor hour
Labor and benefits as % of sales
Overtime and call-out coverage
Turnover by department
Owner hours replacing paid management
When owner hours fall, raise the manager budget before forecasting the same take-home.
4. Inventory turns and in-stock execution
Make inventory work twice: availability and cash
Independent-grocer inventory turns fell from 17.8 to 16.1 in fiscal 2025, while out-of-stocks improved to 6.6%. Slower turns mean more cash is tied in inventory for each dollar of sales. Too little stock loses transactions; too much stock raises shrink, markdown, spoilage, and working-capital needs. The owner pays for both errors.
As a rough sensitivity, a store with annual merchandise purchases in the $11 million range can carry hundreds of thousands of dollars more inventory when turns slow materially. The exact cash effect depends on vendor terms and category mix, so use the receiving ledger and perpetual inventory rather than a generic “months of stock” rule.
Track turns with service level
A low inventory balance is not efficient if shelves are empty.
Inventory turns by department
Out-of-stock rate
Days of supply
Fresh shrink and aging
Vendor fill rate and lead time
Release owner cash only after the next replenishment cycle and major seasonal buys are funded.
5. Refrigeration, occupancy, and fixed overhead
Treat the cold chain as a profit center
ENERGY STAR says refrigeration may use up to 40% of a supermarket or grocery property's total energy. That makes compressor performance, case doors, temperature settings, seals, coils, lighting, and preventive maintenance financial controls as much as engineering tasks. The base model allows $92,000 a month for fixed overhead across occupancy, utilities, insurance, security, repairs, software, cleaning, and administration.
A 5% reduction in that base overhead would save $4,600 per month, or $55,200 a year before reserve effects. But deferred maintenance is not savings if it causes food loss or emergency equipment replacement. The operating decision is to lower normalized cost while protecting refrigeration uptime and product quality.
Benchmark the building monthly
Separate usage, rate, and failure costs so utility inflation is not confused with operating waste.
Utility cost per sales dollar
Refrigeration service calls
Temperature exceptions
Rent and occupancy as % of sales
Repair reserve versus emergency spend
Keep a capital plan for cases, compressors, HVAC, and backup power rather than distributing every good month.
6. Fresh departments, loyalty, and digital mix
Grow the mix that raises margin dollars without hiding labor
Fiscal-2025 reporting says produce, meat, deli, bakery, and seafood remained defining differentiators among the highest-performing independents. It also found online sales at only 1.1% of independent-grocer revenue, but with an average online basket roughly three times the typical in-store transaction. That creates opportunity, but online orders bring picking, substitution, packaging, platform, and delivery costs that must be modeled outside merchandise margin where appropriate.
Fresh and prepared categories can improve trip frequency and differentiation, yet they also carry specialized labor, food-safety, yield, and spoilage risk. The correct KPI is contribution after direct product loss and incremental labor, not simply department sales. A strong mix can lift the high case toward 29% gross margin; a poorly controlled one can do the opposite.
Track contribution by mission and channel
Use category and customer data to decide which growth actually funds the owner.
Fresh gross-margin dollars
Spoilage and markdown by department
Online basket and fulfillment labor
Loyalty frequency and retention
Private-label and prepared-food mix
Expand a channel only when its incremental gross profit covers the incremental labor, technology, and service cost.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.