How Much Does a Tour Bus Owner Make? $253K Year 1 EBITDA
A tour bus owner can make meaningful income, but owner take-home is not the same as revenue In the researched assumptions, Year 1 revenue is $925K and EBITDA is $253K, growing to $3075M revenue and $164M EBITDA by Year 5 That profit is before owner distributions, taxes, debt service, and cash reserves Seats sold, ticket price, trips, labor, insurance, financing, and off-season downtime drive the final owner income
Owner income$253K to $1.64MNet margin83% to 86%Revenue for target pay$3.08MBusiness difficultyHard
Want the six main tour bus income drivers?
1
Occupancy
$925K
Year 1 revenue is about $925K from 15.1K visits, so more filled seats lift EBITDA and owner pay fast.
2
Ticket Pricing
$45-$1.2K
City tours at $45, themed tours at $65, and charters at $1,200 give pricing real pull, so small fare lifts flow straight to cash.
3
Fixed Overhead
$457K
Year 1 payroll of $372.5K plus about $84.6K in fixed overhead is the biggest profit drag, so lean staffing protects take-home.
4
Direct Costs
$157K
Fuel, entry fees, commissions, and maintenance take 17% in Year 1, so every point saved drops straight into EBITDA.
5
Tour Frequency
15K-45K
Growing visits from 15.1K to 45.3K spreads the same staff and office cost across more sales, which improves margin.
6
Fleet Utilization
2 buses
Keeping both buses busy avoids dead capacity, while idle vehicles still carry insurance, fuel, and labor costs.
Want to test your tour bus owner income?
Owner income calculator
Estimate owner take-home and target-pay gap from revenue, margin, costs, reserves, and target pay.
!
Planning note: This is a researched planning estimate, not guaranteed salary, tax advice, or owner distribution advice.
Want to see the Tour Bus financial model dashboard?
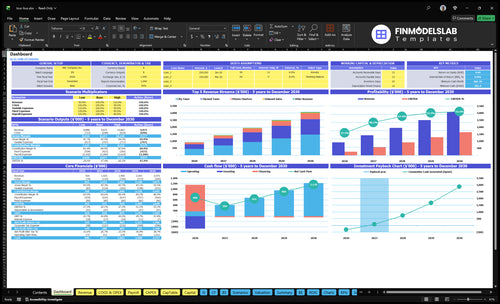
Open the Tour Bus Financial Model Template to see revenue, profit, cash flow, payroll, capex, reserves, and owner pay; Year 1 shows $925K revenue, $253K EBITDA, $470K capex, $581K minimum cash, and a 23-month payback.
Owner income model highlights
Owner pay scenarios
Route demand charts
Occupancy and pricing
Fleet cost and debt
Payroll and reserves
How much revenue does a tour bus business need to pay the owner?
For Tour Bus, the model shows $925K of revenue, 17% direct trip costs, $846K fixed overhead, and $3,725K payroll, with $253K EBITDA before owner pay. That means owner cash only starts after direct costs, overhead, payroll, reserves, and debt service are covered. Don’t call it a guaranteed salary unless the owner is on payroll.
Owner pay math
$925K revenue is the model base.
17% goes to direct trip costs.
$253K remains before owner pay.
Use cash left after reserves first.
What blocks owner pay
$846K fixed overhead must be covered.
$3,725K payroll is in the model.
Debt service comes before distributions.
Owner salary is only if on payroll.
What profit margin can a tour bus business earn?
A Tour Bus business can show a strong gross margin of 83% to 86% before payroll and overhead. In Year 1, direct trip costs are 17% of revenue, then 14% by Year 5, so the real profit swing comes from occupancy, wages, fuel, maintenance, and commissions; see How Much Does It Cost To Open And Launch Your Tour Bus Business? for startup context. EBITDA rises from $253K in Year 1 to $164M in Year 5, but that margin can shrink fast if seats go empty or repairs spike.
Margin drivers
17% direct trip costs in Year 1
14% direct trip costs by Year 5
83% to 86% gross margin before overhead
$253K to $164M EBITDA range
Cost pressure points
Fuel can move margins quickly
Attraction entry fees add direct cost
Partner commissions cut trip profit
Maintenance and repairs can spike fast
Does scaling a tour bus business increase owner income?
Yes—a Tour Bus business can increase owner income, but only if utilization stays high enough to cover the added costs. In the model, revenue rises from $925K in Year 1 to $3,075M in Year 5 as visitors, charters, and add-on sales grow, while payroll also climbs from $3,725K to $7,075K; so more buses help only when seats stay full.
Where income can rise
$925K Year 1 revenue.
$3,075M Year 5 revenue.
Visitor, charter, and add-on income grow.
Owner-operated models can protect early cash.
What limits the upside
Payroll rises from $3,725K to $7,075K.
More buses add dispatch and maintenance.
Compliance, storage, financing, and downtime also rise.
Managed models need stronger volume.
Key Takeaways
Seat occupancy drives revenue without matching cost growth.
Pricing lifts yield, but demand caps the ceiling.
Fleet utilization matters because buses are expensive assets.
Overhead, direct costs, and reserves cut take-home.
Compare low, base, and high tour bus owner income scenarios
Scenario view
Owner income moves with trip volume, ticket price, fleet size, labor, and reserve needs. This table shows a lean launch, the base model, and a stronger Year 5 scale.
Lean, base, and upside cases for owner income.
Scenario
Low CaseLean case
Base CaseModeled case
High CaseUpside case
Launch model
A low-demand case keeps trips light and owner draw thin.
This is the modeled operating case with steady demand and balanced staffing.
A stronger case pushes toward full buses, more trips, and better spread of fixed costs.
Typical setup
Lower occupancy, fewer tours, and more commission-heavy bookings keep revenue and margin under pressure while the owner stays hands-on.
Year 1 lands at $925K revenue and $253K EBITDA, with 17% direct costs, $84.6K fixed overhead, about $372.5K payroll, $470K capex, a $581K cash floor, and a 23-month payback.
Higher ticket prices, more trips, a bigger fleet, and a fuller labor plan push Year 5 to about $3.075M revenue and $1.64M EBITDA.
Cost drivers
Occupancy
trip volume
commission mix
fuel
labor
Ticket mix
occupancy
labor mix
fuel
OTA commissions
High occupancy
more trips
higher ticket prices
bigger fleet
fixed-cost spread
Owner income rangeBefore owner reserves
Minimal owner drawDownside case
$253K EBITDAModel case
Year 5 upside drawUpside case
Best fit
Use this to test cash strain if bookings stay soft and the owner has to cover more day-to-day work.
Use this as the main planning case for budgeting, hiring, and cash checks.
Use this to test what happens if demand stays strong and the fleet keeps running near capacity.
!
Planning note: Scenario ranges are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distributions.
Tour Bus Core Six Income Drivers
Paid Seat Occupancy
Paid Seat Occupancy
When more seats sell on each tour, the operator turns the same driver time, fuel, insurance, and vehicle cost into more revenue. The core metric is seats sold per tour, or capacity utilization (the share of seats filled). With Year 1 demand of 5,000 themed tour visitors and 10,000 city tour visitors, fill rate is a direct lever on owner take-home.
Here’s the quick math: an extra rider usually adds ticket revenue without a matching jump in cost, so gross margin improves when the bus runs fuller. The catch is weak weekday and off-season demand. If those trips go out half-empty, the same route can still lose cash and leave less profit to pay the owner.
Track fill rate by route and day
Measure seats sold per tour, capacity utilization, and booked seats versus capacity before each departure. Watch it by themed tour, city tour, weekday, weekend, and season, because the weak days usually drag down the whole month.
Bus seats available per trip
Seats sold per tour
Fill rate by day and season
Ticket revenue per trip
If fill rate drops on slow days, tighten the schedule, test group offers, or shift capacity to higher-demand times so extra riders add profit instead of just adding noise to the forecast.
Overhead, Compliance, And Reserves
Fixed Overhead And Reserves
This driver is the cash you spend before any ticket revenue reaches you. Fixed overhead is $7,050 per month, or $84,600 a year from the disclosed monthly run rate, and it includes $2,000 for vehicle insurance and $200 for licenses and permits. Office rent, software, admin, marketing, accounting, storage, and repair reserves all cut distributable cash.
That means owner pay only starts after compliance and reinvestment needs are covered. If demand is soft in a weekday or off-season month, overhead still lands, so profit can disappear even when the buses look busy on paper.
Track Cash Before Owner Pay
Track this as a monthly cash test, not just a budget line. Here’s the quick math: fixed overhead + repair reserve + owner pay must fit inside cash after direct trip costs. If you sell more seats or raise ticket yield, some of that gain still needs to stay in reserve so one repair or slow month does not hit payroll or the owner draw.
Watch overhead by month.
Separate repair cash from operating cash.
Pay yourself after reserves.
Review insurance and permit renewals early.
If the reserve account stays empty, the business is paying out cash too fast. A bus break or seasonal dip can force short-term borrowing, and that makes owner income less reliable even when annual revenue looks fine.
Fleet Utilization And Vehicle Cost
Fleet Utilization
When two buses cost $400K of the $470K startup capex, the owner only gets paid well if those assets stay busy. At roughly $200K per bus, weak use hurts cash because financing, depreciation, storage, insurance, and maintenance keep running even when seats are empty.
The key input is paid operating days across city tours, themed routes, private charters, and events. Here’s the quick math: higher utilization spreads fixed vehicle cost over more ticket sales, so take-home rises only when extra trips add revenue faster than they add fuel, labor, and wear. Idle time is the silent margin leak.
Track Bus Hours, Not Just Revenue
Measure seat-hours sold, bus-days used, and revenue per bus-day. If one bus is booked on weekdays and the other only on weekends, the fleet is underworked even if top-line sales look fine. The owner should forecast utilization by route type and season, then compare it to monthly vehicle costs.
Track paid miles and idle days.
Split use by tour, charter, event.
Price peak dates above slow periods.
Cut downtime with tighter maintenance.
What this estimate hides: a bus that runs more can still lower profit if it needs too many repairs or sits between bookings. The goal is simple: keep each bus earning across more of the calendar so fixed vehicle cost gets smaller per trip and owner income climbs.
Ticket Price And Passenger Yield
Ticket Price And Yield
Ticket price is the fastest way to lift revenue per passenger, because the same seat can earn $65 on themed tours, $45 on city tours, or $1,200 on private charters in Year 1. One clean rule: higher fare helps only if demand holds. Once discounts, group rates, online booking fees, and partner commissions hit the sale, the owner cares about realized yield (cash kept per passenger), not list price.
Here’s the quick math: revenue per trip equals passengers × realized fare. So a fare increase can raise gross margin without adding seats, but it can also slow bookings if the market pushes back. The real risk is assuming prices can climb forever; demand and competition still set the ceiling, and weak fill rate can erase the gain.
Measure Realized Fare
Track listed price, average realized fare, discount rate, commission rate, and revenue per passenger by tour type. If private charters book at $1,200 but require heavy partner commissions, net yield may trail a smaller direct booking. What matters is cash after all sales cuts, because that is what pays fuel, guides, overhead, and the owner draw.
Test price in small steps by tour type, then watch seats sold, booking pace, and refund rate. Keep a floor for each product: themed tours at $65, city tours at $45, and charters at $1,200 in Year 1. If a higher fare slows conversion or pushes more sales to discount channels, the extra revenue may not reach take-home pay.
Track net revenue per passenger
Separate direct and partner sales
Measure discount and fee drag
Review price by tour type
Trips Per Day And Operating Days
More Trips and More Open Days
More trips per day and more operating days raise schedule revenue only when demand, permits, staff, and buses can support it. With 15,000 Year 1 visits across themed and city tours plus 100 private charters, the gain comes from turning more route time into sold seats, not from running empty buses.
Here’s the quick math: revenue = trips × days × average seats sold × ticket price. The catch is cost per extra run, because each added trip brings fuel, cleaning, driver hours, guide hours, maintenance, and downtime. If added trips stay half-full, revenue rises slower than cost, and owner take-home gets squeezed.
Fill Trips Before Adding Runs
Measure trips/day, days open, seats sold per trip, and revenue per run. Add departures only when the extra trip covers variable costs and still leaves margin after the model’s 17% Year 1 direct cost rate.
Test longer hours one route or one season at a time. If weekday or off-season demand is soft, hold the schedule tight and push advance sales and charter fill first. That protects cash from extra labor, cleaning, and fuel before the seats are sold.
Track fill rate by departure.
Watch profit by daypart.
Separate charter and tour demand.
Direct Trip Costs
Direct Trip Costs
Direct trip costs are the bus-level costs tied to each tour: fuel, driver wages, guide payroll, maintenance, cleaning, parking, tolls, and booking commissions. They sit below revenue and before overhead and owner pay, so they set the gross margin the owner can draw from. In the model, these costs are 17% of revenue in Year 1 and ease to 14% by Year 5.
Here’s the quick math: if fuel jumps, repairs bunch up, or partner commissions rise faster than direct bookings, the owner keeps less cash from each trip. Payroll is separate and starts at $3,725K in Year 1, so trip costs have to stay tight just to protect take-home income. Lower trip cost rate = more profit per sold seat.
Track Cost per Trip
Measure each route by cost per trip, cost as % of revenue, and cost per seat sold. Split the cost into fuel, labor, cleaning, maintenance, tolls, parking, and commissions so you can see what moved when margin slips. If direct bookings rise, commissions should fall as a share of sales; if not, owner income gets squeezed fast.
Track fuel by route and mile.
Log repairs the day they happen.
Separate guide and driver hours.
Watch commission rate by channel.
Compare empty seats to trip cost.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Tour Bus Bundle
Choosing a selection results in a full page refresh.