What Is the Earning Potential for Toy Manufacturing Business Owners?
A U.S. owner-operated toy manufacturer can realistically produce about $139,000 a year of modeled owner income in a stabilized base case, after the business pays non-owner payroll, overhead, marketing, monthly debt service, and a 24% tax reserve plus an 8% reinvestment reserve. This article models a small company with several proprietary toy lines, light in-house assembly and packaging, outsourced components, and a mix of wholesale and direct-to-consumer sales. The base case assumes about $2.64 million of annual revenue, a 45% non-labor gross margin, and $82,000 of monthly operating costs before owner pay. The figure is not a guaranteed salary or GAAP net income, and it does not promise that all accounting profit is safe to distribute; inventory builds, receivables, product testing, recalls, tooling, and personal tax circumstances can all reduce cash available to the owner.
Owner income$139KNet margin5%Revenue for target pay$2.58MBusiness difficultyHard
What does $139K of toy manufacturing owner income require?
The base case requires a business that has moved beyond hobby-scale production: about $220,000 of average monthly sales, reliable reorder demand, and enough throughput to spread payroll and facility costs across roughly 10,000 shipped units a month at a reasoned blended net manufacturer price near $22. Demand is available, but it is not uniform. The Toy Association reports approximately $30.3 billion of tracked U.S. retail toy sales in 2025, up 6%, while its June 2026 update reported 13% U.S. dollar growth through April 2026. Those are retail-market figures, not a promise for a new manufacturer, so the calculator uses volume, price, margin, payroll, and reserves rather than market growth as the earnings engine.
Owner income calculator
Test how sales, non-labor gross margin, payroll, overhead, debt, and reserves change owner take-home.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
1
Units sold × net price
10K units/mo
The base case pairs roughly 10,000 shipped units with a $22 blended net manufacturer price; a 5% revenue miss can erase most of the monthly owner cushion.
2
Non-labor gross margin
45% base
Materials, packaging, outsourced components, freight, and fulfillment set how much revenue remains before payroll; every margin point on $220,000 is $2,200 a month.
3
Payroll per shipped unit
$4.40/unit
Base non-owner payroll of $44,000 divided by about 10,000 units makes labor productivity visible before the owner takes any cash.
4
Inventory cash cycle
8% reserve
Tooling, raw materials, finished goods, and retailer receivables can consume cash before profit is distributed, so the base case retains part of positive profit.
5
Customer acquisition mix
5.9% of sales
The base marketing budget is $13,000 a month; wholesale sell-in, trade support, and DTC acquisition must create repeatable contribution, not just top-line volume.
6
Debt + fixed capacity
$25K/mo
Base fixed overhead plus debt service is $25,000 monthly before payroll and marketing, creating a hard floor that weak months still have to carry.
Want to test the assumptions in a full toy forecast?
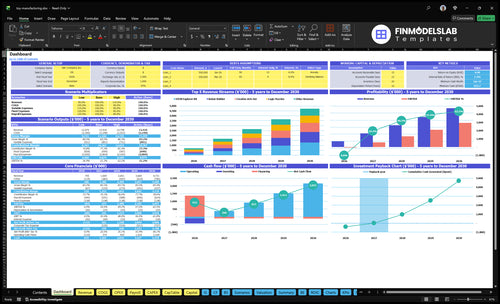
The Toy Manufacturing Financial Model Template includes a dashboard that connects revenue, gross margin, payroll, cash flow, and scenario outputs. Use the screenshot to pressure-test whether your unit volume, product mix, hiring plan, and cash reserve tell the same story before you treat projected profit as owner income.
Compare low, base, and high demand cases.
Check revenue mix against payroll and operating costs.
Trace profit into cash flow before planning distributions.
How many toys must you sell to support six-figure owner pay?
In this model, six-figure owner pay starts around the point where monthly revenue is consistently above $200,000, not merely when one holiday shipment spikes. At the base assumption of a $22 blended net manufacturer price, $220,000 of monthly revenue is about 10,000 units. The mix matters: wholesale volume often carries a lower net price, while DTC sales can raise revenue per unit but add fulfillment, returns, payment fees, and acquisition cost. For children’s products, scale can also change compliance economics; CPSC says its small-batch relief is product-specific and tied to qualifying thresholds, including no more than 7,500 units of a covered product in the prior year, while underlying safety requirements still apply.
Base volume math
$220,000 monthly revenue ÷ $22 blended net price = about 10,000 units.
A 500-unit monthly shortfall at $22 removes about $11,000 of revenue before any cost response.
Track shipped units, net price after allowances, cancellations, and returns by channel.
What this estimate hides
A $30 retail shelf price is not the same as the manufacturer’s $30 net revenue.
Retailer discounts, promotional allowances, freight, marketplace fees, and chargebacks can lower realized price.
Seasonal orders can pull production and cash needs forward by weeks or months.
A growing SKU count can increase testing, packaging, tooling, and slow-moving inventory.
What margin can a small toy manufacturer realistically protect?
A prudent planning target is roughly 40% to 49% of revenue left after non-labor direct product costs, with 45% used in the base calculator. This is a model assumption, not an industry guarantee. As an adjacent large-company reference, Mattel reported a 48.7% gross margin for 2025, but its scale, brand portfolio, sourcing network, royalties, and accounting are very different from a small manufacturer. The calculator therefore does not import that margin directly: it treats materials, components, packaging, freight, outsourced production, fulfillment, and payment costs as direct costs, while all employee payroll sits separately in labor cost.
Why one margin point matters
At $220,000 monthly revenue, one gross-margin point equals $2,200 of monthly gross profit.
Moving from 45% to 43% removes $4,400 before payroll, rent, marketing, and debt change.
If the business was earning $11,560 of modeled monthly owner income, that two-point compression can cut the owner cushion by more than one-third before reserves recalculate.
Separate purchase-price variance, freight, scrap, rework, and retailer allowances so the source of margin erosion is visible.
Do not hide labor inside gross margin
The calculator’s $44,000 base labor line includes non-owner payroll and employer burden.
The base model supports about $138,720 of annual owner income only after $2.64 million of annual revenue and a 45% non-labor gross margin.
Operating break-even before owner pay is roughly $182,000 of monthly revenue; the modeled $10,000 monthly owner-pay target needs about $214,902.
Payroll, inventory, compliance, and retailer payment timing can consume cash even when the income statement is profitable.
Can the business pay the owner without starving inventory?
Only if the owner treats working capital as a claim on cash before discretionary distributions. Toy manufacturing often pays for materials, packaging, tooling, testing, and assembly before finished goods are sold, and wholesale customers may pay after shipment. The base calculator therefore retains 8% of positive profit for reinvestment even after a separate 24% tax reserve. Financing can help bridge that timing: SBA says 7(a) loans can fund working capital and machinery or equipment, but debt converts a working-capital problem into a fixed monthly payment, which is why the base model carries $6,000 of debt service.
Debt principal and interest, not just interest shown on an accounting P&L.
Inventory needed for confirmed orders plus a controlled safety stock for repeat sellers.
Testing, corrective actions, replacement tooling, and launch spend for the next production cycle.
Compliance is a cash-flow item
CPSC states that ASTM F963 is a mandatory toy safety standard and that children’s toys generally require applicable certification; see the CPSC toy safety guidance.
Budget compliance per SKU and production change, not as one generic annual fee.
How should owner salary and owner distributions be separated?
Think of owner compensation as two questions: what is the owner paid for work, and what residual profit can ownership distribute? The calculator deliberately answers the second question in cash terms after modeled operating costs and reserves; it does not put owner pay inside the labor line, because that would count the same economic benefit twice. In an actual S corporation, however, the IRS says a shareholder-employee who performs services must receive reasonable compensation before non-wage distributions. So a real payroll implementation may split the modeled owner-income pool between W-2 salary and distributions, with payroll tax and personal tax consequences determined separately.
Owner-operated case
The owner acts as general manager, product decision-maker, and key-account closer.
Base non-owner payroll stays at $44,000 per month; owner cash is the residual $11,560 after modeled reserves.
For reference, BLS put the May 2024 median for industrial production managers at $121,440; use the production-manager wage data only as a compensation reference, not a promise of owner salary.
If the legal entity requires payroll to the owner, translate part of the owner-income pool into wages without also recording it as a second distribution.
Manager-run case
Add a hired manager’s fully loaded cost to labor before estimating passive distributions.
A $10,000 monthly owner target does not become safe merely because accounting profit is positive.
At base assumptions, operating break-even is about $182,222 monthly revenue before owner pay; the target-pay formula raises required revenue to about $214,902.
Passive income should be the amount left after the replacement management team, reserves, debt, and working capital are funded.
What do low, base, and high owner-income cases look like?
The scenarios below use the calculator’s same nine inputs, so the owner-income row is not a separate editorial estimate. The low case protects fixed costs but does not manufacture a profit by pretending payroll disappears with demand; the high case adds staff, marketing, overhead, debt service, and a larger reinvestment reserve as volume expands. Wage assumptions are anchored to the labor market rather than free owner labor: BLS reported a $43,570 median annual wage for assemblers and fabricators in May 2024, while manufacturing industrial designers had a $76,240 median wage in the same period.
Owner-income scenarios
Three coherent operating cases using the same calculator presets for revenue, margin, payroll, overhead, marketing, debt, and reserves.
Low, base, and high planning cases for a U.S. owner-operated toy manufacturer.
Scenario factor
Low CaseSlow sell-through
Base CaseStabilized
High CaseScaled demand
Launch modelRevenue engine
$130K monthly revenue
40% gross margin
About 6,500 units at $20 net
$220K monthly revenue
45% gross margin
About 10,000 units at $22 net
$350K monthly revenue
49% gross margin
About 14,000 units at $25 net
Typical setupTeam and capacity
$32K labor
$18K fixed overhead
$9K marketing
$44K labor
$19K fixed overhead
$13K marketing
$65K labor
$28K fixed overhead
$25K marketing
Cost driversCash commitments
$5K debt service
22% tax reserve
8% reinvestment reserve
$6K debt service
24% tax reserve
8% reinvestment reserve
$8K debt service
25% tax reserve
10% reinvestment reserve
Owner income rangeAfter modeled tax and reinvestment reserves
$0/year
$138,720/year
$354,900/year
Best fitOperating profile
Early-stage brand with uneven wholesale reorders and the owner covering several functions.
Established small brand with repeat retail accounts, disciplined SKU count, and mixed channels.
Scaled small manufacturer with broader retail distribution, stronger mix, and added staffing.
!
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
Which six drivers move toy manufacturing owner income most?
The six drivers below are ranked by how quickly they change the cash pool available to the owner in this model. They also reinforce why revenue, EBITDA, accounting profit, salary, and safe distributions are not interchangeable. U.S. toy demand can grow while an individual manufacturer loses money if its product mix misses the market; the Toy Association’s 2025 data showed large category differences, with games and puzzles up 37% while several other supercategories declined. Build owner-income decisions around your own sell-through and cash conversion, not industry headlines.
1. Units sold and realized net price
Build revenue from shipped units, not wish-list retail prices
The base case uses 10,000 monthly shipped units at about $22 of net manufacturer revenue each. That is $220,000 of monthly sales. A 5% unit shortfall with price unchanged removes 500 units, or $11,000 of sales. At a 45% gross margin, the immediate gross-profit loss is about $4,950 before payroll or rent can react. That would cut the modeled $17,000 profit-before-reserves pool by almost 30%.
Realized price should be measured after wholesale discounts, promotional allowances, returns, marketplace fees, and any freight treated as a direct sales cost. A premium shelf price is useful only if enough of it reaches the manufacturer. The 2026 market update reported that average toy selling price was rising faster than units, but your own net price can still fall if retailers demand more support or your channel mix shifts.
Track sell-through before scaling production
Use a weekly revenue bridge that separates volume from price and channel mix.
Units shipped and units returned by SKU.
Net revenue per unit by customer and channel.
Reorder rate for the top 20 accounts.
Weeks of finished-goods inventory by SKU.
Do not authorize a bigger run because gross orders look strong; confirm the net price and cash collection pattern first.
2. Non-labor gross margin
Protect product economics before adding payroll
The base gross-margin assumption is 45%, meaning $99,000 of a $220,000 month remains after non-labor direct product costs. If margin improves to 47% with revenue unchanged, gross profit rises by $4,400 monthly. With other inputs unchanged, almost all of that improvement reaches profit before reserves, making sourcing and product architecture more powerful than a similarly sized percentage reduction in a small overhead line.
Use large public-company margins only as context. Mattel’s 2025 gross margin was 48.7%, but a small manufacturer lacks its purchasing scale and brand economics. A founder should reconstruct each SKU’s bill of materials, packaging, freight, outsourced processing, fulfillment, royalties if any, payment costs, and expected scrap instead of borrowing a headline industry percentage.
Watch margin leakage by SKU
Separate standard cost from the reasons actual cost changed.
Material and component purchase-price variance.
Scrap, rework, and defect rate.
Freight and fulfillment cost per shipped unit.
Gross margin by SKU after retailer allowances.
A low-margin bestseller can consume capacity while leaving less owner cash than a smaller, better-designed product line.
3. Payroll per shipped unit
Scale labor only when throughput can carry it
Base non-owner labor is $44,000 per month, or about $4.40 per unit at 10,000 units. If the same team ships only 8,000 units, labor rises to $5.50 per unit even though payroll itself did not change. That is why seasonal under-utilization is dangerous: manufacturing labor has a variable component, but supervisors, design, QA, receiving, and customer support do not disappear when volume slips.
BLS notes that assemblers and fabricators build products including toys, and its May 2024 median wage for the occupation was $43,570. Employer cost is higher than wage alone once benefits and legally required costs are included. The base payroll therefore models loaded employer cost, not just hourly pay on a job posting.
Manage labor with throughput metrics
Measure productivity without encouraging quality shortcuts.
Loaded labor dollars per good unit shipped.
Units per paid production hour.
Rework hours as a percent of assembly hours.
Overtime hours before and after major launches.
The owner should cover a real managerial role only by choice; if the business needs the owner to work unpaid to show profit, it has not reached passive-owner economics.
4. Inventory and working-capital discipline
Convert accounting profit into cash before distributing it
A toy maker can post a profitable month while cash falls because the company pays suppliers for the next run and waits for retailers to pay the last one. The base case therefore retains 8% of positive profit as a reinvestment reserve. That is only a policy placeholder: a company with long lead times, concentrated holiday orders, or slow-paying wholesale accounts may need much more.
Compliance can extend the cash cycle too. CPSC’s toy guidance says children’s toys manufactured after April 20, 2024 must meet ASTM F963-23 where applicable, and certification requirements depend on the product. The point for owner income is simple: money committed to compliant inventory and testing is not simultaneously safe for an owner draw.
Track the cash conversion cycle by production run
Build a run-level cash schedule before committing purchase orders.
Supplier deposits and days payable.
Raw-material, work-in-process, and finished-goods days.
Wholesale days sales outstanding and overdue receivables.
Cash committed to the next tested production run.
Pause discretionary distributions if the next production cycle cannot be funded without stretching suppliers or missing payroll.
5. Customer acquisition and channel mix
Buy repeat demand, not one-time revenue
The base marketing line is $13,000 a month, about 5.9% of revenue. That budget can cover trade-show activity, samples, retailer support, creative, paid social, and DTC acquisition. The high case raises marketing to $25,000 because $350,000 of monthly revenue requires broader distribution and more demand support; keeping marketing frozen while revenue jumps would make the scenario artificially optimistic.
Wholesale and DTC should be judged on contribution after their channel-specific costs. DTC may offer a higher selling price but incur acquisition, pick-pack, payment, and return costs. Wholesale may lower price but provide larger orders and more predictable reorders. The owner-income question is not which channel has the highest revenue; it is which produces the most cash after product cost, acquisition cost, labor load, and working capital.
Measure acquisition against contribution
Make each channel prove it can fund the next order.
Contribution margin after channel fees and marketing.
DTC customer acquisition cost and 90-day repeat rate.
Wholesale reorder rate and markdown support per account.
Revenue concentration in the top five customers.
If a new retailer adds volume but demands deep allowances and long payment terms, owner cash may fall even as sales rise.
6. Debt service and fixed-capacity decisions
Keep the fixed-cost floor below normal gross profit
The base case carries $19,000 of fixed overhead and $6,000 of monthly debt service. Add $44,000 of payroll and $13,000 of marketing and total operating costs reach $82,000 before owner reserves. At a 45% gross margin, operating break-even is about $182,222 of monthly revenue. The $10,000 owner-pay target, after the 32% combined reserve policy, pushes the calculator’s required revenue to $214,902 a month.
This is the clearest distinction between accounting profit and safe owner cash. A new molding machine can lower unit cost and still reduce distributions if its payment arrives before utilization does. A larger warehouse can support holiday volume and still be a bad decision if the extra capacity sits empty nine months a year. Match debt and lease commitments to demonstrated demand, not the high-case forecast.
Stress-test fixed commitments before signing
Run the downside case with no assumption that costs fall instantly.
Monthly fixed overhead plus principal and interest.
Gross profit at 80%, 90%, and 100% of planned unit volume.
Debt-service coverage before owner distributions.
Months of cash runway after inventory deposits.
The low scenario shows the warning: $130,000 of monthly revenue at a 40% gross margin produces $52,000 of gross profit against $64,000 of operating costs, leaving no safe modeled owner income.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Toy Manufacturing Bundle
Choosing a selection results in a full page refresh.