How Much A Trigger Point Therapy Practice Owner Makes: $85K-$368K
Trigger Point Therapy Practice Bundle
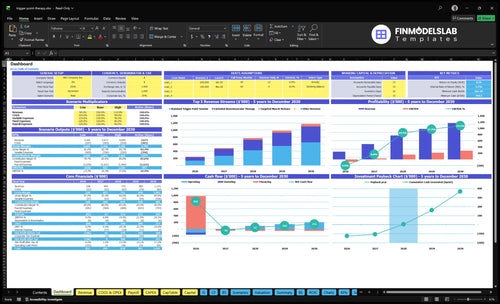
A trigger point therapy practice owner can plan around $85k in modeled lead therapist pay, plus possible profit distributions once the clinic is profitable and cash is safe In this case, business profit is negative in the first year at -$82k EBITDA, so owner take-home should not assume distributions early By the fifth year, revenue reaches $1174M and EBITDA reaches $283k, which could support up to $368k of pre-tax owner income if the owner takes the $85k lead therapist role and distributes all EBITDA That full distribution is not automatic because reserves, debt service, reinvestment, and taxes still come first
Owner income$85k–$368kNet margin31%–34%Revenue for target pay$248k–$1.174MBusiness difficultyHard
Want to test your owner pay?
Owner income calculator
Estimate owner take-home and the target-pay gap from revenue, margin, costs, reserves, and target pay.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice. It excludes taxes, personal benefits, clinical claims, and guaranteed distributions.
Want the six income drivers?
1
Booked Sessions
46-144/wk
More booked sessions is the fastest path to higher owner pay, since each filled slot spreads the same rent and core staff cost over more visits.
2
Session Price
$120.5
The first-year weighted service price is about $120.5, so even small price lifts drop straight to take-home after variable costs.
3
Labor Mix
$243K-$541K
Payroll rises from about $243K to $541K as the team grows, so staffing mix is the biggest swing in margin and owner income.
4
Referrals
80%-60%
Stronger retention and referrals can cut paid marketing from 80% to 60% of the growth load, which protects cash and boosts payback.
5
Room Use
M14
Better scheduling and room turnover help the clinic reach Month 14 breakeven, and every month earlier improves owner cash flow.
6
Overhead
$75K
Keeping fixed overhead near $75K a year preserves cash for the owner, while rent and admin creep push breakeven out.
Want to see the forecast model for Trigger Point Therapy Practice?
What expenses most affect trigger point therapy practice profit margin?
The biggest hit to profit margin in a Trigger Point Therapy Practice is payroll, followed by fixed overhead and high-fee variable costs; if you’re mapping this for How To Write Trigger Point Therapy Practice Business Plan?, start with those three lines. Fixed costs total $6,250 per month ($4,500 rent, $650 utilities and internet, $250 liability insurance, $500 cleaning, $150 software, and $200 office supplies). Payroll is the largest cost, rising from $243k in year 1 to $541k in year 5, and cancellations hurt twice because payroll and rent still run.
Fixed cost drag
$4,500 monthly rent
$650 utilities and internet
$250 liability insurance
$500 cleaning, $150 software, $200 supplies
Variable cost pressure
Treatment consumables and linens: 40% to 30%
Retail inventory: 50% to 40%
Marketing and referrals: 80% to 60%
Booking and payment fees: 30%
How much can a solo trigger point therapist make?
A solo Trigger Point Therapy Practice can generate about $313,200 in first-year gross revenue if the owner handles most sessions: 2,400 visits × $120.50 plus $10 retail per visit. For setup details, see How To Start Trigger Point Therapy Practice?.
Revenue math
8 visits/day
300 working days
46 weekly sessions
$313,200 gross revenue
Income levers
Avoid $65k therapist payroll
Delay $55k manager cost
Skip $38k front desk wage
Watch burnout and rebooking gaps
Does hiring therapists increase trigger point therapy owner income?
Yes—but only if the added therapists fill paid sessions at a healthy labor margin. In the base case, headcount rises from 10 FTE in year 1 to 50 FTE in year 5 at $65k each, visits increase from 8 to 25 per day, and revenue moves from $248k to $1.174M. EBITDA improves from -$82k to $283k, so hiring can lift owner income after ramp-up, but only if payroll, supervision, and scheduling stay tight.
When hiring helps
Fill more paid sessions.
Push visits from 8 to 25/day.
Keep labor margin healthy.
Scale from 10 to 50 FTE.
What can hurt income
Payroll grows before demand.
Supervision takes owner time.
Quality slips across providers.
Cash needs rise during ramp-up.
Key Takeaways
Booked sessions drive revenue as volume scales.
Pricing changes flow through every paid visit.
Payroll only works when booked hours cover wages.
Breakeven comes after fixed costs and reserves.
Compare lean, base, and high owner-income scenarios
Owner income scenarios
Heavy payroll and fixed rent keep owner income low until visits rise; once the clinic fills, EBITDA starts to support real distributions.
Owner income by ramp speed and capacity.
Scenario
Low CaseLean case
Base CaseBase case
High CaseUpside case
Launch model
A first-year ramp with 8 visits a day keeps owner pay thin and leaves no safe profit distribution.
A mid-ramp clinic with 18 visits a day can support solid owner income if overhead stays tight.
A mature clinic with 25 visits a day can throw off strong owner income if volume holds and costs stay contained.
Typical setup
About 46 weekly sessions, $248k revenue, and -$82k EBITDA under heavy payroll and fixed rent.
About 104 weekly sessions, $773k revenue, and $154k EBITDA with tighter marketing and a fuller service mix.
About 144 weekly sessions, $1.174M revenue, and $283k EBITDA with fuller staffing and stronger room use.
Cost drivers
Lead therapist payroll
staff therapist payroll
rent and utilities
marketing and referrals
booking fees
Balanced staffing
rent and overhead
marketing and referrals
consumables
booking fees
Full therapist schedule
rent and overhead
marketing and referrals
booking fees
retail sales
Owner income rangeBefore owner reserves
$85kNo safe profit
$239kModeled income
$368kFull upside
Best fit
Use this to stress-test reserves and a slow opening month.
Use this as the working plan for a clinic that needs steady fill and tight margin control.
Use this to test upside, but keep cash reserves because staffing and demand swings can cut take-home fast.
!
Planning note: These ranges are researched planning assumptions only; they are not guaranteed earnings, salary promises, tax advice, or required distributions.
Trigger Point Therapy Practice Core Six Income Drivers
Booked Treatment Sessions
Booked Sessions
Booked sessions are the paid visits that actually land on the calendar. Here’s the quick math: volume moves from 8 visits per day in year 1 to 25 visits per day by year 5, or from 2,400 to 7,500 annual sessions on 300 operating days. Weekly volume rises from 46 to 144 sessions, so more of the day has to turn into paid time for owner income to grow.
No-shows and cancellations are the leak. Empty slots still leave rent and payroll in place, so each missed visit hits cash flow and profit fast. The owner’s own hands-on capacity matters too: this is physical work, and admin time still has to get done.
Fill the Calendar
Track booked visits per day, no-show rate, cancel rate, and rebook rate. Also track available treatment hours versus paid hours, so you can see whether growth is coming from fuller schedules or longer days. If visits rise but gaps stay open, the calendar looks busy while take-home pay stays weak.
Rebook before the client leaves
Confirm visits early
Use waitlists to backfill gaps
Protect admin blocks each week
Protect income by cutting idle time between sessions and keeping peak hours full. With fixed overhead, every extra paid slot helps cover costs and leaves more room for owner draw.
Treatment Room Utilization And Scheduling
Room Utilization
Empty rooms still cost money. Clinical facility rent is $4,500 per month, so the goal is to turn every open hour into paid care. With planned volume rising from 8 visits a day in year one to 25 in year five, poor scheduling turns fixed rent into dead cost and cuts owner pay.
Here’s the quick math: at 300 operating days, that is 2,400 to 7,500 sessions a year. Rent alone equals $54,000 a year, so rent load drops from $22.50 per session at 8/day to $7.20 at 25/day. Gaps between 60-minute, 90-minute, and targeted sessions are the leak.
Fill the Calendar, Not Just the Day
Track booked hours, gap minutes, cancellation rate, and waitlist fills. Those inputs show whether the room is earning enough to cover fixed rent and staff time. If a 90-minute visit leaves a 30-minute hole, that slot still pays $0, so utilization matters more as visits move from 8 to 25 per day.
Use cancellation rules, same-day waitlists, and peak-hour coverage to backfill lost visits. Keep buffer time where it protects quality, but don’t let buffers become idle blocks. One clean rule helps: protect prime slots first, then fit targeted sessions around them. That keeps rent tied to revenue, not to empty chairs.
Average Session Revenue
Average Session Revenue
When each booked slot brings in more money, the owner’s take-home rises faster than headcount. The model’s first-year weighted service price is $12050 across $110 standard sessions, $160 extended sessions, and $65 targeted sessions, so pricing changes flow through every visit. More retail and a bigger extended-session mix lift revenue without needing more booked hours.
Here’s the quick math: retail adds $10 per visit in year 1 and $15 by year 5, so at 7,500 annual sessions that is a swing from $75,000 to $112,500 a year. A shift in extended neuromuscular therapy from 30% to 40% can raise average revenue, but longer sessions also reduce daily slot capacity if the calendar is full.
Price the mix, not just the visit
Track average revenue per visit by session type, retail attach rate, and package share. Use a simple check: if the 60-minute mix is too heavy, test a better-priced 90-minute offer and see whether revenue per booked hour improves enough to cover slower turnover. Keep premium positioning tied to service depth, not clinical promises.
Measure revenue per booked slot weekly.
Track standard, extended, targeted mix.
Set add-on and retail attach goals.
Test packages for prepaid cash flow.
Watch whether longer sessions cut throughput.
If add-ons raise ticket size but add too much time, they can lower total profit. The right test is simple: higher average session revenue should improve cash collected, gross margin, and owner pay after labor and room costs, not just top-line sales.
Provider Labor Mix
Provider Labor Mix
Owner pay depends on who brings in revenue and who gets paid first. Modeled payroll is $243k in year 1 and $541k in year 5, with a $85k lead clinical therapist, $65k staff therapists, $55k for the clinic manager, and $38k for front desk coverage. If booked sessions do not cover wages, marketing, supplies, and room costs, labor growth cuts into owner income fast.
Here’s the quick math: hired therapists create scale only after their booked sessions pay for their own wages and a share of overhead. If volume is weak, each added provider raises cash pressure before it raises profit. The owner’s take-home improves only when revenue per visit stays above labor cost per visit and the schedule stays full enough to absorb payroll.
Track Pay Against Booked Hours
Watch revenue per therapist hour, booked sessions, and payroll as a share of revenue. Add staff only when forecasted visits can cover their pay plus room, supplies, and marketing. If the lead therapist or staff therapists sit underbooked, margins shrink before the owner sees any draw.
Use a hiring gate: only expand when each new role has enough paid sessions to fund its wage and overhead load. That keeps labor from getting ahead of demand and protects cash flow. In this model, the fix is not more headcount; it is enough booked work per provider to make the added payroll earn back its cost.
Client Retention And Referrals
Client Retention and Referrals
When clients rebook and refer, weekly sessions stay fuller without leaning so hard on paid ads. In this model, marketing and referral spend is 80% of revenue in year one and 60% by year five, so weak retention eats margin fast and lowers owner take-home. Better rebooking also supports the jump from 46 to 144 weekly sessions.
Here’s the quick math: more repeat visits and referrals raise revenue quality, but they also cut cash pressure because less of each dollar gets spent to replace lost clients. What this hides is simple: if clients do not come back, fixed costs and payroll still land, and the owner has to buy more demand just to stand still.
Measure Rebooking, Not Hope
Track rebook rate, referral count, and weekly sessions by provider. Test reminder workflows, post-visit rebooking, and clear treatment plans so the next visit gets booked before the client leaves. Keep the message clinical and honest: explain the plan, but make no outcome guarantees.
Use a simple dashboard: sessions booked, repeat-client share, referral share, and marketing spend as a percent of revenue. If repeat clients slip, owner pay gets squeezed because the business has to spend more to refill the calendar. If referrals rise, the clinic can grow volume with less paid acquisition and better cash flow.
Track weekly rebook rate
Measure referral source mix
Watch marketing as % revenue
Overhead And Reserve Discipline
Overhead and Reserve Discipline
$6,250 a month in fixed operating costs, or $75,000 a year, is the floor before owner pay. Safe take-home starts only after overhead, reserves, and reinvestment are covered. The model’s Month 14 breakeven and Month 41 payback show why cash can lag profit, especially after $61,500 of startup capex.
By year five, EBITDA reaches $283,000, but that does not mean all of it should be paid out. If debt service, cash reserves, or growth spending come first, distributions should wait. This is a cash rule, not a profit rule: the owner’s draw depends on what remains after fixed costs, reserve funding, and reinvestment needs.
Protect owner pay with a cash rule
Track monthly fixed costs, reserve transfers, and planned reinvestment before setting any owner draw. If fixed spend stays at $6,250 a month, every extra dollar of waste comes straight out of pay. Keep a simple monthly cash forecast so you know whether EBITDA is real cash or just paper profit.
Review overhead every month.
Set a reserve before distributions.
Delay draws when cash is tight.
Fund growth before extra pay.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.