How Much VA Claim Assistance Owners Make: $1661M EBITDA
VA Disability Claim Assistance Bundle
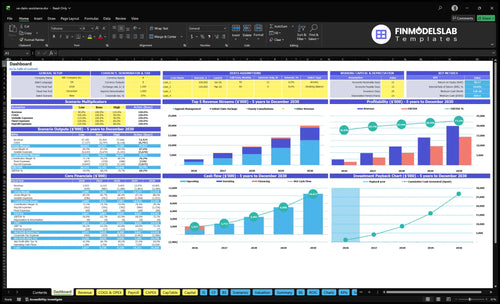
A VA disability claim assistance owner can’t treat revenue as take-home pay In this researched scenario, the business generates $2925M in Year 1 revenue and $1661M in EBITDA, a 568% EBITDA margin before taxes, reserves, and distributions The model includes a $115,000 Lead Claims Consultant salary, so owner income may include salary plus any approved distributions if the owner holds that role By Year 5, revenue reaches $19905M and EBITDA reaches $14361M, but those are scenario outputs, not guaranteed earnings
Owner income$1.78MNet margin56.8% → 72.1%Revenue for target pay$2.93MBusiness difficultyMedium
Want the six income drivers?
1
Lead Flow
$45K
A $45K Year 1 budget at $150 CAC decides how many veterans enter the pipeline and whether revenue reaches the $2.925M plan.
2
Client Close
2.8h
Each active customer averages 2.8 billable hours a month in Year 1, so better consult close rates lift revenue without adding as much headcount.
3
Appeals Mix
45%
Appeals rise to 45% of the mix by Year 5, and that shift pushes more billed hours and fee value into the owner's pocket.
4
Case Throughput
20h
Appeals take 20 to 25 billable hours, so faster file turnaround lets the same team carry more cases before capacity hits.
5
Labor Efficiency
56.8%
With $313K of Year 1 payroll and a $45K marketing budget, margin discipline decides how much revenue turns into owner cash.
6
Cash Buffer
$834K
The model needs $834K minimum cash and only breaks even in Month 3, so tight reinvestment protects equity early on.
Want to test your owner pay?
Owner income calculator
Estimate owner take-home and the target-pay gap from revenue, margin, costs, reserves, and your pay goal.
!
Planning note: This is a researched planning estimate, not guaranteed salary, tax advice, or owner distribution advice. Cash collected is not profit, and profit is not take-home.
Can you check owner income in the financial model?
What costs reduce VA disability claim assistance profit margin?
The biggest profit-margin hits in VA Disability Claim Assistance are labor, case-level direct costs, and marketing; see What Are Operating Costs For VA Disability Claim Assistance? for the cost map. In Year 1, direct case costs equal 150% of revenue and variable expenses equal 120%, so pricing has to cover a lot before profit shows up. The biggest swing comes from labor efficiency, paid case mix, and CAC moving from $150 to $130.
Main cost drivers
Medical examiner nexus fees raise case cost.
Records retrieval adds direct spend.
Secure CRM and portal fees stack up.
Referral commissions cut take-home margin.
Overhead pressure
Marketing rises from $45,000 to $140,000.
Wages are $313,000 in Year 1.
Wages reach $889,000 by Year 5.
Fixed overhead is $67,800 per year.
How does a VA disability claim assistance business make money?
VA Disability Claim Assistance makes money by billing veterans for claim package support, appeals management, and hourly consultations, with cash tied to billable hours and case resolution timing; track the operating drivers in What Are The Five KPIs For VA Disability Claim Assistance Business?. Here’s the quick math: 120 × $125 = $15,000, 200 × $150 = $30,000, and 20 × $100 = $2,000 by service type.
Revenue streams
Bill claim packages at $125/hour
Bill appeals management at $150/hour
Bill consultations at $100/hour
Model sample revenue at $47,000
Cash risks
Track active cases separately from cash
Watch resolved matters versus receipts
Appeals mix rises to 450% by Year 5
Rules and accreditation affect charges
How many VA claim clients do you need to make a living?
You can’t size VA Disability Claim Assistance by lead count alone; you size it by collected revenue per paid matter after direct costs. Here’s the quick math: Year 1 direct costs are 150% and variable fees are 120%, so 730% remains before marketing, payroll, fixed costs, taxes, and reserves; fixed overhead is $5,650/month, payroll is $313,000, and marketing is $45,000. If the owner also fills the Lead Claims Consultant seat, the salary benchmark is $115,000.
What sets the client count
Use collected revenue, not leads.
Count paid matters, then subtract costs.
Direct costs hit 150%.
Variable fees hit 120%.
Year 1 cost load
Fixed overhead is $5,650/month.
Payroll totals $313,000.
Marketing budget is $45,000.
Owner pay benchmark is $115,000.
Key Takeaways
Qualified leads matter more than raw lead volume.
Better intake lifts revenue without adding payroll.
Case mix shifts revenue per paid matter.
Cash reserves protect owner pay during collection delays.
Compare low, base, and high VA claim assistance owner income scenarios
Owner income scenarios
Income swings with lead flow, conversion, case mix, staffing, and cash timing. Base tracks the modeled first-year run rate; high reflects Year 5 scale and tighter CAC.
Three owner income cases for planning cash, staffing, and reserves.
Scenario
Low CaseDownside case
Base CaseModeled case
High CaseUpside case
Launch model
Lower earnings path with slower lead flow, weaker close rates, and more cash tied up before collections land.
Modeled earnings path using the first-year run rate from the financial model.
Stronger earnings path with Year 5 scale, better CAC, and a larger case mix.
Typical setup
The shop stays small, depends on paid leads with CAC above the modeled $150, and carries a lean team while reserves stay higher.
This case uses $2.925M revenue, $1.661M EBITDA, 56.8% EBITDA margin, $45,000 marketing, $150 CAC, $313,000 payroll, and $5,650 monthly overhead.
This case reflects $19.905M revenue, $14.361M EBITDA, 72.1% EBITDA margin, $140,000 marketing, $130 CAC, and a bigger staff model.
Cost drivers
slower conversion
higher CAC
delayed collections
heavier reserves
lean staffing
modeled lead volume
$150 CAC
$45k marketing
$313k payroll
$5,650 overhead
Year 5 scale
lower CAC
higher revenue mix
larger staff
stronger margins
Owner income rangeBefore owner reserves
Lower 7-figure take-homeDownside band
Around $1.7M take-homeModeled band
Around $14.4M take-homeUpside band
Best fit
Use this to stress-test cash burn, intake delays, and a weak referral funnel.
Use this as the planning base for hiring, cash, and owner draws.
Use this to test upside capacity, hiring pace, and reserve discipline.
!
Planning note: Scenario ranges are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distributions.
VA Disability Claim Assistance Core Six Income Drivers
Qualified Lead Flow
Qualified Veteran Leads
Qualified lead flow is the top of the funnel: how many eligible veterans book and show for consults. Here’s the quick math: $45,000 / $150 CAC = 300 acquired clients from that channel in Year 1. More qualified leads fill consultation capacity and raise paid matters, but only if intake can screen fast and the team can handle the added review work.
The risk is cheap traffic that looks busy but does not sign. Low-quality leads still consume intake time, and that can push payroll up without adding revenue. By Year 5, marketing rises to $140,000 and CAC improves to $130, so the same spend buys more efficient growth if lead quality stays high.
Track Quality, Not Just Volume
Measure qualified leads, consultation show rate, and signed matter rate together. A lead only helps income if it is eligible, responds, and moves through evidence review. If intake hours rise faster than signed cases, the funnel is leaking and owner pay will not keep up with marketing spend.
Use compliant, trust-based acquisition and test which sources produce the best conversion at the lowest CAC. One clean metric is qualified leads per $1,000. When that improves, you get more consultations without the same payroll load, so margin and owner distributions improve.
Case Resolution Throughput
Case Resolution Throughput
Throughput is how many cases get reviewed, documented, filed, followed up, and resolved without quality slips. If one active customer moves from 28 billable hours a month in Year 1 to 35 in Year 5, that is a 25% lift in revenue work per case. It helps owner income only when the extra hours are collected, not trapped in rework.
The main leak is backlog. Missed follow-up, slow client replies, or weak evidence handling can stretch cycle time and delay cash. Clean case flow turns active files into collected revenue faster, which supports better gross margin, steadier cash flow, and a more reliable owner draw.
Tighten Case Flow
Track the few numbers that show whether cases are moving: open cases per manager, days to first follow-up, documents still missing, and billable hours per active customer. Here’s the quick test: if cases age while hours stay flat, you have a workflow problem, not a demand problem.
Set follow-up deadlines in writing.
Assign one owner per case.
Use secure records from day one.
Escalate stalled client responses fast.
Consultation-To-Client Conversion
Consultation-to-Client Conversion
This is the share of consultations that turn into paid matters. It covers intake screening, clear engagement terms, meaning what the client is hiring you for and when payment starts, and plain timing expectations. When the team filters for eligibility and documents the scope well, more consult time becomes collected revenue, and less time gets burned on non-fit cases against the $5,650 monthly fixed overhead.
Track lead-to-consultation rate, consultation-to-client rate, paid case rate, no-show rate, and intake hours per signed matter. The risk is pressure selling or weak notes. That can lift short-term closes but hurt trust and case quality. Better conversion raises revenue per marketing dollar and protects owner pay because the same overhead is spread across more signed work.
Improve the Close Rate
Use a simple intake script: check eligibility, explain the engagement, and state timing in plain words. If no-shows are high, tighten reminders and booking windows. If consults are not closing, review whether prospects were screened too loosely or the next step was unclear.
Count booked, attended, signed.
Log no-shows by source.
Measure hours per signed matter.
Document why prospects were declined.
A cleaner process reduces wasted case review time and keeps more of each marketing dollar tied to paid work. What this hides: if the team spends too long on weak leads, intake becomes a cost center, not a profit driver.
Labor And Marketing Efficiency
Labor and Marketing Efficiency
Labor and marketing efficiency is how much revenue is left after payroll, CAC, marketing, software, referrals, and fixed overhead. In Year 1, payroll is $313,000, marketing is $45,000, CAC is $150, and fixed overhead is $67,800, so weak conversion or heavy rework can wipe out owner pay fast. One clean rule: if revenue per client does not outrun labor, margin gets squeezed.
By Year 5, payroll rises to $889,000 and marketing to $140,000, while direct and variable percentages improve from 270% to 210%. That means efficiency matters more as volume grows. Protect quality and compliance costs, but cut idle intake time, poor-fit leads, and repeat work. If each case needs less cleanup, more cash can reach the owner.
Track Cost per Signed Case
Measure cost per signed case, intake hours per matter, and no-show rate. Here’s the quick math: CAC = marketing spend ÷ acquired customers, so a $150 CAC only works if the client’s billable hours cover payroll and overhead. Keep the team busy with qualified veterans, not broad traffic that never converts.
Cut rework before hiring more.
Filter leads before intake time.
Protect compliance and quality costs.
Watch the gap between payroll growth and billable output. If payroll climbs toward $889,000 by Year 5, the owner’s draw depends on tighter scheduling, fewer dead-end reviews, and faster handoff from intake to paid work. The goal is simple: keep revenue quality high enough that fixed overhead and labor don’t swallow the margin.
Cash Reserves And Owner Distributions
Cash Reserves Control Owner Pay
Cash flow, not EBITDA, decides when the owner can take money home. In this model, the business needs at least $834,000 cash in Month 2, reaches breakeven in Month 3, and pays back in Month 4, because claim work and collections can lag the work already done.
Reserves have to cover payroll, marketing, compliance, and case timing gaps. EBITDA is profit before interest, taxes, depreciation, and amortization, so it can look healthy while cash is still tight. If reserves run thin, owner distributions get delayed or cut, even when active cases are building.
Build a Reserve Floor Before Drawing Profit
Track monthly cash balance, days of cash on hand, collections lag, and owner draw coverage. The key inputs are active client volume, billable hours, payroll, marketing spend, compliance costs, and the timing of receipts. If collections slip behind workload, cash should stay in the business instead of moving to owner pay.
Hold cash through Month 2.
Test draws after breakeven.
Map payroll and fee timing.
Block draws below reserve floor.
Paid Case Mix And Collected Fee Value
Paid Case Mix Value
This driver is the blend of paid work across initial claim packages, appeals management, and hourly consultations. Using the stated hours and rates, a package is $1,500 (12 x $125), an appeal is $3,000 (20 x $150), and a consultation is $200 (2 x $100). Treat the mix as an assumption, not fee advice.
If Year 1 mix is 45%/30%/25% and Year 5 shifts to 35%/45%/20%, weighted revenue per paid matter rises from about $1,625 to $1,915, or 17.8%. Appeals lift collected value, but they also bring more review work and slower timing, so owner pay depends on cash collection speed as much as billable hours.
Track Mix by Matter Type
Measure three inputs every month: matter type share, hours billed per matter, and collected dollars per matter. A simple formula is (share x fee value) across the mix. That tells you whether the business is earning more because of better case mix or just more low-value consult volume.
Track paid matters by service type
Watch billed hours per case
Compare collected fee per matter
Flag slower appeal collections
Push more appeal work only if review time, staff capacity, and cash timing can hold. If appeals rise but unbilled admin time also rises, gross margin and owner draw can slip even when top-line revenue looks better.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.