Value Stream Mapping Owner Income: $155K Salary, $39K EBITDA
Value Stream Mapping Consulting Bundle
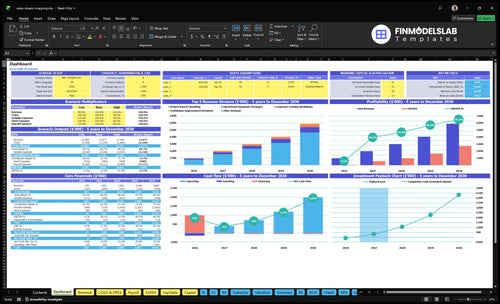
A value stream mapping consulting owner in this researched model has a planned principal salary of $155K, plus business profit capacity that starts at $39K EBITDA in Year 1 By Year 5, revenue reaches $5887M and EBITDA reaches $2725M, but that is not automatic take-home Owner take-home depends on billable hours, pricing, subcontractor use, travel, payroll, overhead, and reserves The business breaks even in Month 7 and reaches payback after 18 months, so early cash discipline matters
Owner income$194KNet margin4% to 46%Revenue for target pay$970KBusiness difficultyHard
Want to test your owner pay?
Owner income calculator
Estimate owner take-home and the target-pay gap from revenue, margin, costs, reserves, and target pay.
!
Planning note: This is a researched planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
What drives owner income most?
1
Project Pricing
$180-$250/hr
A $180-$250 hourly range in Year 1 sets the ceiling on each billable hour, so small rate gains lift income fast.
2
Billable Utilization
45 hrs/mo
At 45 billable hours per active customer each month, filling consultant time drives more revenue before you add headcount.
3
Project Mix
10%-50%
Moving toward more retainers and training raises repeat revenue and smooths cash through the year.
4
Delivery Leverage
29%
Year 1 delivery costs run about 29% of revenue, so every point cut in contractor, travel, or software spend lifts EBITDA.
5
Sales Pipeline
$45K
A $45K Year 1 marketing budget and $3.5K CAC set how fast the pipeline fills before breakeven in Month 7.
6
Overhead Reserves
$735K
With $8K fixed overhead a month, a $735K cash floor matters until payback hits in Month 7.
Want to see the full income model for Value Stream Mapping Consulting?
Can a value stream mapping consulting business scale beyond the owner?
Yes—Value Stream Mapping Consulting can scale beyond the owner, but only if new consultants do profitable billable work. In the model, senior consultants grow from 10 FTE in Year 1 to 50 FTE in Year 5, operations analysts from 10 to 30 FTE, revenue rises from $970K to $5887M, and EBITDA rises from $39K to $2725M.
Scaling works if utilization holds
Grow billable work, not headcount.
Move owner into sales and training.
Keep quality control tight.
Use account management to protect renewals.
Where margin risk shows up
Low utilization cuts leverage fast.
More staff can mean more overhead.
Senior consultants must stay profitable.
Operations analysts must support delivery.
How much can a value stream mapping consulting owner make?
Value Stream Mapping Consulting can support about $194K in Year 1 owner pay capacity before taxes and reserves: $155K principal salary plus $39K EBITDA on $970K revenue. By Year 5, the model reaches $5.887M revenue and $2.725M EBITDA with a larger team, but solo upside is capped by sales, prep, travel, and delivery time; track the drivers in What Are The 5 Core KPIs For Value Stream Mapping Consulting Business?.
Owner Pay
Year 1 revenue: $970K
EBITDA: $39K
Principal salary: $155K
Pay capacity: $194K
Scale Limits
Solo capacity hits time limits
Team scale adds payroll
Quality control becomes critical
Year 5 EBITDA: $2.725M
How much revenue does a value stream mapping consulting business need to pay the owner?
Value Stream Mapping Consulting needs about $970K in Year 1 revenue to support a $155K owner salary, and that still leaves only about $39K in EBITDA. The model also carries $440K in Year 1 payroll, $96K in fixed overhead, and variable plus delivery costs at 29% of revenue. If sales slip before Month 7 breakeven, owner distributions should wait.
Revenue build
$155K owner salary first
$440K Year 1 payroll
$96K fixed overhead
29% variable and delivery costs
Cash risk
$970K Year 1 revenue target
Only $39K EBITDA left
Wait on distributions before Month 7
Keep reserves until breakeven holds
Key Takeaways
Pricing discipline drives owner income more than volume.
Billable hours must rise, or fixed costs squeeze margin.
Retainers smooth cash flow, but hourly rates stay lower.
Pipeline and cash reserves protect breakeven and take-home pay.
Compare lean, base, and high owner income scenarios
Owner income scenarios
Owner income swings with scale because delivery load, contractor use, and recurring work change fast. Low, base, and high cases show how cash pressure eases as repeat work and CAC improve.
Compare founder pay pressure, scaled earnings, and mature upside.
Scenario
Low CaseLow Case
Base CaseBase Case
High CaseHigh Case
Launch model
This is the lean founder-pay case with thin cushion and heavy delivery work.
This is the scaled operating case with more team capacity and stronger repeat work.
This is the mature upside case with the strongest owner income path.
Typical setup
Year 1 runs at $970K revenue and $39K EBITDA, with $155K principal salary, 29% delivery and variable costs, and Month 7 breakeven after early cash strain.
Year 3 reaches $2.981M revenue and $993K EBITDA, with a larger consulting team, more recurring work, and a 33.3% EBITDA margin.
Year 5 reaches $5.887M revenue and $2.725M EBITDA, with a 50% retainer mix, lower CAC, and a 46.3% EBITDA margin.
Cost drivers
Principal consultant salary
contractor fees
travel and per diem
sales commissions
fixed overhead
Larger consulting team
recurring retainers
lower CAC
higher billable hours
steady project mix
Higher retainer mix
lower CAC
more billable hours
larger consulting team
steadier utilization
Owner income rangeBefore owner reserves
$155KFounder pay floor
$993KScaled earnings
$2.725MUpside case
Best fit
Use this to test first-year cash pressure and minimum owner pay.
Use this as the main planning case for staffing and cash.
Use this to test what happens if repeat work and pricing both hold.
!
Planning note: Scenario ranges are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distributions.
Value Stream Mapping Consulting Core Six Income Drivers
Project Pricing And Fee Structure
Scope-Based Pricing
Higher owner pay starts with pricing each service by scope and client complexity. This work includes current-state mapping, future-state design, diagnostics, implementation coaching, and training. In Year 1, rates are $225 for diagnostics, $200 for project consulting, $180 for retainers, and $250 for training per hour. By Year 5, those rise to $270, $245, $225, and $300.
Price too low and the owner gives away margin before any overhead is covered. Here’s the quick math: an 80-hour project at $200 per hour brings in $16,000 before costs. If the scope expands and the fee does not, owner income falls even when revenue looks busy. Outcome-based packages usually protect margin better than open-ended hourly work.
Price by Scope
Track service type, estimated hours, client complexity, and realized rate on every job. That shows which offers pay for prep, travel, admin, and follow-up, and which ones just fill time. If diagnostics or training consume more senior time than planned, the owner should reprice fast.
Use simple pricing rules: small scope, standard rate; complex scope, premium rate; open-ended work, fixed fee with clear deliverables. Build quotes around the inputs that move revenue quality: hours, workshops, revisions, and implementation support. One clean rule beats ad hoc discounts.
Map scope before quoting.
Separate diagnostics from consulting.
Charge more for complexity.
Use fixed fees for defined outcomes.
Review realized rate monthly.
Billable Utilization And Capacity
Billable Utilization
Billable utilization is the share of work time that earns client revenue. Here, active customers average 45 billable hours per month in Year 1 and 55 by Year 5; project work uses 80 billable hours per project in Year 1 and 90 by Year 5. At a fixed hourly rate, that 22% lift in client hours can flow straight into owner pay.
The catch is nonbillable time: sales, proposal writing, travel, prep, analysis, and admin. When utilization slips, fixed overhead and payroll stop flexing, so margin turns thin fast. One empty week can wipe out the cash from several billed days, especially if delivery staff are already on payroll.
Track Chargeable Hours Closely
Measure utilization by consultant, client, and project. Use billed hours / total available hours as the core ratio, plus active customers, hours per project, and nonbillable hours. If sales time rises but billed time does not, owner income will lag even when the pipeline looks busy. Keep the math visible every week.
Track billed hours each week.
Separate nonbillable work by type.
Flag projects above budgeted hours.
Review utilization by client monthly.
Set a floor for sold hours and cut low-value admin. If Year 1 stays near 45 hours per active customer, keep scope tight; if projects drift past 80 hours, reprice or reset scope. The goal is simple: keep enough chargeable time to cover payroll and fixed costs before owner draw.
Sales Pipeline Consistency
Sales Pipeline Consistency
Pipeline consistency is what keeps client work coming in, so billable hours stay full and owner pay doesn’t drop. In Year 1, marketing spend is $45K with $35K CAC; by Year 5 it rises to $110K marketing and $26K CAC. Likely buyers are manufacturers, operations teams, supply chain groups, and service-process teams. Empty weeks quickly turn fixed overhead into profit drag.
This driver includes leads, qualified meetings, proposal volume, close rate, and repeat work. A weak pipeline means fewer active clients, lower utilization, and less cash left after $8K per month of fixed overhead. Referral sales are modeled at 50% of revenue, so channel deals still need enough margin to leave room for delivery and owner draw.
Track CAC Before You Scale
Measure pipeline by source, stage, and CAC, then compare each source to realized billable hours. Here’s the quick check: if a source costs $35K to win a client, it needs enough hours and rate to earn that back fast enough to cover fixed costs and still pay the owner. Track booked meetings, win rate, and months of work per client.
Test direct outreach, referrals, and partner channels separately. Keep referral fees in the model at 50%, and only use them when the remaining margin beats direct acquisition. If lead flow slips, shorten proposal turnaround and follow-up time, because the fastest way to protect income is to keep billable weeks full.
Associates And Subcontractor Leverage
Associates And Subcontractor Leverage
In Year 1, contractor fees are 120% of revenue, so subcontracted delivery destroys margin before overhead. By Year 5, fees fall to 100%, which only gets you to zero on that labor; profit still depends on billable utilization, tight scope, and low rework.
As senior consultants grow from 10 FTE to 50 FTE, owner income rises only if those hours stay billable and use the same mapping method. If staff spend time on handoffs, fixes, or idle gaps, payroll and management time eat the cash that should fund owner pay.
Keep Billable Time Above Payroll
Track billed hours per associate, contractor fees as a share of revenue, and owner time spent selling versus managing. More staff only helps when each added hour is sold at the same mapping standard; otherwise, capacity grows faster than profit.
Use one playbook for current-state maps, future-state maps, and workshop delivery. Watch for rework, inconsistent workshop quality, and scheduling gaps, because those hidden costs turn leverage into overhead and cut the owner’s draw.
Set billable targets by role
Review rework every week
Protect owner sales time
Standardize the mapping method
Project Mix And Recurring Work
Recurring Work Mix
Income improves when one-off mapping turns into implementation support, kaizen coaching, training, and multi-site work. In Year 1, the model mix is 40% operational diagnostics, 60% project consulting, 10% retainers, and 15% training. Training carries the highest Year 1 rate at $250/hour, while retainers usually price lower but help smooth cash flow.
What this estimate hides is client timing and scope depth. If the mix shifts toward recurring work, owner income gets steadier because monthly billings are less tied to new project wins. The key inputs are client count, billable hours, service mix, and how much work is repeat versus one-off. More recurring work usually means less cash churn and better room to pay the owner.
Track Repeat Work Share
Measure revenue by service line every month: diagnostics, project consulting, retainers, and training. Here’s the quick math: if retainers rise, cash flow gets smoother even if hourly pricing is lower, because work stays in place longer and the sales gap shrinks. That matters when fixed costs keep running.
Watch three numbers: repeat-client hours, retainer share, and training hours. If one-off mapping keeps ending at the report stage, income stays spiky. If implementation support and kaizen coaching become the next step, the same client can buy more hours across more months, which usually supports steadier owner pay.
Track mix by service line.
Log repeat-client hours monthly.
Price training separately.
Push mapping into implementation.
Renew retainers before projects end.
Overhead, Reserves, And Cash Discipline
Cash Discipline
This driver includes the $8K per month fixed base for rent, insurance, SaaS, legal and accounting, utilities, and content subscriptions. Add Year 1 capex for laptops, furniture, equipment, video tech, software development, network setup, website, and training materials. Every dollar tied up here is a dollar the owner cannot take home, even when sales look strong.
The model needs $735K minimum cash and reaches breakeven in Month 7. That reserve is working capital, not profit or owner compensation. If overhead runs above plan or reserve cash is funded too early, the business can show revenue and still leave the owner with little or no draw.
Track Burn and Reserve Coverage
Use a 13-week cash forecast and track cash burn, or the net cash spent each month. Watch fixed overhead, reserve months on hand, and the timing of capex and client collections. If the cash gap widens, protect the buffer before increasing owner pay.
Rent, insurance, SaaS
Legal, accounting, utilities
Payroll and marketing
Capex timing and totals
Reserve balance versus burn
Keep reserve cash separate from operating cash. A strong month does not mean more draw if a software build, equipment buy, or slow client payment is about to hit. The clean rule is simple: if cash coverage is thin, delay spend before you delay pay.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.