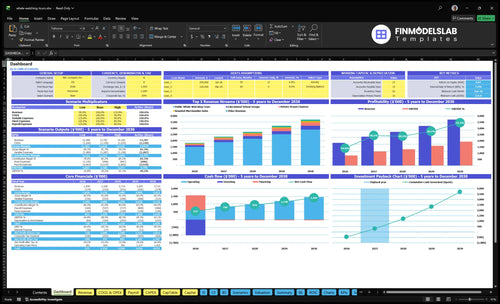
How Much Do Whale Watching Tour Owners Make? $821K Year 1 EBITDA
Whale Watching Tours Bundle
You’re pricing a seasonal boat business where revenue is large, but cash can disappear into fuel, crew, insurance, dockage, and vessel reserves In the researched five-year model, whale watching tour revenue grows from $183 million in Year 1 to $371 million in Year 5, with EBITDA from $821,000 to $193 million These are planning assumptions, not guaranteed salary, tax advice, or location-specific licensing guidance
Owner income$821k–$1.93MNet margin45%–52%Revenue for target pay$1.83MBusiness difficultyHard
Want to test your whale watching owner pay?
Owner income calculator
Estimate owner take-home and the target-pay gap from revenue, margin, costs, reserves, and target pay.
!
Planning note: This is a researched planning estimate, not guaranteed salary, tax advice, or owner distribution advice. Actual owner income depends on demand, margins, payroll, taxes, debt, and how much cash you keep in the business.
Want the six drivers that move owner income most?
1
Load Factor
$1.5M
12,000 public guests at $125 each create about $1.5M in Year 1, so every extra filled seat lifts income with little added overhead.
2
Ticket Pricing
$2.5K
Private charters at $2,500 each move revenue fast, and the 40 Year 1 bookings add about $100K before extras.
3
Trip Count
20K
Public tours grow from 12,000 guests in Year 1 to 20,000 in Year 5, so more sailings set the ceiling on revenue.
4
Fixed Costs
$199K
Docking, insurance, rent, permits, software, and maintenance total $199.2K a year, so this cash drag hits profit before any upside shows up.
5
Crew Model
$384K
Year 1 wages run about $384K, and captain, biologist, and crew hours shape both margin and how many trips you can run.
6
Channel Mix
7.5%
Booking commissions at 5.0% plus 2.5% ad spend take 7.5% of booking value, so more direct sales protect net booking margin.
Want to see how owner income is built in Whale Watching Tours?
How much can a whale watching tour owner make in a season?
A Whale Watching Tours owner can make as little as the modeled $95,000 general manager salary in a season if cash stays in the business, or participate in modeled EBITDA, profit before interest, taxes, depreciation, and amortization, of $821,000 in Year 1; see How Increase Whale Watching Tours Profits? for the operating levers. By Year 5, the model shows $371 million revenue and $193 million EBITDA, but owner pay depends on cash needs, not headline profit.
Season income drivers
Track viable operating days
Price sold seats clearly
Protect charter revenue
Plan for weather cancellations
Owner cash reality
$183 million Year 1 revenue
$821,000 Year 1 EBITDA
$95,000 manager salary
Reserve cash for debt and taxes
What affects whale watching tour profit margin?
Whale Watching Tours margins get squeezed fast when variable trip costs and fixed vessel overhead both stay high. Fuel at 80% of revenue, booking commissions at 50%, merchandise and food inventory at 45%, and marketing at 25% leave little room; for the planning side, see How To Write A Business Plan For Whale Watching Tours?. Fixed monthly costs add $16,600 before payroll, and payroll is $384,000 in Year 1 and $757,000 by Year 5, so cancellations still burn cash.
Variable costs
Fuel runs at 80% of revenue
Booking commissions take 50%
Food and merch inventory use 45%
Marketing still takes 25%
Fixed overhead
Dockage costs $4,500 monthly
Insurance costs $3,200 monthly
Rent, permits, system total $3,900
Maintenance reserve adds $5,000
How many whale watching trips are needed to pay the owner?
For Whale Watching Tours, pay the owner from contribution margin, not ticket sales alone. Using the provided numbers, the business needs about $729,000 in revenue to cover $199,200 of fixed costs, $289,000 of non-owner payroll, and a $95,000 owner salary. The trip count depends on average revenue per departure, capacity, and load factor, so the real driver is revenue per boat load.
Owner pay math
$199,200 fixed costs
$289,000 non-owner payroll
$95,000 owner salary
$729,000 revenue target
Trip count drivers
Use contribution margin first
Multiply by average departure revenue
Factor in boat capacity
Adjust for load factor
Key Takeaways
Seats sold matter more than fixed vessel costs.
Pricing and private charters lift margin fast.
More trips per season set the revenue ceiling.
Labor, fuel, and commissions can swallow cash.
Low, base, and high owner income scenario objective
Owner income scenarios
Owner income moves with guest volume, ticket price, charter mix, and add-on sales. Fuel, crew, and marina costs still shape how much EBITDA reaches the owner.
Compare launch, core, and upside income paths.
Scenario
Low CaseDownside
Base CaseCore
High CaseUpside
Launch model
Year 1 is the lower-income case, with the first operating year still ramping.
Year 3 is the modeled middle case, with steadier demand and better pricing.
Year 5 is the stronger earnings path, with volume, pricing, and add-ons all higher.
Typical setup
Year 1 runs at $1.83 million revenue and $821,000 EBITDA, with 12,000 public guests, 40 private charters, and a $125 base ticket.
Year 3 reaches $2.719 million revenue and $1.313 million EBITDA, with 16,000 public guests, 70 private charters, and a $135 ticket.
Year 5 reaches $3.710 million revenue and $1.933 million EBITDA, with 20,000 public guests, 100 private charters, and a $145 ticket.
Cost drivers
Public tour volume
charter count
ticket price
add-on sales
fuel and staffing
Guest volume
charter mix
ticket pricing
merchandise and food sales
crew and marina costs
Peak guest volume
charter demand
higher ticket price
add-on sales
crew and maintenance load
Owner income rangeBefore owner reserves
$821,000Year 1 case
$1.313MCore case
$1.933MYear 5 upside
Best fit
Use this to stress test early ramp, lighter charter demand, and slower add-on sales.
Use this as the main operating plan for a scaled but still realistic year.
Use this to test what happens if the route, pricing, and add-on mix all outperform plan.
!
Planning note: These scenario ranges are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distributions.
Whale Watching Tours Core Six Income Drivers
Passenger Load Factor
Passenger Load Factor
This driver is the share of seats sold on each trip, measured as seats sold ÷ available seats. Because the vessel, crew, and departure are already paid for, a fuller boat lifts revenue and owner profit faster than it lifts costs. The model uses 12,000 public guests in Year 1 and 20,000 in Year 5, so the key question is how many seats you actually fill, not just how many trips you run.
The upside is strongest in peak season, when weather, daylight, and demand support fuller departures. Still, extra passengers can bring booking fees, inventory cost, service labor, and refund exposure, so higher load factor helps most when those added costs stay small. One clean seat sold can be pure margin if the boat was going anyway.
Track Seats Sold, Not Just Trips
Track load factor by trip, season, and departure time, then compare it to the added cost per guest. Use seats sold ÷ available seats as the core metric, and watch which sailings stay full in peak months versus shoulder months. That tells you where owner cash improves fastest and where pricing or scheduling needs work.
Measure fill rate by departure.
Separate peak and off-peak trips.
Watch fees, labor, and refunds.
Prioritize fuller, higher-margin sailings.
Ticket Pricing And Private Charters
Ticket Mix and Charter Pricing
This driver is the mix of public tickets, private charters, and school group tickets. Year 1 pricing is $125, $2,500, and $65; by Year 5 it rises to $145, $2,900, and $75. To estimate it, use booked guests, charter count, and average price after discounts. One charter equals 20 public tickets at Year 1 pricing, so mix changes move revenue fast.
Here’s the quick math: 40 charters at $2,500 add $100,000 in Year 1, and 100 charters at $2,900 add $290,000 in Year 5. When demand holds, price changes flow quickly to margin. What this hides: child pricing, group discounts, trip length, vessel comfort, and local competition can limit how far you can push fare increases.
Track Charter Yield Closely
Track yield by customer type: public, charter, and school. Keep a weekly view of booked charters, average selling price, and discount rate. If charters fill with little discounting, that is the cleanest path to owner pay because the trip is sold at a premium before it leaves the dock.
Test price changes in small steps, not all at once. If group demand softens, protect volume with school pricing and limited discounts, but keep charter rates tied to trip length and vessel comfort. If charter bookings stall while public seats hold, margin may improve less than forecast even with higher posted prices.
Staffing Model
Staffing Model
The staffing model sets both owner pay and how much work the owner still has to do. Year 1 payroll is $384,000: $95,000 general manager, $85,000 licensed captain, $65,000 lead marine biologist, two deckhands at $42,000 each, and $55,000 sales coordinator.
By Year 5, payroll rises to $757,000. An owner can swap in their own labor as captain or manager and turn salary into owner income, but the business still needs qualified crew, safety coverage, and enough schedule depth to keep trips running without gaps. One missing licensed role can hit cash flow fast.
Track Crew Depth, Not Just Headcount
Model staffing by role, not by total staff. The key inputs are licensed captain coverage, marine biologist coverage, deckhand backup, sales support, and whether the owner is working as captain or manager. That tells you if payroll is really $384,000 in Year 1 or if extra coverage pushes it higher.
Track payroll by role each month.
Map every departure to crew coverage.
Test owner-as-captain or manager savings.
Here’s the quick math: every added salary lowers the cash left for owner draw, so staffing should match trip volume and safety rules. If schedule depth is thin, overtime and backup labor can erase margin. If the owner fills a licensed role, the pay moves from wage cost to owner income, but the workload rises with it.
Trips Per Season
Trips Per Season
Trips per season is the number of revenue-producing departures you can actually run in a year. It sets the ceiling before pricing matters. With demand growing from 12,000 public guests, 40 charters, and 2,000 school guests in Year 1 to 20,000, 100, and 4,000 in Year 5, fewer operating days or cancellations can cap income even if ticket sales are strong.
What this hides is simple: weather, whale migration timing, daylight, maintenance downtime, permits, crew availability, and school calendar demand can all cut departures. If trips fall, revenue drops fast, but dockage, insurance, and payroll still keep running, so owner pay gets squeezed first.
Track departures, not just bookings
Build the forecast from operating days and departures per day, then compare planned trips to actual trips each month. One clean metric: completed departures ÷ scheduled departures. If weather or maintenance pushes that ratio down, you lose revenue capacity and cash flow before pricing can help.
Protect the season by mapping peak whale windows, school dates, and crew coverage early. Keep a cancellation log by cause, because a small loss in trip count can wipe out a lot of margin when fixed costs stay put. More trips only help if they are sellable and fully staffed.
Vessel Costs
Vessel Costs
Vessel costs are the cash drag on this tour model. Launch capex totals $1,027,000 for the vessel, customization, safety gear, education tech, camera equipment, office systems, and the retail system. After launch, fixed vessel costs run $12,700 per month before fuel, so owner pay only comes from what is left after those bills and labor.
The big swing factor is fuel. It equals 80% of Year 1 revenue and still 60% by Year 5, so strong sales do not always mean strong cash. Reserves are a planning need, not leftover cash. If the boat does not keep cash set aside for fuel, dockage, insurance, and maintenance, the owner’s draw gets squeezed fast.
Track Fuel Burn Before Owner Draw
Measure fuel as a percent of revenue by trip and by season. Here’s the quick math: $4,500 dockage + $3,200 insurance + $5,000 maintenance reserve = $12,700 monthly, or $152,400 a year, before fuel. That tells you the minimum cash base the boat needs before the owner takes money out.
Track fuel per departure, revenue per trip, and reserve deposits weekly. If fuel stays near 80% of Year 1 revenue, pricing and scheduling must leave enough gross margin to cover the vessel and still pay the owner. Keep a separate reserve account so maintenance and downtime do not eat operating cash.
Split fuel by trip type.
Fund reserves every month.
Review cash before owner draws.
Marketing Channel Mix
Channel Mix and Net Cash
Gross bookings are ticket dollars before fees, so they are not the same as net revenue. In Year 1, 50% agency commissions plus 25% marketing and digital ads can consume 75% of revenue before fuel, crew, and dock costs. That’s why channel mix has a direct line to owner pay.
By Year 5, commissions drop to 40% while marketing stays at 25%, so the business keeps more cash from each booking. Direct bookings, strong reviews, and repeatable local referrals improve predictability and reduce discounts, refunds, and partner cuts.
Track Source Mix Weekly
Measure bookings by channel, commission rate, ad spend, and refund rate. Here’s the quick math: gross bookings less channel fees and marketing equals the cash left to cover vessel costs and owner income. If direct bookings rise, more of each ticket stays in the business.
Push post-trip reviews, hotel referrals, and local repeat guests. Compare every promo against net cash, not just seats sold. A channel that fills the boat but takes 50% of the sale can still weaken profit if it also drives discounts or refunds.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.