

Revenue and Monthly Calculations
Edit scheduled team hours, utilization, five service shares, and yearly billing rates on Revenue. Calc applies the January 31, 2026 launch timing and builds detailed monthly sales by service.


The Architectural Firm Financial Model is an Excel financial model for planning an independent US architecture studio. It converts scheduled professional hours, billable utilization, service mix, and realized hourly rates into a monthly revenue forecast and five-year operating projections for 2026–2030.
The illustrated studio has one principal architect, a growing design team, and fractional administrative support. All operating assumptions and forecast amounts are editable planning estimates, not historical results, national industry averages, or promises of performance.
The workbook connects architectural service capacity with staffing, costs, investment requirements, and financial reporting.
Edit scheduled team hours, utilization, five service shares, and yearly billing rates on Revenue. Calc applies the January 31, 2026 launch timing and builds detailed monthly sales by service.
Plan technical consultants, surveys, non-reimbursed travel, software, premises, insurance, and marketing. Payroll adds role-specific headcount, salaries, hiring dates, and monthly personnel expense schedules.
CAPEX schedules equipment purchases and depreciation; CapTable and Debt record owner capital and financing facilities. Dashboard includes working-capital settings, Low/Base/High multipliers, and financing controls.
Use the income statement, cash flow, balance sheet, scenarios, break-even and returns, valuation, charts, and combined Summary reports. Checks and Contents support reconciliation and navigation.
Revenue is calculated from one shared pool of professional hours, then allocated across five architectural services.
Scheduled team capacity rises from 480 hours per month in 2026 to 960 in 2030, while estimated billable utilization increases from 55% to 70%. The model sells only the resulting utilized hours, so the five services never independently consume the same capacity twice.
The five offerings are schematic design (15%), design development (30%), construction documents (30%), construction administration (20%), and feasibility and code studies (5%). Each service receives its allocated professional hours multiplied by that year’s realized hourly price.
The Revenue Forecast translates scheduled architectural hours, utilization, service mix, and annual hourly fees into revenue by service. Use it to test whether additional delivery capacity or a revised project mix supports the studio’s sales target.
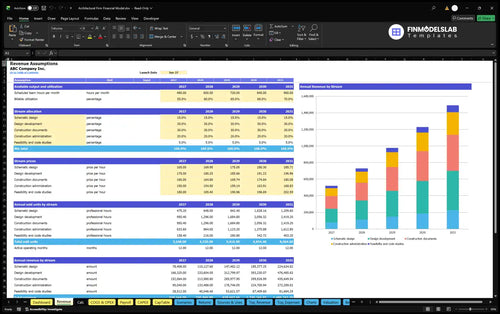
480 scheduled hours/month × 55% utilization = 264 billable hours/month; 264 × $164.25 weighted hourly fee × 12 months = $520,344 annual revenue.
For 2026, realized hourly prices range from $150 for construction administration to $180 for feasibility and code studies. These are selected model assumptions, not verified market tariffs; updating a price or mix changes the revenue projection without changing the underlying hour pool.
COGS, revenue-linked expenses, fixed overhead, and salaried staff are modeled separately to show their effect on EBITDA.
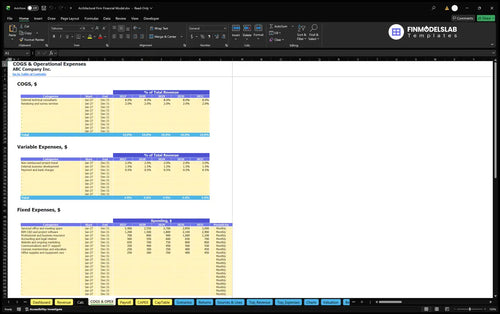
External technical consultants are estimated at 8% of revenue and rendering or survey services at 2%, forming the direct-cost budget. Non-reimbursed project travel, outside business development, and payment charges add another 4% of revenue as variable operating expenses.
The COGS and Operating Expenses report organizes external consultants, rendering, project travel, office space, insurance, BIM/CAD software, and other recurring costs. Expense assumptions flow into the monthly operating calculations and help explain changing contribution and EBITDA margins.
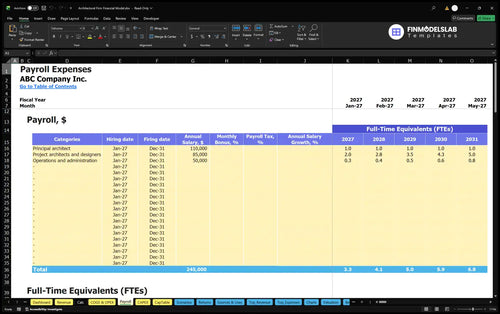
The principal architect has an annual base salary of $110,000. Project architects and designers rise from 2 to 5 annual-average FTE at $85,000 per FTE, with operations support increasing from 0.25 to 0.75 FTE at $50,000 per FTE.
The Payroll Forecast schedules architect, designer, and administration FTE, salary assumptions, and personnel costs by role. In the illustrative case, modeled payroll increases from $292,500 in 2026 to $572,500 in 2030 as delivery capacity expands.
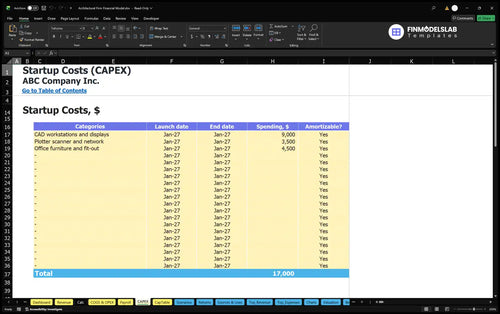
Startup assets and initial cash requirements are financing decisions, not additional annual EBITDA expenses.
The launch plan includes $9,000 of CAD workstations and displays, $3,500 for a plotter, scanner, and network, and $4,500 for furniture and fit-out. These $17,000 of planned assets are tracked separately from formation costs, website setup, office deposits, and preopening outreach.
The Capital Expenditure Plan records equipment purchases, acquisition timing, and depreciation schedules. It helps distinguish initial workstations and plotting equipment from recurring software, facilities, and personnel expenses when reviewing the firm’s investment and subsequent financial statements.
The example uses 30 accounts-receivable days, zero payable days, and zero inventory days. Estimated initial owner funding is $179,205, calculated from qualifying opening needs and a three-month recurring-expense reserve, with no confirmed outside borrowing in the case.
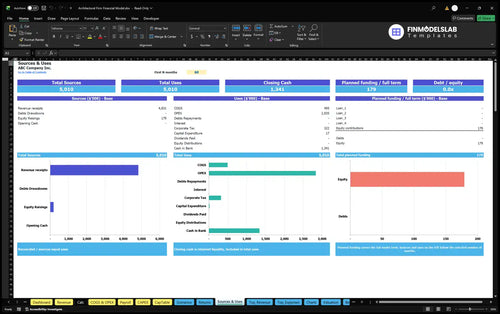
The Sources and Uses of Funds report compares cash entering the business through operations, equity, and debt with spending and retained cash. It is useful for evaluating owner contributions, equipment requirements, and potential changes to the opening funding plan.
The illustrative planning case projects revenue, modeled operating expenses, and EBITDA for each year from 2026 through 2030.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $520,344 | $440,948 | $79,396 |
| 2027 | $730,847 | $550,019 | $180,828 |
| 2028 | $978,608 | $664,305 | $314,303 |
| 2029 | $1,230,245 | $779,134 | $451,111 |
| 2030 | $1,490,743 | $895,204 | $595,539 |
Planning estimates rounded to whole dollars; rounding may create small differences between displayed totals.
The example’s revenue rises from $520,344 in 2026 to $1,490,743 in 2030 as scheduled hours, billable utilization, and hourly prices increase. The corresponding operating expenses include direct costs, variable expenses, fixed overhead, and payroll, increasing from $440,948 to $895,204.
Illustrative EBITDA increases from $79,396 to $595,539 over the five years. EBITDA measures operating earnings before interest, tax, depreciation, and amortization; it is not the same as net profit, free cash flow, available cash, or owner distributions.
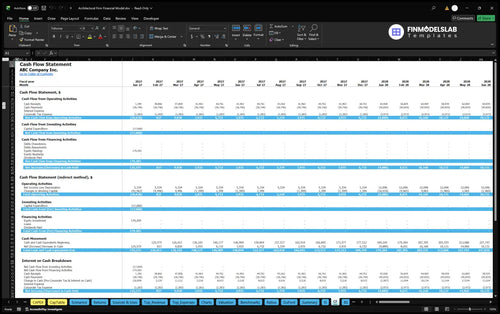
The Cash Flow Forecast traces cash receipts, operating payments, investment expenditures, owner contributions, and financing movements through monthly cash balances. Review it separately from EBITDA to examine receivable timing, equipment spending, liquidity, and potential funding pressure.
The workbook also contains income statement, balance sheet, ratios, charts, and combined reporting views. These reports describe additional financial measures, but the supplied numerical case only establishes the annual operating forecast through EBITDA; no net profit or cash balance is assumed here.
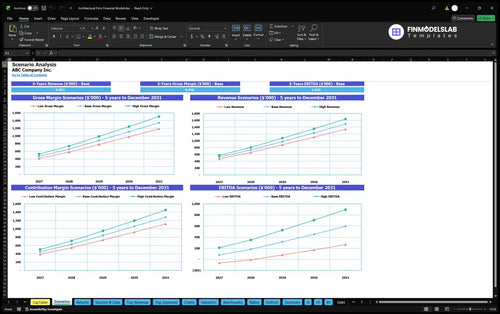
The Financial Scenario Analysis compares Low, Base, and High settings for revenue, direct costs, variable spending, fixed costs, and payroll. Adjust the Dashboard multipliers to see how revenue and expense changes can alter projected operating profitability.
Return analyses ask different questions about operating coverage, cash recovery, and invested capital.
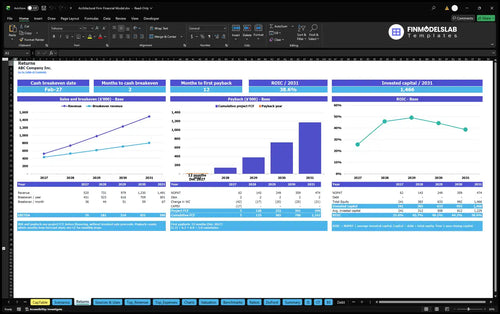
Sales break-even estimates revenue required to cover operating costs under the selected assumptions. Cash break-even instead considers the timing of cash inflows and outflows; investment payback tracks cumulative project cash recovery, while annual ROIC relates operating returns to invested capital.
The Break-Even, Payback and ROIC report combines modeled sales break-even, cash break-even timing, cumulative project cash flow, and annual invested-capital return measures. It helps evaluate whether a proposed architectural practice can sustain its cost base and ultimately recover initial investment.
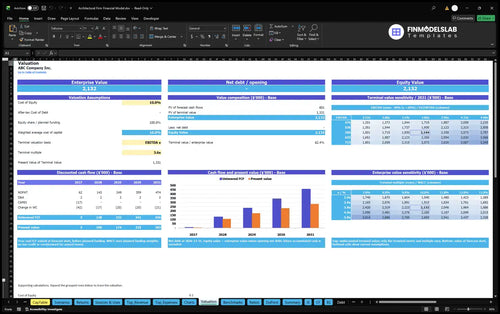
The Valuation report offers discounted cash flow and terminal-value sensitivity, while Benchmarks compares modeled margins with values entered by the user. Neither a specific payback date nor a valuation, ROIC, or IRR result is documented for this case, so none is implied.
The Business Valuation Analysis estimates enterprise and equity values using projected unlevered free cash flow, a discount rate, and terminal assumptions. Its sensitivity view supports comparisons of valuation assumptions rather than treating the illustrative EBITDA forecast as a verified company valuation.
This Excel template is designed for independent architects, new firm founders, and advisers evaluating an hourly-fee design practice.
Test whether more scheduled hours require additional architects, whether improved utilization offsets rising salaries, and how the mix of design phases changes realized revenue per hour. Then inspect operating margins, funding needs, cash flow, and scenario comparisons before making staffing or investment decisions.
Answers to common questions about capacity-based revenue, editable assumptions, reports, and financial planning.
One pool of scheduled monthly team hours is multiplied by billable utilization, split across five service categories, then multiplied by the respective realized hourly rates.
Yes. Revenue inputs include annual utilization, available team hours, service mix, and realized fees for each of the five service categories.
Yes. The Payroll worksheet supports FTE planning, annual base salary, hiring timing, and monthly personnel expense by role.
Yes. The workbook includes monthly income statement, cash flow, and balance sheet reports; this specific case brief supplies numerical projections only through EBITDA.
Yes. Dashboard controls and the Scenarios report compare Low, Base, and High assumptions for revenue and operating cost categories.
No. EBITDA excludes investing and financing cash movements; review the separate Returns and Cash Flow reports for cash break-even and investment payback analysis.
No. The hourly prices and financial projections are editable estimates for an illustrative US architectural studio, not observed national averages.
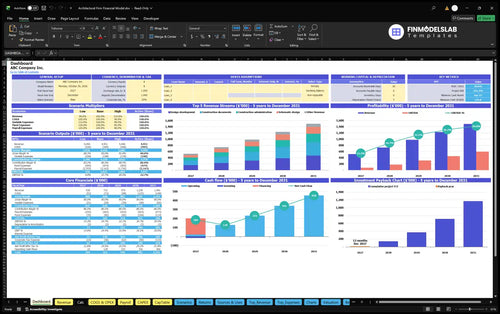
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
DCF valuation and sensitivity analysis.
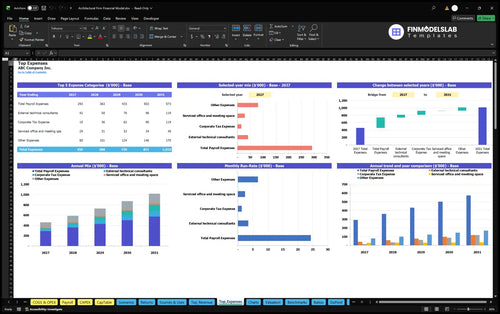
Largest costs and spending trends.
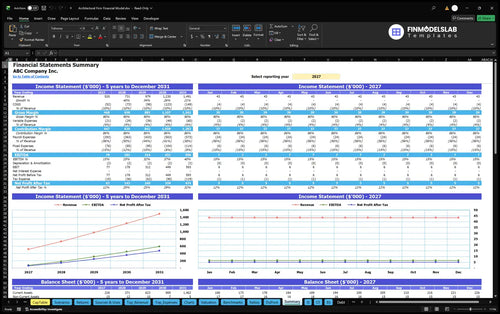
Annual and monthly financial performance.
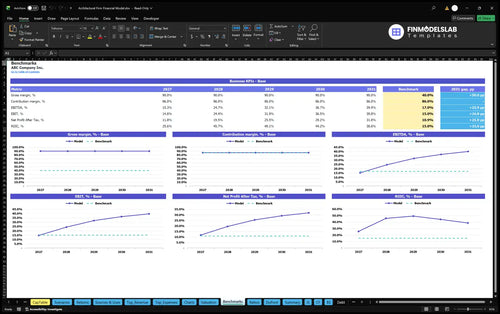
Compare margins and returns to benchmarks.

I stopped chasing charts across half a dozen files. Now the statements and visuals live in one place, and I can send a clean update in under an hour.

The template made it much easier to trust the numbers. When I changed one assumption, I could see the effect right away without worrying that a broken cell would throw off the whole model.
Building the financials by hand was eating my evenings. This template turned that into a short setup session, and I had a usable forecast ready the same day.