

Revenue and Calc
Set baked items available per day, operating days, utilization, monthly seasonality, category shares, and realized menu prices. The Calc sheet converts these inputs into monthly item volumes and revenue by category.


The Bakery Financial Model is an Excel planning template for an independent neighborhood retail bakery with on-site production and a staffed sales counter. It links daily baking capacity, the mix of products sold, menu prices, operating expenses, and staffing to monthly financial projections and annual reports.
The illustrative U.S. bakery opens January 31, 2026, and covers 2026 through 2030. It uses one shared baked-item capacity pool, not separate demand forecasts for each product, and its figures are editable planning assumptions rather than observed business results.
The workbook connects bakery-specific planning inputs to operating calculations, financial statements, funding schedules, and decision-oriented reports.
Set baked items available per day, operating days, utilization, monthly seasonality, category shares, and realized menu prices. The Calc sheet converts these inputs into monthly item volumes and revenue by category.
Separate ingredients and packaging from payment fees, marketing, recurring overhead, and fixed salaries. Plan bakers, production assistants, counter staff, and the owner-manager by annual-average FTE.
Record bakery equipment, leasehold improvements, equity contributions, and any financing entries. The Debt schedules are available, although the documented example assumes initial owner funding with no new debt.
Bakery sales are driven by one daily item-capacity pool, operating days, sold-capacity utilization, monthly seasonality, product mix, and prices.
The example starts with 600 baked items available per day and 26 operating days per month. Utilization increases from 45% in 2026 to 75% in 2030, while monthly seasonal multipliers adjust the number of items sold.
Six categories share the same sales volume: artisan bread loaves 18%, croissants and danishes 25%, cookies and brownies 22%, muffins and scones 15%, cake slices 12%, and savory baked goods 8%. These shares total 100%, so no item is allocated twice.
The Revenue Forecast organizes bakery capacity, utilization, operating days, seasonal adjustments, category mix, and realized selling prices. Its monthly calculations feed annual revenue by product group, helping evaluate the effect of higher output or a different menu mix.
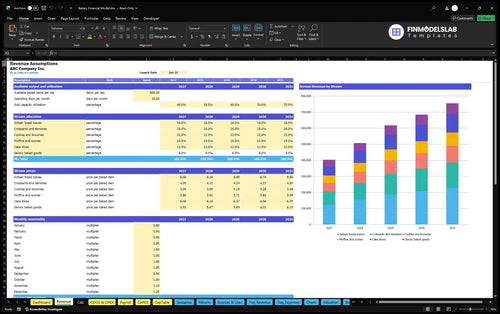
600 available items per day × 26 operating days × 45% sold capacity = 7,020 items per month before the seasonal multiplier.
In 2026, planned prices include $8 for an artisan loaf, $4 for a croissant or danish, $3 for a cookie or brownie, and $6 for a cake slice. Category volumes are multiplied by their respective prices, then combined into total bakery revenue.
The model classifies direct product costs, revenue-linked operating expenses, recurring fixed overhead, and payroll separately to calculate EBITDA.
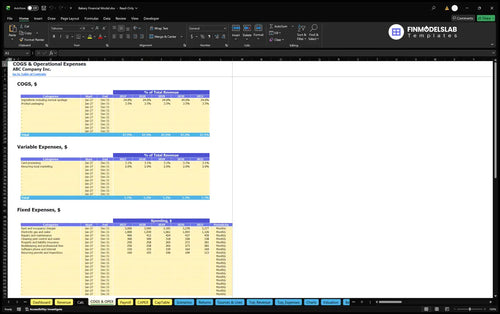
Ingredients including normal spoilage equal 24% of revenue, while packaging adds 3.5%. Card processing is modeled at 3.08% of sales and recurring local marketing at 2%; these percentage inputs move with the bakery revenue forecast.
Fixed costs cover rent, utilities, maintenance, cleaning, insurance, professional fees, software, communications, permits, and inspections. Example rent is $3,000 per month in 2026 and $3,377 per month in 2030, with 12 paid months in each year.
The COGS and Operating Expenses Forecast separates ingredient and packaging costs from sales-linked fees and fixed overhead. This breakdown helps identify which expenses rise automatically with sales and which require planned changes to monthly budgets.
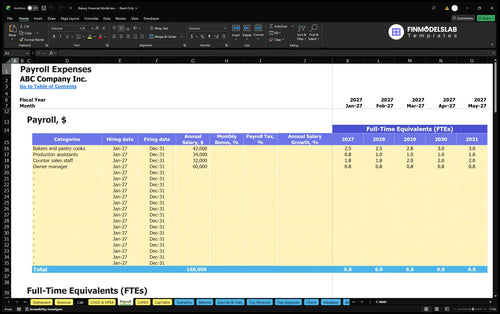
Payroll is counted only in the personnel schedule, not again within COGS or fixed overhead. In 2026 the plan uses 2.5 baker FTE, 0.75 production assistant FTE, 1.75 counter staff FTE, and 0.75 owner-manager FTE.
Annual base pay per FTE is $42,000 for bakers, $34,000 for production assistants, $32,000 for counter staff, and $60,000 for the owner-manager. The example excludes employer taxes and benefits under its stated scope.
The Payroll Forecast shows staffing by role, annual-average FTE plans, salary assumptions, and monthly personnel costs. It supports decisions about production coverage and counter staffing as sold-capacity utilization grows across the projection.
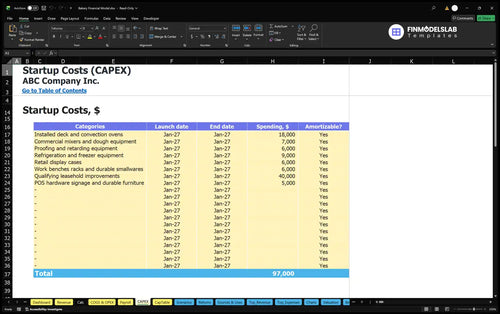
Startup assets, preopening cash payments, and owner funding are planned separately from ongoing operating expenses and EBITDA.
The case includes $18,000 for installed ovens, $7,000 for mixers and dough equipment, $6,000 for proofing equipment, and $9,000 for refrigeration. Additional investment categories include display cases, work benches, leasehold improvements, POS hardware, signage, and durable furniture.
Separate preopening cash items cover permits, website setup, launch marketing, refundable deposits, and staff preparation. The CAPEX schedule records the timing of capital purchases, while depreciation is tracked for applicable assets rather than deducted in the EBITDA example.
The Capital Expenditure Plan schedules ovens, mixers, refrigeration, furnishings, and other bakery investment items by purchase date. Its depreciation calculations support the financial statements while keeping equipment purchases distinct from recurring operating spending.
The illustrative opening owner contribution is $224,468. Its stated basis combines itemized equipment and other startup assets, separate opening cash requirements, physical working capital, and a three-month reserve for recurring costs; it is not an EBITDA or profit result.
Working-capital controls use zero accounts-receivable days, seven accounts-payable days, and ten inventory days. These assumptions help model collections, supplier payments, and inventory investment in the broader cash-flow and balance-sheet schedules.
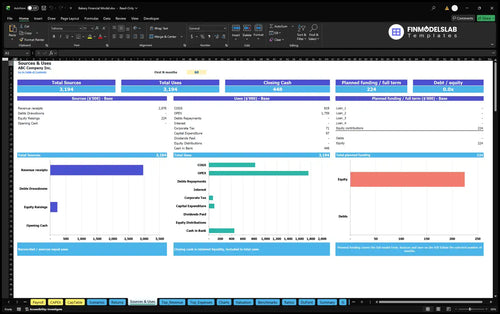
The Sources and Uses of Funds report organizes planned owner equity and any entered financing against operating, investing, and funding cash allocations. Use it to distinguish opening capital contributions from projected sales receipts and subsequent business expenditure.
In the documented illustrative operating case, annual revenue increases alongside sold-capacity utilization, and EBITDA moves from negative to positive.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $403,088 | $428,226 | −$25,138 |
| 2027 | $507,444 | $472,687 | $34,756 |
| 2028 | $617,697 | $529,128 | $88,568 |
| 2029 | $685,168 | $563,692 | $121,476 |
| 2030 | $756,132 | $588,956 | $167,176 |
Forecasts are illustrative, not historical results. Figures are rounded to the nearest whole dollar; displayed differences may vary slightly.
The 2026 operating forecast shows a $25,138 EBITDA loss on $403,088 of revenue, while 2030 shows $167,176 of EBITDA on $756,132 of revenue. These figures reflect the selected production, price, staffing, and spending assumptions; they do not establish net profit or cash availability.
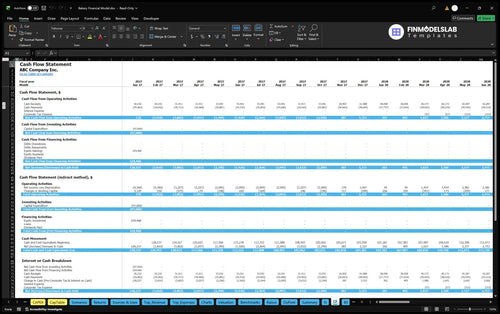
The Cash Flow Forecast tracks operating, investing, and financing cash movements, including equipment purchases and owner contributions. It helps assess liquidity and potential funding gaps that cannot be determined from the annual EBITDA figures alone.
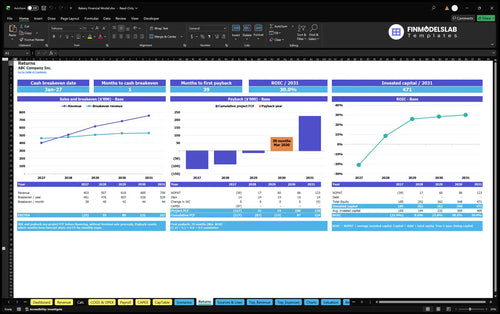
The workbook supports operating break-even, cash break-even, investment payback, and annual return analysis as different financial questions.
The Returns report compares revenue with the level needed to cover operating costs, examines cumulative project cash flow for investment recovery, and calculates return on invested capital. None of those results should be inferred directly from EBITDA.
Dashboard controls provide Low, Base, and High revenue and expense multipliers. Compare how a slower bakery ramp, higher ingredient costs, or additional staffing requirements could affect margins and the timing of economic recovery, without assuming an unreported payback period.
The Returns analysis brings together break-even requirements, project cash-flow payback, and annual ROIC. It helps compare the bakery’s operating cost coverage with the distinct question of when invested capital might be recovered.
This template fits bakery owners, prospective operators, and advisors assessing an on-site production format. Adjust the capacity, category prices, wage plan, site expenses, capital budget, and financing inputs to reflect the bakery actually being evaluated.
Answers to common questions about editing assumptions, understanding the projections, and using the supporting reports.
Yes. Edit the six product-category prices and their shares of the same sold-item capacity pool on the Revenue planning sheet.
It multiplies available items per day by operating days, utilization, and monthly seasonality, then applies product shares and prices to the resulting item volume.
Yes. Payroll plans baker, production assistant, counter staff, and owner-manager FTE and compensation separately from direct costs and fixed overhead.
Yes. Dashboard scenario controls compare Low, Base, and High assumptions for revenue and operating expense categories.
No. EBITDA excludes investing and financing cash movements; examine Cash Flow, the Balance Sheet, and working-capital assumptions to assess liquidity.
No. All figures are illustrative forecasts based on editable estimates, not actual industry performance or guaranteed investment outcomes.
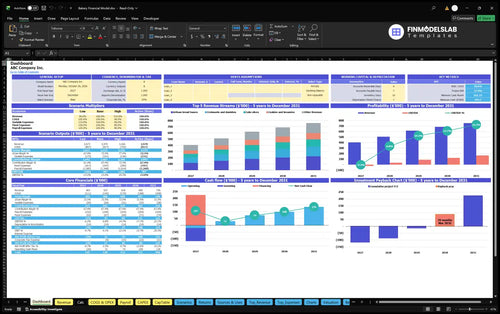
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
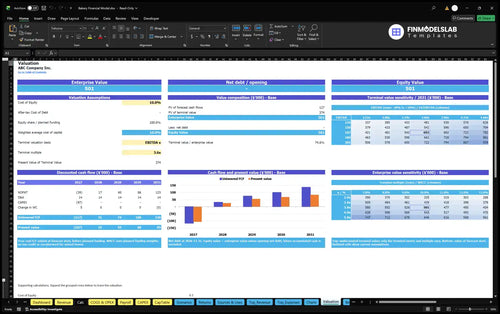
DCF valuation and sensitivity analysis.
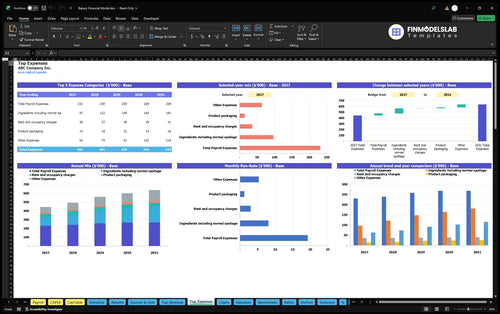
Largest costs and spending trends.
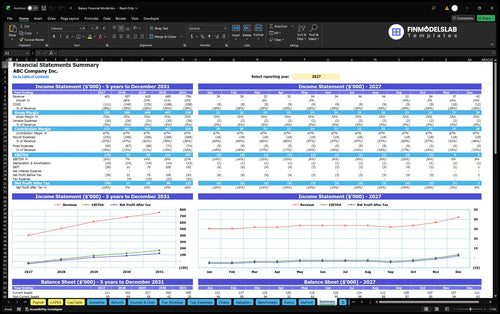
Annual and monthly financial performance.
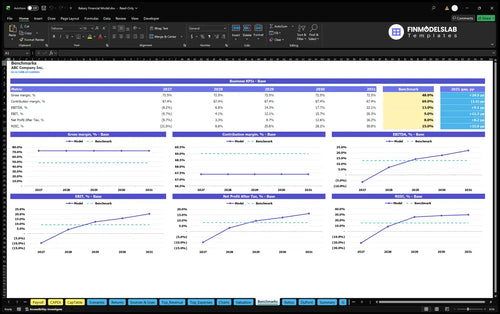
Compare margins and returns to benchmarks.

This template gave me a starting point when I had nothing mapped out, and that saved me a full day of guesswork. I could move from idea to draft forecast without feeling stuck.

I was tired of hunting through separate tabs and old exports for the numbers, so having the statements and charts in one place made a big difference. It cut my prep time for investor updates by about 3 hours.
I do not live in Excel, and this model still felt manageable from the first open. The layout made the advanced parts easier to follow, and I booked my lender call two days sooner than planned.