

Revenue + Calc
Set batch size, operating days, annual utilization, formulation mix, launch date and per-gallon selling prices. Monthly calculations allocate one finished-gallon pool across product lines.


This chemical manufacturing financial model forecasts revenue, costs, staffing, equipment and financial statements for a U.S. producer of water-based industrial cleaning liquids from 2026–2030.
The case models a leased 8,000-square-foot plant, two 500-gallon mixers and B2B drum/tote sales. It excludes chemical synthesis, pesticides, flammable solvents and consumer retail.
The Excel template links production capacity to financial statements, funding schedules and decision reports.
Set batch size, operating days, annual utilization, formulation mix, launch date and per-gallon selling prices. Monthly calculations allocate one finished-gallon pool across product lines.
Forecast raw materials, packaging, testing, freight, plant overhead and staffing separately, using cost rates, monthly fixed expenses, FTE and annual salaries.
Schedule asset purchases and depreciation, record owner equity and model optional debt drawdowns and repayments. The illustrative case funds opening needs entirely with owner contributions.
Review the projected income statement, cash flow statement and balance sheet, including receivables, inventory, payables, asset balances and financing movements.
Sales are calculated from one available monthly gallon pool, utilization, each formulation’s share and its annual net selling price.
Two 500-gallon mixer batches on each of 20 operating days create 20,000 available finished gallons per month. Utilization is 40% in 2026, 50% in 2027, 60% in 2028, 68% in 2029 and 75% in 2030.
Allocate finished gallons once: alkaline degreaser 30%, neutral floor cleaner 25%, glass cleaner 15%, acid descaler 15% and liquid detergent the remaining 15%. Each stream multiplies its gallons by its own annual net price.
The Revenue Forecast ties batch capacity and utilization to gallons sold by cleaning formulation and then to annual sales. Changing product mix or the per-gallon price changes the forecast without counting any gallon twice.
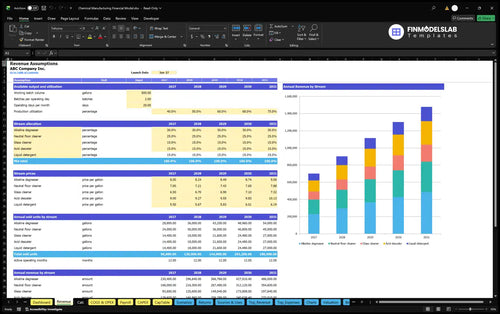
20,000 gallons/month × 40% utilization × 12 months × $7.30 weighted net price/gallon = $700,800 annual revenue.
The January 31, 2026 launch month counts in full; sales are zero beforehand. No monthly seasonality is assumed.
The model connects production sales to direct formulation and packaging costs, variable selling costs, monthly overhead and role-based personnel expense.
Direct COGS are set at 25% of sales for surfactants and inputs, 18% for drums, totes, labels and closures, and 2% for testing and waste. Freight, external commissions and payment losses add 7% of sales as variable operating expenses.
The COGS and Operating Expenses report organizes percentage-based production costs and sales-related costs separately from monthly plant overhead. It helps test whether higher gallon output can absorb rent, power, maintenance, insurance and compliance services.
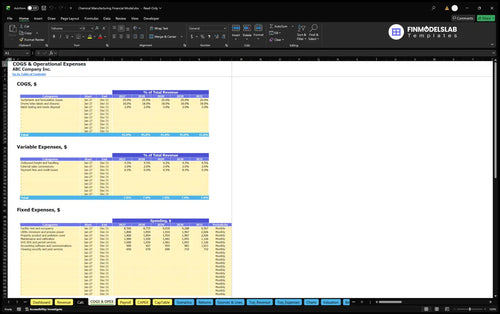
$700,800 revenue − $315,360 COGS − $49,056 variable expenses = $336,384 before fixed overhead and Payroll.
Base-case fixed costs are $187,800 in 2026 and $211,392 in 2030. Facility rent alone starts at $8,500 a month; utilities, insurance, maintenance, EHS services, administrative systems and site services are additional categories.
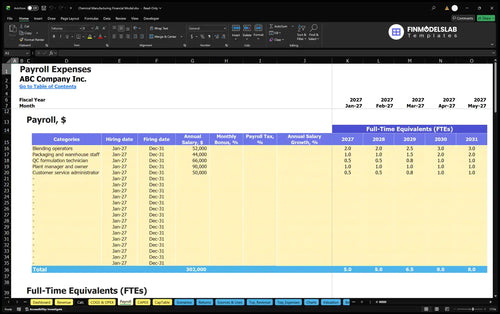
The Payroll Forecast organizes blending operators, packaging and warehouse personnel, QC, plant management and administration by FTE and base salary. Illustrative annual staffing increases from five to eight FTE, raising salary expense from $296,000 to $450,000.
Opening equipment, launch cash and working capital are separate funding uses; they are not deducted again as current-year operating expenses.
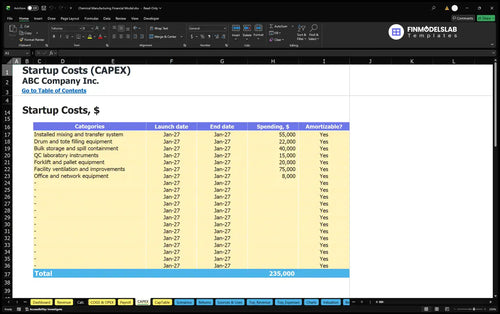
Initial durable plant assets total $235,000, including a $55,000 mixing and transfer system, $22,000 filling equipment, $40,000 bulk storage and containment, and $15,000 QC instruments. Other assets include handling equipment, ventilation improvements and office technology.
The Capital Expenditure Plan schedules equipment and installation spending by date and records depreciation separately. Use it to distinguish cash paid for durable mixing, filling and storage assets from the operating costs used to calculate EBITDA.
Opening uses also include $60,000 other cash, $57,638 starting net working capital and a $212,054 three-month reserve. Controls assume 24 receivable, 33 inventory and 20 payable days.
The Sources and Uses of Funds report reconciles modeled inflows, investing and operating outlays, and cash retained. The illustrative opening plan contributes $564,692 from owners only; available debt controls do not mean the base case includes a loan.
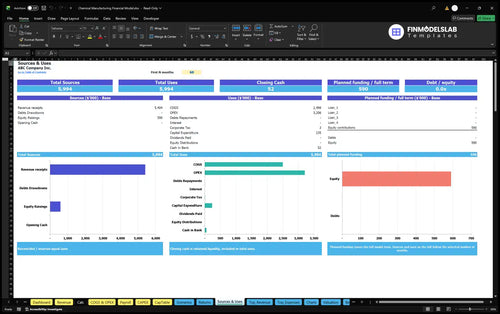
The illustrative base case grows revenue as production utilization rises, but fixed plant costs and payroll keep EBITDA negative until 2030.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $700,800 | $848,216 | −$147,416 |
| 2027 | $902,460 | $958,719 | −$56,259 |
| 2028 | $1,115,496 | $1,152,318 | −$36,822 |
| 2029 | $1,301,602 | $1,332,045 | −$30,443 |
| 2030 | $1,478,880 | $1,430,410 | $48,470 |
Forecasts are illustrative and rounded to whole USD; operating expenses include COGS, variable expenses, fixed expenses and payroll.
The case reaches $1,478,880 of revenue and $48,470 of EBITDA in 2030, after operating losses in each preceding forecast year. Higher mixer utilization increases sales, while expanded staffing and recurring site costs absorb much of that gain.
The Projected Income Statement carries revenue, direct costs, operating expenses and payroll into gross margin, contribution margin and EBITDA, then separately handles depreciation, financing costs and tax. The supplied case does not establish a net-profit forecast.
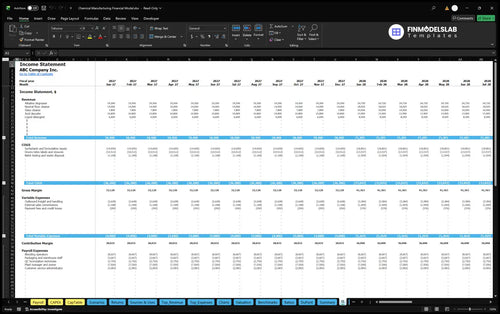
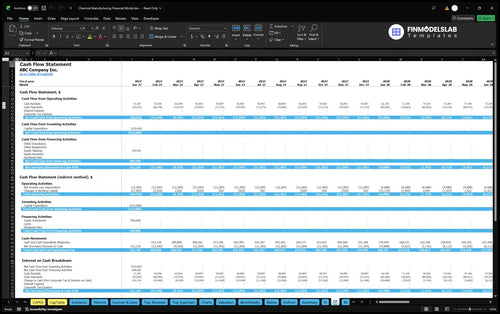
The projected balance sheet and working-capital schedules show how inventory, customer collections, supplier payments and investments affect liquidity despite improving annual operating results.
The Cash Flow Forecast separates operating, investing and financing cash movements and reconciles opening with closing cash. Use it to investigate liquidity as customers pay and inventory accumulates; EBITDA alone does not determine available cash.
Scenario controls and Returns reports let users evaluate different operating conditions without presenting unsupported payback or valuation figures as established results.
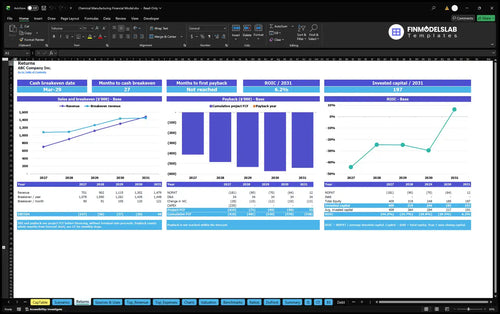
Sales break-even measures the revenue needed to cover operating costs; cash break-even tracks cumulative project cash flow. Investment payback considers recovery of invested funds, while annual ROIC measures return relative to invested capital.
The Returns, payback and ROIC analysis compares operating sales with break-even requirements and evaluates cumulative project cash flow and invested capital. These distinct measures should not be inferred from the positive 2030 EBITDA result.
The Dashboard supplies Low, Base and High multipliers for sales and each expense family. Test a slower utilization ramp, lower realized prices or higher material and personnel costs before relying on a given investment or financing plan.
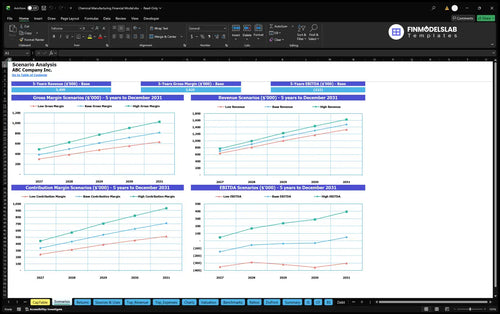
The Financial Scenario Analysis compares Low, Base and High revenue, gross margin, contribution margin and EBITDA. Its sensitivity helps identify whether gallon utilization, selling price, input costs or plant overhead is the main risk to operating performance.
Valuation, benchmarks, ratios and checks are available, but this case does not establish a valuation, payback date, ROIC or sufficient cash balance.
These answers clarify the modeled production case, editable drivers and how to interpret its financial outputs.
Two mixers, daily batches, operating days, utilization, one allocated pool of gallons and five net per-gallon selling prices drive monthly and annual sales.
Yes. Revenue inputs include annual utilization, formulation allocation and prices, with monthly Calc schedules applying the selected launch date.
No. The documented case records fixed base salaries in Payroll separately from the material, packaging, testing and waste inputs in COGS.
No. The 2030 illustrative EBITDA is $48,470 before depreciation, financing costs and taxes, and it does not establish net profit or cash sufficiency.
Yes. The standard workbook provides monthly cash flow and balance sheet reports, although the case-specific figures supplied here only support operating results through EBITDA.
No. Opening funding is modeled as $564,692 of owner equity; Debt controls are available for users who want to model external financing.
The Returns report supports sales break-even, cash break-even, investment payback and ROIC analysis, but the supplied case does not substantiate their specific outcomes.
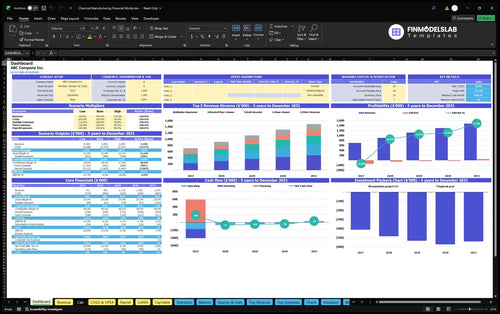
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
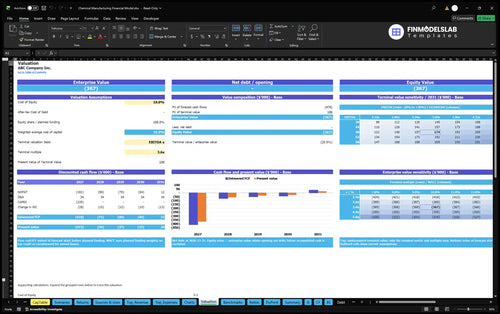
DCF valuation and sensitivity analysis.
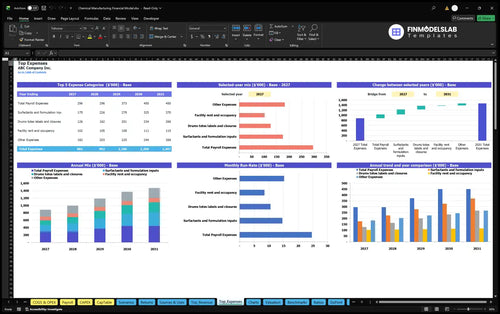
Largest costs and spending trends.
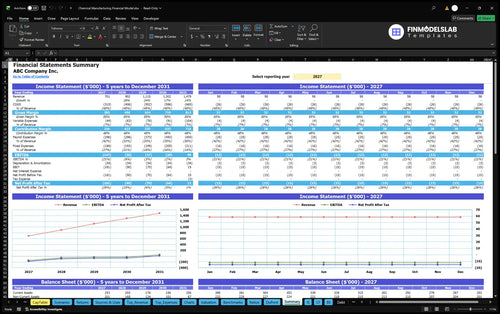
Annual and monthly financial performance.
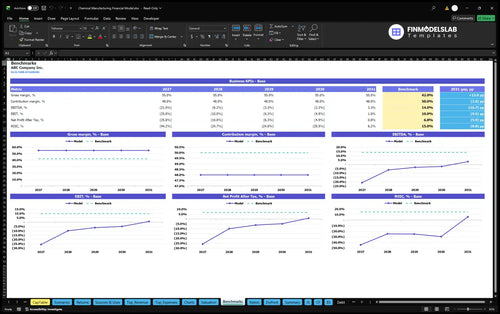
Compare margins and returns to benchmarks.

This template stopped the blank-sheet panic and gave me a place to start. I had a working forecast in one afternoon instead of staring at an empty workbook for days.
I used to have P&L, cash flow, and charts spread across different files. Now everything sits in one model, and I walked into our lender call with cleaner numbers and no scrambling.
Building the model by hand was eating up my week, but this cut the setup time fast. I finished the first pass in a few hours and got back to operations the same day.