

Revenue and Calc
Enter active projects, five work-type allocations, earned-work prices, and launch timing. Monthly calculations recognize progress revenue rather than full contract bookings.


The Construction Company Financial Model is an Excel template for US contractors handling residential renovations, home additions, and small commercial fit-outs. It links active projects and earned-work prices to revenue, job costs, staffing, and financial reports.
The illustrative 2026–2030 case launches January 31, 2026 and uses subcontracted trades alongside in-house supervision and carpentry. Results are documented through EBITDA, not actual performance or guaranteed results.
The workbook connects construction-specific operating assumptions with monthly schedules, financial statements, scenario controls, and management analysis.
Enter active projects, five work-type allocations, earned-work prices, and launch timing. Monthly calculations recognize progress revenue rather than full contract bookings.
Budget materials, subcontract packages, job costs, variable and fixed overhead, and employee FTE and salaries separately.
Schedule assets, owner contributions, and optional financing. Four Dashboard debt-control rows support repayment structures.
Review financial statements and the combined Summary. Dashboard controls cover scenario settings and working-capital inputs.
Compare Low, Base, and High cases, break-even, payback, ROIC, valuation sensitivity, and funding uses.
Revenue is average active project-months allocated once across five job types and multiplied by earned-work prices.
In the Base planning case, average active projects rise from 8 in 2026 to 12 in 2030. Each month allocates the same project pool across kitchen renovations (25%), bathroom renovations (25%), structural renovations (20%), home additions (20%), and commercial fit-outs (10%).
Prices represent work earned per project-month, not full contract value. In 2026, kitchens start at $18,000 per project-month and additions at $35,000, with separate annual price paths.
The Revenue Forecast combines active projects, work-type percentages, and yearly progress prices. Change job mix or active project volume to test recognized sales.
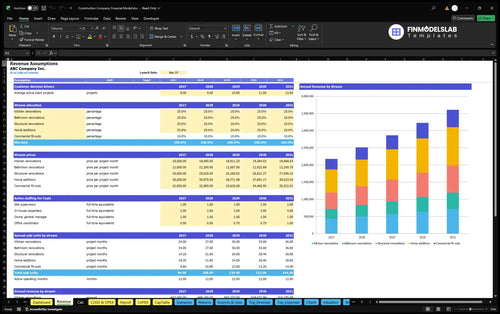
8 average active projects × 12 months × $22,700 blended earned revenue per project-month = $2,179,200 annual revenue.
The $22,700 blended price weights all five 2026 work types. Each project-month is allocated only once; no competing capacity forecast is implemented.
Operating expenses separate direct job costs, revenue-linked overhead, fixed expenses, and staff.
Direct costs total 64.5% of modeled revenue: materials 30%, specialist subcontract packages 30%, equipment rentals 2%, waste disposal 1.5%, and permits and inspections 1%. These costs scale with progress revenue and are distinct from the in-house employees on Payroll.
Variable costs add 3.8% of sales: marketing 2.5%, collections 0.3%, and callbacks 1%. Fixed costs cover premises, vehicles, insurance, software, upkeep, professional services, and licensing.
The COGS and Operating Expenses forecast separates direct construction costs from variable and fixed operating spending. Adjust the material and subcontract percentages or recurring office commitments to see their effect on gross margin, contribution, and EBITDA.
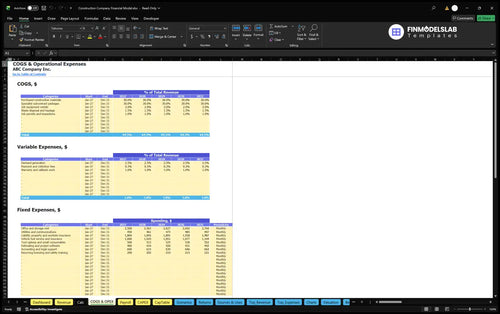
The 2026 case has $1,405,584 of COGS, $82,810 of variable costs, and $89,400 of fixed costs. Asset purchases and loan repayments are excluded from these operating charges.
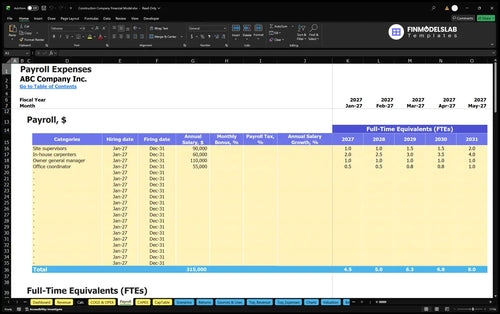
The Payroll Forecast plans supervisors, carpenters, an owner manager, and office support by FTE and salary. Carpenter FTE rises from 2 in 2026 to 4 in 2030 as active projects grow.
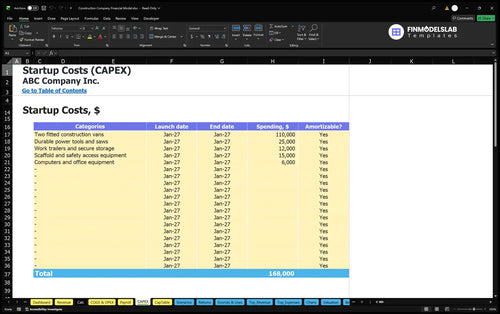
Equipment, preopening payments, working capital, and funding differ from recurring costs.
The case includes vans ($110,000), durable tools ($25,000), trailers ($12,000), and scaffolding ($15,000). Computers and office equipment are additional startup assets with no stated amount here.
Lease deposits, formation costs, launch promotion, and preopening labor are separate cash items, not recurring EBITDA charges.
The Capital Expenditure Plan schedules equipment spending and relevant depreciation. Distinguish upfront vans and tools from recurring job costs and overhead.
Working-capital controls use 17 accounts-receivable days, 10 accounts-payable days, and 5 inventory days. These assumptions help translate earned construction revenue and expenses into payment timing; they do not change what EBITDA means.
The Sources and Uses of Funds report compares funding sources with operating payments, investment, financing, and retained cash. Equity contributions are funding, not sales.
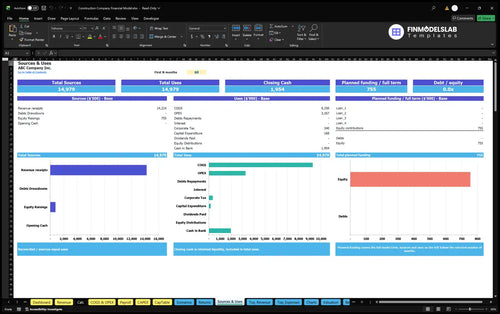
The $754,802 opening owner-funding estimate includes assets, prelaunch payments, working capital, and a three-month operating cash reserve. No external funding is confirmed; cash sufficiency is not established.
The illustrative 2026–2030 case forecasts growing revenue and positive EBITDA before depreciation, interest, and tax.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $2,179,200 | $1,925,294 | $253,906 |
| 2027 | $2,512,890 | $2,185,439 | $327,451 |
| 2028 | $2,861,903 | $2,514,855 | $347,047 |
| 2029 | $3,226,795 | $2,796,425 | $430,370 |
| 2030 | $3,608,143 | $3,148,043 | $460,100 |
Illustrative projections, not actual results. Amounts are rounded to whole dollars, so displayed differences can vary by $1.
Revenue rises with active projects and earned-work prices. EBITDA subtracts direct costs, variable costs, fixed costs, and Payroll: $253,906 in 2026 and $460,100 in 2030.
The Income Statement includes further accounting lines, but this example supports values only through EBITDA. Net profit and cash available to owners cannot be inferred.
The Cash Flow Forecast tracks operating, investing, and financing movements with a cash reconciliation. Compare construction receipts with supplier payments, equipment purchases, and funding instead of equating earned revenue with collected cash.
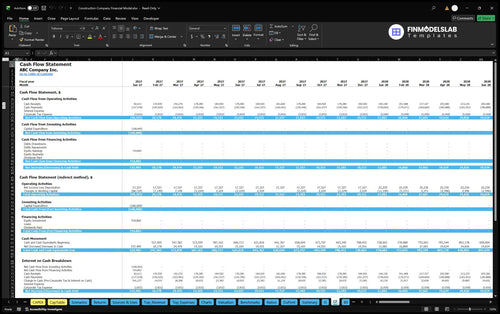
Construction billing and collections can fall in different months. The 17-day receivables setting and 10-day payables setting are therefore useful alongside the cash-flow and balance-sheet reports when evaluating working-capital pressure during expansion.
The Financial Scenario Analysis compares Low, Base, and High revenue, COGS, variable expense, fixed expense, and payroll multipliers. Use it to examine how a slower renovation pipeline or higher subcontract costs could change operating profitability without claiming a predicted outcome.
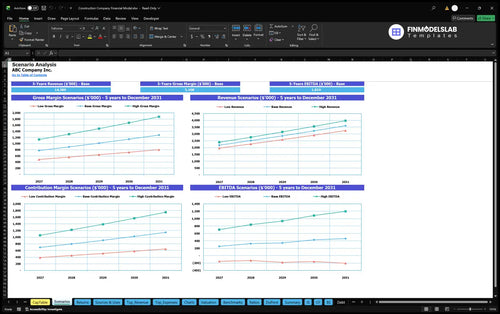
Returns and Valuation distinguish operating thresholds, cash recovery, capital efficiency, and valuation.
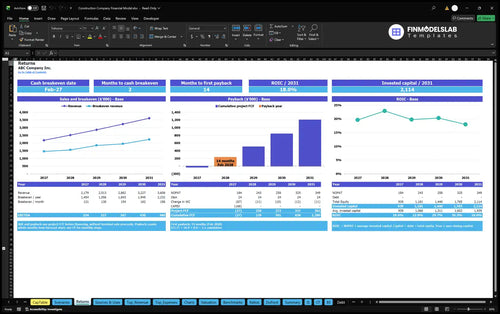
Sales break-even compares sales with the revenue needed to cover specified operating costs. Cash break-even measures cash recovery timing, while investment payback tracks recovery of invested funds and annual ROIC compares operating return with invested capital. These measures are not interchangeable.
The example provides funding and EBITDA figures, but no verified payback month, ROIC, IRR, or business valuation. Each requires separate cash-flow and financing assumptions.
The Returns report compares sales with break-even needs and analyzes cash recovery, payback, and annual ROIC. It separates investment performance from operating EBITDA.
The Valuation report uses discounted unlevered free cash flow and a terminal multiple with sensitivity analysis. Results from that framework should be reviewed as assumption-dependent estimates, not as a verified sale price for the illustrative construction business.
The template helps founders, owners, and advisers evaluate a small general contractor.
Test how active projects, work mix, and prices support staffing. Then examine subcontract costs, overhead, equipment spending, and collections before assessing growth or funding.
The example is a national US planning case, not a local quote. Substitute your own pipeline, job costs, salaries, collections, purchases, and financing terms.
Answers to common questions about how this general-contractor Excel model works and what its example results establish.
It allocates average active project-months across five work types, then multiplies each share by the corresponding monthly earned-work price. It does not recognize every signed contract in full immediately.
Yes. The Revenue inputs include active project assumptions, percentages for five job types, and annual prices per project-month.
No. Specialist subcontract packages are part of COGS; Payroll covers listed site supervisors, carpenters, the owner manager, and the office coordinator.
Yes. The workbook has Cash Flow and Balance Sheet reports, with working-capital and financing schedules. The supplied illustrative case only documents numerical operating results through EBITDA.
No. It is an estimated opening owner-funding figure for this example, based on selected assets, prelaunch uses, working capital, and an operating cash reserve.
No. EBITDA excludes capital purchases, financing flows, and working-capital timing; review the Cash Flow report and underlying assumptions to assess liquidity.
No. Returns and Valuation sheets support those analyses, but the provided figures do not establish a payback date, ROIC, IRR, or enterprise value.
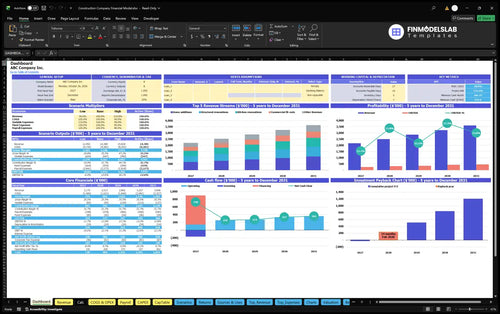
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
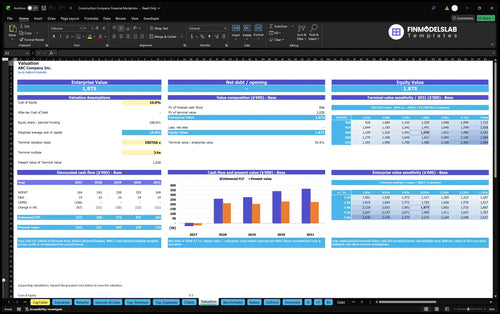
DCF valuation and sensitivity analysis.
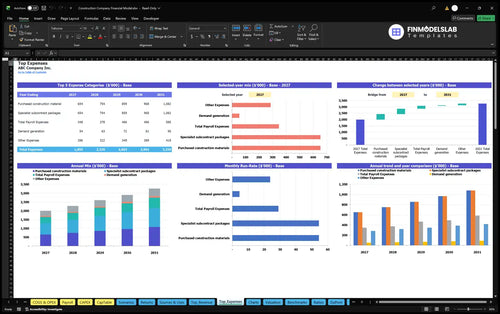
Largest costs and spending trends.
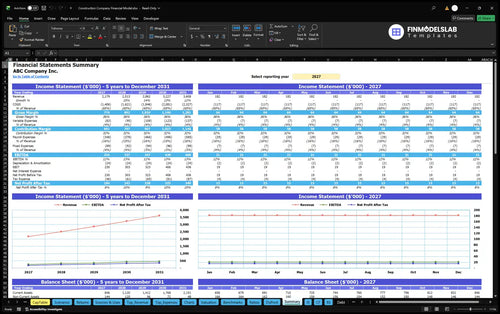
Annual and monthly financial performance.
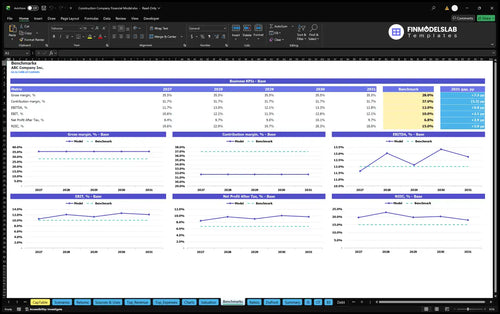
Compare margins and returns to benchmarks.

This template kept one bad cell from turning into a bigger mess, which saved me hours of rechecking formulas. I could trust the numbers and move on instead of hunting errors line by line.
I used to spend days building forecasts from scratch, but this model cut that down to an afternoon. The layout made it easy to start planning right away and saved me more than 20 hours on the first pass.
I wasn’t sure what lenders would expect, but this template gave me the right outputs and order to follow. It helped me put together a cleaner deck and book a meeting with our banker faster.