

Revenue and Calc
Set rentable units, serviceable days, utilization, seasonality, and daily-equivalent rates by equipment class; monthly calculations allocate one common pool of rented machine days.


This construction equipment rental financial model is an Excel planning template for forecasting machine-day rentals, operating expenses, startup investment, and financial performance. It connects fleet utilization, seasonality, and realized daily hire rates to monthly calculations and a five-year annual projection.
The illustrated case models an independent Charlotte, North Carolina, dry-hire yard with 20 owned machines across five equipment classes. It assumes a fixed fleet from 2026 through 2030, outsourced local delivery included in hire pricing, and no operated rentals, equipment sales, or re-rental revenue.
The workbook links equipment-specific assumptions with monthly calculations, operating costs, investment schedules, and financial reports.
Set rentable units, serviceable days, utilization, seasonality, and daily-equivalent rates by equipment class; monthly calculations allocate one common pool of rented machine days.
Plan repair materials, outside repairs, outsourced delivery, lead generation, yard overhead, and three staffing roles without duplicating their expenses.
Schedule fleet and facility investment and record owner equity contributions separately from annual equipment rental earnings.
Review selected-case metrics and compare Low, Base, and High revenue and cost multipliers alongside model setup and optional debt controls.
Use Income Statement, Cash Flow, Balance Sheet, Sources & Uses, Returns, Valuation, Checks, and charts to assess the outputs created by your inputs.
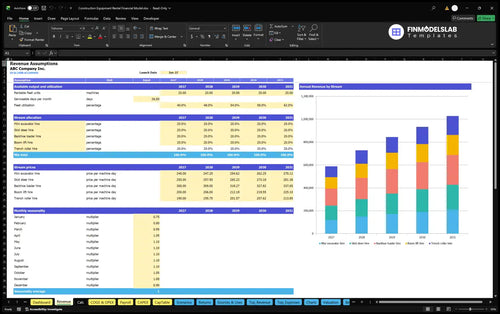
The model calculates rental sales from one shared capacity pool, allocated evenly among five equipment categories and priced at class-specific realized hire rates.
The 20-machine fleet provides 520 serviceable machine days per month at 26 available days per unit. Annual utilization rises from 40% in 2026 to 62% in 2030; January-to-December seasonal factors redistribute rentals across months without creating a second demand forecast.
Mini excavators, skid steers, backhoes, boom lifts, and trench rollers each receive 20% of available and rented days. The realized daily-equivalent hire rates already include local outsourced delivery and term discounts; refundable deposits and jobsite fuel are excluded.
The Revenue Forecast organizes fleet capacity, monthly utilization, seasonal adjustment, and realized machine-day rates for all five equipment classes. Its annual volume and revenue totals flow from the detailed Calc worksheet.
20 machines × 26 days per month × 40% utilization × $236 average daily-equivalent hire × 12 normalized months = $589,056.
The $236 rate is the equally weighted average of five 2026 class prices: $240, $250, $300, $200, and $190 per machine day. Since the twelve seasonality factors average 1.0, the illustrated capacity calculation reconciles to the annual revenue forecast.
Direct rental costs and variable selling expenses change with revenue, while recurring yard coverage and role-based salaries are modeled separately.
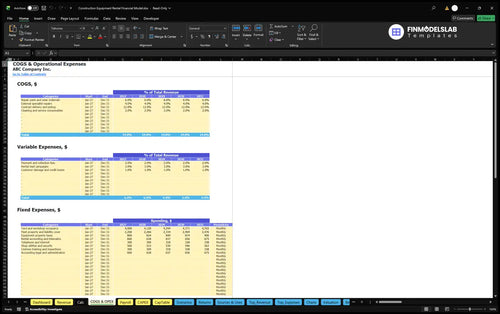
Direct costs include repair parts and wear materials at 6% of sales, external specialist repairs at 4%, delivery and pickup at 12%, and cleaning consumables at 2%. Additional variable costs total 6% of sales across collection fees, lead campaigns, and damage or credit losses.
Fixed categories cover workshop occupancy, insurance, equipment taxes, telematics, utilities, security, licensing, and administration. In 2026, the illustration assigns $141,373 to COGS, $35,343 to other variable expenses, and $111,600 to fixed overhead.
The COGS and Operating Expenses forecast separates revenue-linked maintenance and delivery costs from recurring yard overhead. Adjusting rates, effective dates, or fixed spending changes the operating expense and margin calculations.
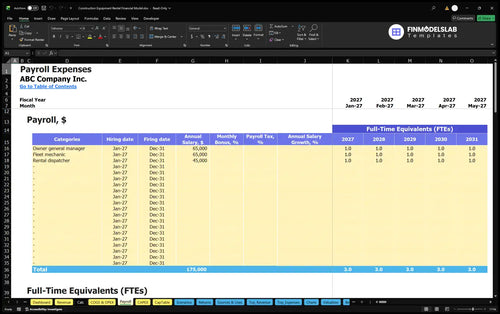
The staffing plan budgets one owner general manager, one fleet mechanic, and one rental dispatcher. Their annual base salaries of $65,000, $65,000, and $45,000 produce $175,000 of illustrated annual payroll before excluded employer taxes and benefits.
The Payroll Forecast tracks staffing by role, annual-average FTE, salary assumptions, and monthly personnel costs. In this case, the three positions are budgeted separately from direct rental costs to avoid counting compensation twice.
Startup capital covers owned equipment and setup cash, while working-capital assumptions and the reserve are distinct from recurring rental expenses.
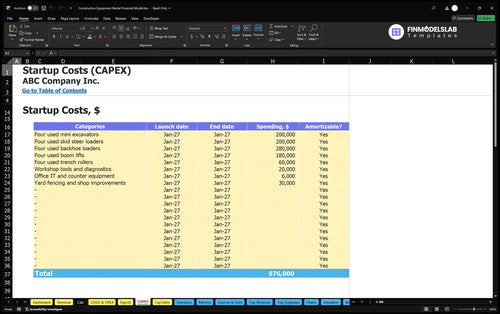
The illustrative asset budget is $976,000 for used equipment, shop tools, office technology, fencing, and improvements. It includes four each of mini excavators, skid steers, backhoes, boom lifts, and trench rollers, with no additional fleet expansion assumed during the forecast.
Separate opening cash totals $31,000 for deposits, permits, website and software setup, prelaunch marketing, and preparation. Working capital uses 21 receivable days, 10 payable days, and 10 inventory days as editable planning controls.
The Capital Expenditure Plan records fleet and facility asset purchases, spending timing, and depreciation schedules. It helps distinguish equipment investment from maintenance expenses and from the revenue those machines may earn.
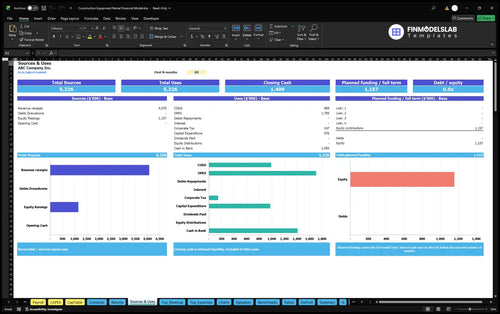
The selected opening funding is $1,156,720 of estimated owner equity: $976,000 in assets, $31,000 in setup cash, approximately $33,891 in launch net working capital, and $115,829 as a three-month reserve. The reserve is a policy assumption, not a verified peak cash requirement.
The Sources and Uses of Funds report organizes contributions, investment, operations, and retained cash across selected forecast months. It is useful for reviewing where owner capital is allocated and how any newly modeled debt would change funding flows.
The following annual amounts describe the supplied Charlotte rental-yard planning case, not observed performance or industry averages.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $589,056 | $463,317 | $125,739 |
| 2027 | $728,073 | $508,370 | $219,703 |
| 2028 | $843,653 | $546,492 | $297,161 |
| 2029 | $933,334 | $576,949 | $356,385 |
| 2030 | $1,027,631 | $608,896 | $418,735 |
Rounded to whole dollars; source calculations retain more precision, so displayed differences may occur.
Projected revenue increases as fleet utilization and realized prices rise, without adding machines. EBITDA grows from $125,739 in 2026 to $418,735 in 2030 after direct, variable, fixed, and payroll operating expenses in the illustrated base case.
The Income Statement can extend the reporting view through depreciation, interest, taxes, and net profit using workbook assumptions. The supplied business-case figures stop at EBITDA; they do not establish those downstream accounting results.
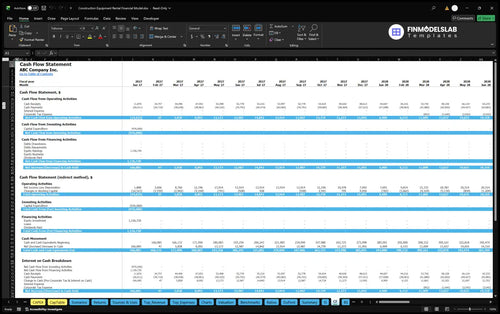
The Cash Flow Forecast separates operating, investing, and financing cash movements and reconciles opening to closing cash. It provides a liquidity view distinct from EBITDA, particularly when equipment spending and owner funding occur.
The Balance Sheet and combined Summary report provide working-capital, asset, funding, and financial-position views based on completed workbook inputs. Checks help identify reconciliation issues; the illustrated EBITDA table does not itself prove positive cash balances.
Returns and scenario reports answer different questions from the annual operating forecast and must be assessed using their own calculations.
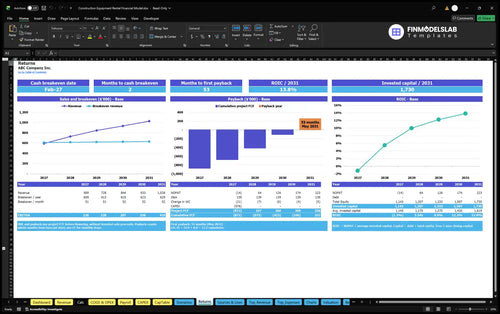
Sales break-even compares revenue with the level needed to cover modeled costs. Cash break-even concerns the timing of cumulative project cash recovery, while investment payback tracks capital recovery and annual ROIC compares returns with invested capital.
These measures cannot be derived from EBITDA alone. Use the workbook Returns and Cash Flow schedules with a complete capital, tax, and financing setup rather than interpreting the operating margin as an investment return.
The Returns analysis compares sales break-even, cash break-even timing, investment payback, and return on invested capital. Each measure uses its own denominator or cash-flow basis, so it should not be substituted for EBITDA or net profit.
Low, Base, and High scenario controls vary revenue and cost assumptions to compare revenue, margins, and EBITDA. The Valuation and Benchmarks reports offer additional DCF sensitivity and user-entered KPI comparisons, but no specific value, return, or industry benchmark is asserted here.
Answers to practical questions about modifying this fleet-based financial model and interpreting its reports.
Yes. The Revenue inputs include separate daily-equivalent hire rates for all five machine classes, which feed the monthly and annual revenue calculations.
No. This case uses one available fleet-day pool with annual utilization and normalized monthly seasonality; it does not add a separate demand forecast.
No. Outsourced local delivery is included in the realized rental prices and budgeted as a direct cost, so it is not counted twice.
Yes. CAPEX schedules asset spending and depreciation, while Dashboard debt controls can feed financing schedules. No outside loan is committed in the illustrated case.
No. EBITDA is an operating earnings measure; equipment investment, working capital, taxes, debt payments, and funding can change the cash-flow outcome.
No. The 2026–2030 amounts are illustrative estimates for the selected Charlotte rental-yard assumptions, not observed industry averages or validated local results.
The Returns worksheet provides break-even, cash recovery, investment payback, and annual ROIC functions, but the supplied business-case brief does not establish specific return values.
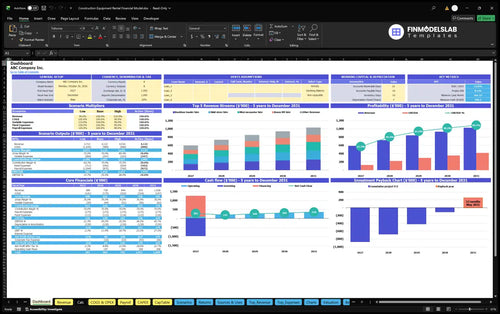
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
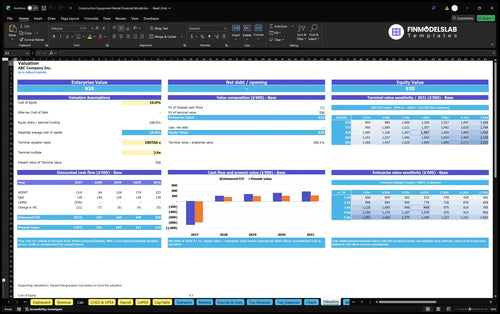
DCF valuation and sensitivity analysis.
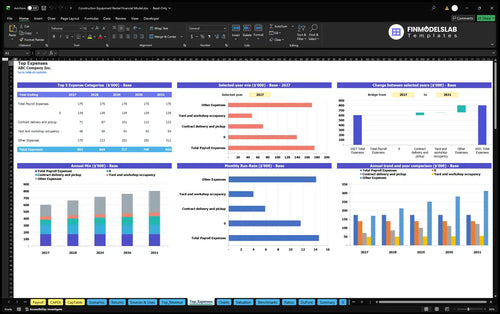
Largest costs and spending trends.
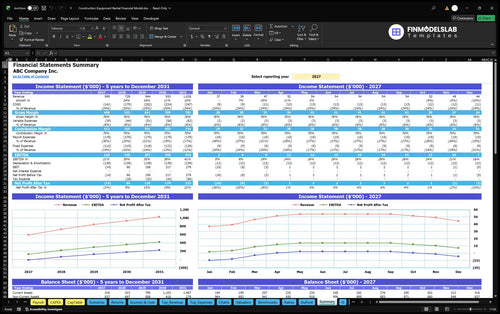
Annual and monthly financial performance.
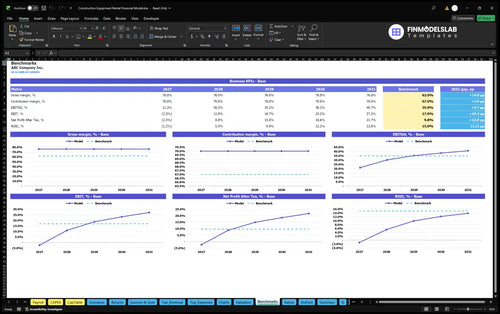
Compare margins and returns to benchmarks.

This template made margins and break-even easy to see, so I could stop guessing and adjust rental rates fast. I got a cleaner profit picture in one afternoon, which made our planning meeting a lot easier.

I liked how the structure kept one bad cell from snowballing into a bigger mess. It saved me hours of checking formulas and gave me confidence that the forecast stayed intact while I edited the inputs.
I wasn’t sure what investors wanted to see, but this model laid it out plainly. The output was organized enough that I could send it to our advisor and book a follow-up meeting without rewriting the whole thing.